

Maddy summaryHB 2448 establishes a new annual spending cap for Washington's state general fund, limiting growth to inflation and population changes starting in 2027. The cap automatically adjusts each November based on actual spending and economic forecasts, requiring the state treasurer to prevent overspending. It allows temporary 24-month exceptions only for declared natural disasters, not for routine budgeting. The bill does not change tax rates but aims to control budget growth through this spending limit.
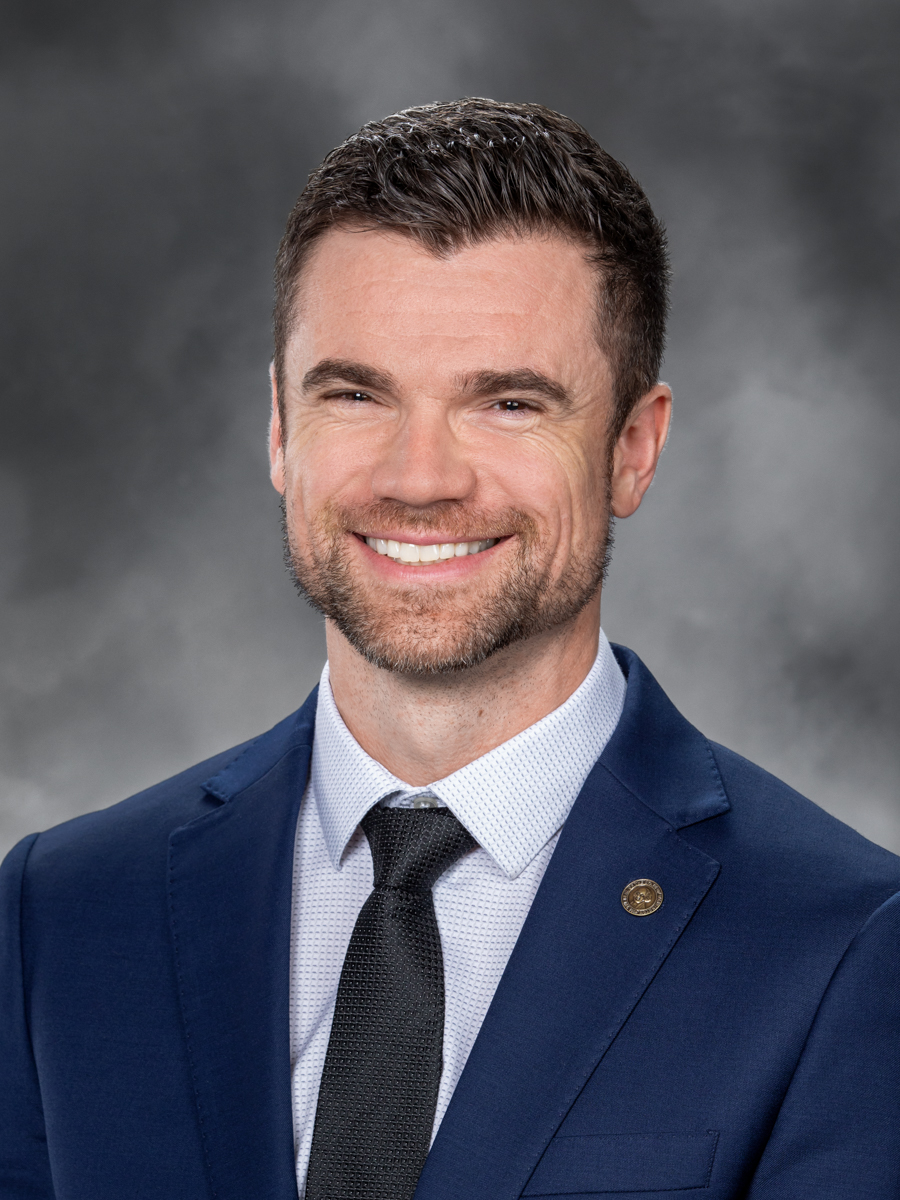
Rep. Skyler Rude
Sponsored bills
Maddy summaryHB 2449 requires Washington state agencies to conduct zero-based budget reviews for 20% of state programs every two years, starting in 2026, ensuring every program receives a review at least once every decade. The legislature selects which programs are reviewed each biennium (e.g., by area like education or health care), and agencies must submit detailed reports analyzing each program's purpose, costs, effectiveness, and alignment with agency goals. These reports must include data on funding, staffing, performance measures, and service levels, with public hearings required for review consideration. The governor and legislature must factor these reviews into budget decisions, aiming to improve transparency and efficiency in state spending.
Maddy summaryHB 2290 exempts schools and school districts in Washington State from paying retail sales and use taxes on purchases and property use. It directly affects public and private K-12 schools, educational institutions, and programs providing instruction to students through grade 12, regardless of their specific designation. The bill removes sales tax (RCW 82.08.020) from all purchases made by these entities and eliminates use tax obligations (RCW 82.12) for their personal property. This policy change simplifies tax compliance for schools and reduces their operational costs by excluding their purchases from state tax calculations.
Maddy summaryHB 2136 increases monthly retirement benefits for certain teachers' retirees under Washington's Plan 1 system. It provides a 1.5% benefit increase (capped at $62.50) for retirees receiving benefits as of July 1, 2017, effective July 2018, and three 3% increases (capped at $110) for retirees as of July 1, 2021-2025, effective July 2022-2026. The bill calculates each increase as a percentage of the retiree's current monthly benefit, but the total increase cannot exceed the specified cap. It excludes retirees covered by specific other retirement provisions under RCW 41.32.489 or 41.32.540.
Maddy summaryHB 2167 would automatically reduce Washington’s state sales tax rate if the legislature ever passes an income tax or tax on individual earnings. Specifically, the bill requires the Department of Revenue to lower the sales tax rate by an amount matching the projected revenue increase from such a new tax. This measure directly affects all Washington residents and businesses that pay sales tax, aiming to offset potential new tax burdens. The bill is conditional - it only triggers if a future income tax is enacted - and does not change current tax rates.
Maddy summaryHB 2101 exempts services involving live animals, birds, and insects from Washington's retail sales tax. This directly affects businesses like petting zoos, animal shows, and educational programs that provide live animal demonstrations. The bill amends the state tax code to explicitly exclude these services from the definition of "retail sale" under RCW 82.04.050. As a result, businesses offering such services will no longer be required to charge customers sales tax on these specific activities.
Maddy summaryHB 2166 amends Washington State law to grant state employees two unpaid religious holidays per year for observance of faith-based practices. It specifically adds a provision allowing employees to select two days annually for religious observance (e.g., Hanukkah, Eid al-Fitr, Passover) after consulting with employers, unless the absence would cause undue hardship. The bill does not create new paid holidays but expands existing unpaid holiday options for state workers, including those in schools and public institutions. It reaffirms existing state legal holidays while listing additional recognized days (like Hanukkah and Eid) that are not legally designated as paid holidays.
Maddy summaryHB 1236 increases penalties for littering in Washington State by creating tiered fines: a class 2 civil infraction for ≤1 cubic foot, a misdemeanor for 1-10 cubic yards, and a gross misdemeanor for >10 cubic yards. Offenders must pay restitution equal to 4x cleanup costs for misdemeanors or 2x for gross misdemeanors, with funds distributed to landowners and law enforcement. The bill also establishes a littering solutions task force under the Department of Ecology, requiring input from state agencies, counties, and industry groups (like waste management, retail, and tourism) to develop recommendations by November 2026. The task force must address specific issues like cigarette butts, road cleanup costs, and reducing litter at public sites such as parks and roadways.
Maddy summaryHB 1122 requires Washington public schools to restrict student mobile device use during instructional hours starting in the 2026-27 school year. It directs the state superintendent to report by December 2025 on successful strategies (like time limits or device storage) and exceptions (for emergencies, disabilities, or instructional needs), then mandates school districts to adopt compliant policies based on a state-developed model. The bill aims to reduce classroom distractions and support student mental health, citing research showing smartphones lower test performance by about six percent. It specifically excludes school-issued devices and applies to all public school districts, including charter and tribal schools.
Maddy summaryHB 1292 establishes an ongoing annual cost-of-living adjustment (COLA) for retirees in Plan 1 of Washington's Teachers' Retirement System (TRS) and Public Employees' Retirement System (PERS), starting July 2026. The bill uses the Consumer Price Index (CPI) to calculate annual increases, capping the first adjustment at 3% and limiting yearly changes to no more than a 3% difference from the prior year. It consolidates the costs of past COLA increases over a 15-year period while requiring new benefit improvements to be paid over a 10-year amortization. The bill directly affects current and future retirees in both systems who qualify under Plan 1, excluding those covered by specific exception provisions.