

Maddy summaryThe Access to Family Building Act establishes legal rights for individuals seeking fertility care and health care providers offering assisted reproductive technology (ART) services. It prohibits states or localities from imposing unreasonable restrictions on ART access - such as excessive costs, health barriers, or arbitrary limitations - that don’t advance safety or health outcomes. The bill allows patients, providers, or insurers to sue to enforce these rights, while explicitly preserving state health/safety regulations that protect patient safety. It does not override existing state insurance laws or require changes to medical facility safety standards. This bill directly affects patients pursuing fertility treatment, fertility clinics, and health insurers covering ART services.
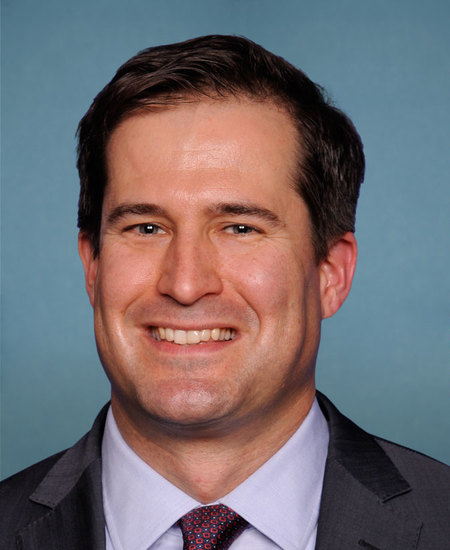
Rep. Seth Moulton
Sponsored bills
Maddy summaryThe Credit for Caring Act of 2025 creates a federal tax credit for family caregivers of elderly or disabled relatives. It allows eligible caregivers (with over $7,500 in earned income) to claim a credit equal to 30% of qualified caregiving expenses exceeding $2,000, capped at $5,000 per year. Qualified expenses include human assistance, home modifications, respite care, counseling, lost wages for unpaid time off, and transportation, all requiring certification from a licensed healthcare provider that the care recipient has long-term needs. The credit phases out for higher earners (over $75,000 single/$150,000 joint) and requires documentation of expenses and care recipient certification.
Maddy summaryHR 2029, the "Stop Comstock Act," amends federal obscenity laws to remove outdated restrictions on abortion and contraception. It deletes references to "indecent" materials and abortion-related language from Title 18 (e.g., removing "or means for procuring abortion" from section 552 and revising definitions in sections 1461 and 1462). The bill clarifies that federal law does not prohibit the distribution of materials related to abortion or contraceptives, updating how "obscene" is defined. These changes directly affect federal enforcement of obscenity laws, particularly regarding medical information and devices. The bill focuses on modernizing statutory language to align with current legal standards for protected speech and healthcare access.
Metastatic Breast Cancer Access to Care Act This bill expedites payment of Social Security Disability Insurance (SSDI) benefits and eligibility for Medicare coverage for those with metastatic breast cancer (i.e., breast cancer that has spread to other sites in the body). Specifically, the bill eliminates the 5-month waiting period for SSDI benefits and the subsequent 24-month waiting period for Medicare coverage for individuals with metastatic breast cancer. Under current law, individuals generally must wait 5 months after the onset of disability to begin receiving SSDI benefits and an additional 24 months to become eligible for Medicare.
Resident Education Deferred Interest Act or the REDI Act This bill allows borrowers in medical or dental internships or residency programs to defer student loan payments until the completion of their programs.
Maddy summaryThis bill blocks new U.S. defense export licenses to the United Arab Emirates (UAE) or its government agencies. It prohibits the export of specific military equipment (listed in U.S. regulations) until the President certifies the UAE is not supplying military aid to Sudan's Rapid Support Forces. The restriction applies to defense articles covered under U.S. export rules, including weapons and related technology. The bill directly affects U.S. defense exporters and the UAE government's ability to obtain new military equipment from the U.S.
Maddy summaryThis bill requires the Transportation Security Administration (TSA) to transition its workforce from a special personnel management system to the standard federal personnel system under Title 5 of the U.S. Code by December 31, 2025. It protects TSA employees by ensuring no reduction in pay, benefits, or retirement rights during the transition, while preserving collective bargaining rights for screening agents. The legislation also mandates consultation with labor unions during the process and requires several reports on workforce issues including recruitment, harassment policies, and workplace safety.
Maddy summaryThis bill changes how individual investors in mutual funds (regulated investment companies) are taxed on certain dividends. It allows investors to defer paying tax on capital gain dividends that are automatically reinvested in additional fund shares through a dividend reinvestment plan. The deferred tax is recognized later when the investor sells shares or upon their death. It also establishes that shares acquired through this reinvestment are treated as held for over one year from the start, potentially qualifying for long-term capital gains rates. The rule applies only to individual investors (not estates, trusts, or dependents claimed by others).
Maddy summaryThis bill adjusts probationary periods for certain federal employees who were involuntarily separated between January 20, 2025, and January 20, 2029. It allows eligible employees (those separated while on probation in an Executive agency) to count their prior service time toward a new probationary period when rehired into a similar position with their former agency. Specifically, the new probation period equals the original required duration minus the time already served in their previous federal role. The law expires on January 20, 2029, and applies only to appointments matching the employee’s prior position.
Maddy summaryHR 1990, the American Innovation and R&D Competitiveness Act of 2025, amends tax rules for businesses to make research and development (R&D) costs more flexible. It allows companies to deduct R&D expenses immediately as business costs (instead of capitalizing them) or to spread these costs over a minimum 60-month period. The bill clarifies which R&D expenses qualify, excludes land improvements and mineral exploration costs, and ensures companies can claim R&D tax credits without conflict with expense treatment. This directly affects businesses that conduct R&D, changing how they account for these costs on tax returns starting for 2022 taxable years.