

Maddy summaryHR 685, the SAVE Moms and Babies Act of 2025, prohibits the FDA from approving new abortion drugs or allowing investigational use of existing ones. It restricts existing abortion drugs to in-person administration by certified healthcare providers in clinics or hospitals (not pharmacies), limits use to pregnancies under 70 days gestation, and requires providers to certify they can handle complications like severe bleeding or ectopic pregnancies. The bill mandates reporting of adverse events (such as hospitalizations or infections) to the FDA without patient identifiers and defines "abortion drug" broadly as any drug intended to terminate pregnancy, excluding specific medical exceptions. This directly affects FDA approval processes, healthcare providers prescribing these drugs, and drug manufacturers.
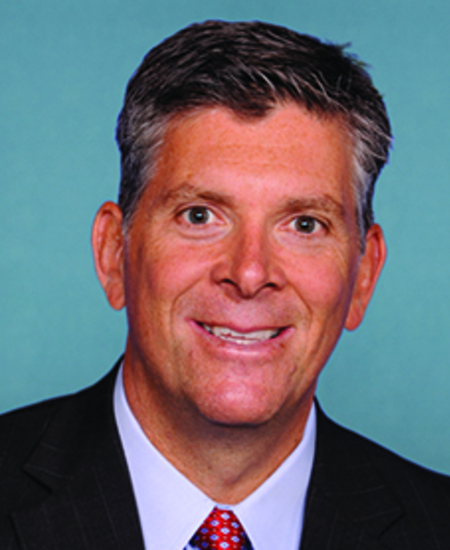
Rep. Darin LaHood
Sponsored bills
Maddy summaryHR 703, the Main Street Tax Certainty Act, makes a key tax deduction permanent for small business owners. It removes the temporary sunset provision (subsection (i)) from Section 199A of the tax code, ensuring the qualified business income deduction remains available for eligible small businesses. This change directly affects pass-through business owners (like S-corps, partnerships, and sole proprietorships) who currently qualify for this deduction. The permanent change takes effect for tax years starting after December 31, 2025.
Maddy summaryHR 682, the Heartbeat Protection Act of 2025, prohibits physicians from performing abortions without first checking for a detectable fetal heartbeat according to standard medical practice and informing the patient of the results. It directly affects physicians and clinics performing abortions, requiring them to document heartbeat checks and comply with strict exceptions for life-threatening conditions, rape (with 48-hour documentation of counseling/treatment), or incest involving minors (with proof of prior report to authorities). Violations could result in fines or up to five years in prison, though the bill explicitly states it does not create or recognize a right to abortion. The law adds detailed documentation requirements for exceptions and mandates retention of medical records per federal health privacy rules.
Maddy summaryHR 662 amends the tax code to change how oil and gas companies calculate taxable income related to intangible drilling and development costs. It allows companies to disregard certain depreciation and depletion expenses recorded on their financial statements when computing taxable income, effectively reducing their tax burden on these specific costs. The bill directly affects oil and gas producers who use intangible drilling costs in their operations. The changes apply to taxable years beginning after December 31, 2025. This is a tax code adjustment, not a direct policy change for energy production.
Maddy summaryHR 623, the LICENSE Act of 2025, modifies federal commercial driver’s license (CDL) regulations to improve testing flexibility and standards. It requires the Transportation Secretary to revise two key regulations: (1) allowing third-party examiners to administer knowledge tests only if they hold valid certification, complete specific training, and have 1 unit of required instruction (per 49 CFR §384.228), and (2) enabling any state to administer skills tests to CDL applicants regardless of their state of residence or where they received training (per 49 CFR §383.79). These changes directly affect CDL applicants, states administering tests, and third-party examiners. The bill focuses on streamlining testing processes while establishing clearer examiner qualifications and removing geographic barriers for skills testing.
Maddy summaryHR 640, the Chemical Tax Repeal Act, eliminates excise taxes on specific chemicals previously levied under Internal Revenue Code Chapter 38. It directly affects chemical manufacturers and distributors who paid these taxes on certain substances. The bill repeals the relevant tax provisions by amending the Internal Revenue Code, removing subchapters B and C of Chapter 38. This change takes effect on January 1, 2024, ending the tax requirement for covered chemicals.
Maddy summaryHR 7 prohibits federal funds from being used for abortions or health insurance plans covering abortion, with exceptions for pregnancies resulting from rape, incest, or when a woman's life is endangered. It blocks federal premium tax credits under the Affordable Care Act for health plans covering abortion (except in specified cases) and requires clear disclosure of abortion coverage and related surcharges in plan materials. The bill allows individuals or employers to purchase separate abortion coverage using non-federal funds, such as out-of-pocket payments, without affecting federal subsidies. It directly affects federal health programs, ACA marketplace plans, and health insurance issuers offering coverage that includes abortion services.
Maddy summaryThe ALIGN Act (HR 574) allows businesses to immediately deduct the full cost of certain qualifying equipment and property (like machinery or tools) instead of spreading the deduction over several years. This permanent tax change directly affects businesses that invest in eligible property placed in service after September 2017. The key provision eliminates the previous depreciation rules for these assets, providing an immediate tax benefit to encourage capital investment. It does not change tax rates or apply to all business expenses, only specific types of equipment meeting the defined criteria.
Maddy summaryThis bill requires the Treasury Secretary to regularly report to Congress about foreign countries that impose taxes on U.S. businesses or individuals considered unfair (extraterritorial or discriminatory taxes). For countries identified in these reports, it authorizes the U.S. to increase tax rates on income and withholdings from those countries, starting at 5% and increasing up to 20% over time. The bill also allows the U.S. to prohibit federal government purchases from entities in those countries and to consider these tax policies when negotiating tax treaties or trade agreements. It would directly affect U.S. businesses and individuals doing business with countries that have these tax policies, as well as those countries' businesses operating in the U.S.
Maddy summaryHR 563 requires the Bureau of Alcohol, Tobacco, Firearms and Explosives (ATF) to destroy all firearm transaction records from discontinued businesses within 90 days of the law's enactment. It also amends a federal law to prevent future registration of such transactions by removing language that required these records to be delivered to the Attorney General. The bill mandates that the ATF submit a report to Congress detailing how many records were destroyed. This legislation directly affects ATF record-keeping procedures, not individual gun owners or firearm ownership rights.