

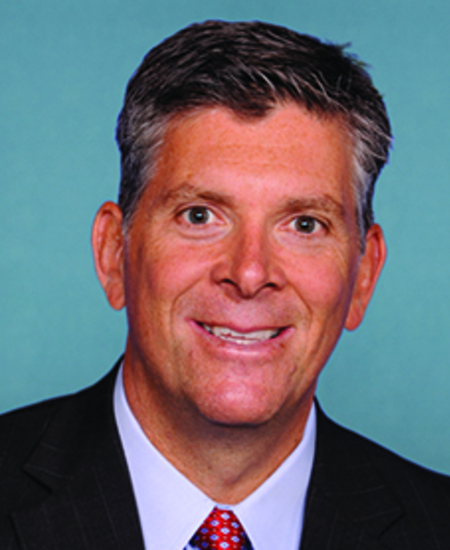
Photo of Darin LaHood
R United States House · District 16 · Illinois On the 2026 ballot

Rep. Darin LaHood

Compare
Total votes
2,837
all sessions
Attendance
97%
87 missed
Lower than 84% of chamber peers
With party
96%
of cast votes
Higher than 84% of chamber peers
Bipartisan score
2%
crosses aisle rarely
Lower than 84% of chamber peers
Sponsored
728
bills & resolutions
Near the chamber average
Committees
7
assignments
728 bills and resolutions

Sponsored bills

Total
728
Primary
98
Co-sponsor
630
This page
728
matching current filters
Co-sponsor HR 523
In committee · Indiana House · Co-sponsor
Permanent Tax Cuts for American Families Act of 2025

Maddy summaryThis bill makes permanent the increased standard deduction amounts for individual income tax filers. It raises the single filer standard deduction from $4,400 to $18,000 and the married filing jointly amount from $3,000 to $12,000 under the Internal Revenue Code. The bill also requires annual inflation adjustments to these amounts, using a specific formula based on the cost-of-living adjustment. These changes directly affect millions of American households that use the standard deduction instead of itemizing deductions on their federal tax returns.

In committee Jan 16, 2025 1 co-sponsor
Co-sponsor HR 539
In committee · Indiana House · Co-sponsor
Chiropractic Medicare Coverage Modernization Act of 2025

Chiropractic Medicare Coverage Modernization Act of 2025 This bill expands Medicare coverage of chiropractic services to include all services provided by chiropractors, rather than only subluxation corrections through manual manipulation of the spine.

In committee Jan 16, 2025 1 co-sponsor
Co-sponsor HR 516
In committee · Indiana House · Co-sponsor
To amend the Internal Revenue Code of 1986 to modify the railroad track maintenance credit.

This bill increases the annual limit on the tax credit for qualified railroad track maintenance expenses (also referred to as the short line railroad tax credit) and expands eligibility for claiming the credit. Under current law, the tax credit is limited each tax year to $3,500 multiplied by the sum of the number of miles of railroad track owned or leased by the taxpayer (miles owned or leased) and the number of railroad track miles assigned to the taxpayer by a Class II or III railroad (miles assigned). This bill increases the annual limit to $6,100 multiplied by the sum of miles owned or leased and miles assigned. The $6,100 amount used in the calculation of the tax credit limit is adjusted for inflation for tax years beginning after 2025. The bill also expands eligibility for the tax credit to include gross expenses for maintaining railroad tracks owned or leased as of January 1, 2024. Under current law, the tax credit is limited to gross expenses for maintaining railroad tracks owned or leased as of January 1, 2015.

In committee Jan 16, 2025 1 co-sponsor
Co-sponsor HR 483
In committee · Indiana House · Co-sponsor
Health Care Efficiency Through Flexibility Act

Maddy summaryHR 483 delays the requirement for Accountable Care Organizations (ACOs) to switch from CMS Web Interface reporting to electronic Clinical Quality Metrics (eCQMs) until January 1, 2030. It creates a pilot program starting in 2026 to test digital reporting methods with participating ACOs, exempting them from eCQM rules during the pilot while preserving their eligibility for incentive payments. ACOs may continue using existing reporting methods (like CMS Web Interface or MIPS CQMs) until 2030, with no penalties for non-compliance during the transition period. The bill also mandates the development of standardized digital reporting standards by 2030, requiring collaboration with healthcare stakeholders. This directly affects ACOs and their participants who report quality measures under Medicare programs.

In committee Jan 16, 2025 1 co-sponsor
Co-sponsor HR 524
In committee · Indiana House · Co-sponsor
NO GOTION Act

Maddy summaryHR 524, the "NO GOTION Act," blocks U.S. green energy tax credits for companies tied to specific countries. It amends tax law to deny benefits under sections like 30C, 45, and 48 to any "disqualified company" - defined as entities created in, controlled by, or linked to China, Russia, Iran, or North Korea. The law directly affects corporations with ties to these nations that seek federal tax incentives for clean energy projects. The policy takes effect for tax years after the bill's enactment, removing eligibility for these companies without altering other tax rules.

In committee Jan 16, 2025 1 co-sponsor
Co-sponsor HR 33
Passed · Indiana House · Co-sponsor
To amend the Internal Revenue Code of 1986 to provide special rules for the taxation of certain residents of Taiwan with income from sources within the United States.

Maddy summaryThis bill creates special tax rules for certain Taiwanese residents with income from U.S. sources, primarily addressing double taxation concerns. It reduces withholding tax rates on interest, dividends, and royalties from 30% to 10% (or 15% for certain dividends) for qualified Taiwanese residents, and eliminates tax on certain wages paid to Taiwanese workers in the U.S. It also sets a $30,000 annual limit on tax-free income from entertainment or athletic activities. To qualify, individuals must meet specific residency and ownership criteria, and the bill requires reciprocal tax benefits from Taiwan before taking effect. This legislation is designed to facilitate economic activity between the U.S. and Taiwan without requiring a formal tax treaty.

Passed Jan 16, 2025 1 co-sponsor
Co-sponsor HR 451
In committee · Indiana House · Co-sponsor
FAIR PREP Act of 2025

Maddy summaryThe FAIR PREP Act of 2025 prohibits the IRS from preparing individual tax returns or refund claims, except for the existing IRS Free File Program and certain qualified return preparation services. It clarifies that the IRS may still provide fillable tax forms with automated calculations and correct mathematical or clerical errors without violating the prohibition. The bill also bans the IRS from developing or operating new electronic tax preparation services after enactment without explicit new congressional authorization. This directly affects how the IRS delivers tax filing assistance, preserving current free options while restricting new government-run tools.

In committee Jan 15, 2025 1 co-sponsor
Co-sponsor HR 378
In committee · Indiana House · Co-sponsor
Thin Blue Line Act

Maddy summaryHR 378, the Thin Blue Line Act, adds a new aggravating factor for the death penalty in federal cases where a defendant kills or targets a law enforcement officer, firefighter, or other first responder. It specifically applies when the victim was killed or targeted while performing official duties, because of those duties, or due to their status as a public official. This amendment to federal death penalty law would make the death penalty a potential sentencing option for such crimes, as the killing would be considered an aggravating factor. The bill directly affects defendants convicted of homicides meeting these specific circumstances involving public safety personnel.

In committee Jan 14, 2025 1 co-sponsor
Co-sponsor HR 354
In committee · Indiana House · Co-sponsor
Small Business Growth Act

Maddy summaryHR 354, the Small Business Growth Act, increases tax deduction limits for small businesses purchasing equipment. It raises the annual deduction cap from $1 million to $2 million and the phaseout threshold from $2.5 million to $3.5 million under Section 179 of the tax code. These changes directly affect small businesses that buy qualifying depreciable assets like machinery or vehicles, allowing them to deduct more of the cost upfront. The provisions apply to property placed in service after December 31, 2025, with inflation adjustments updated to reference 2025 and 2026.

In committee Jan 13, 2025 1 co-sponsor
Co-sponsor HR 350
In committee · Indiana House · Co-sponsor
Prosecutors Need to Prosecute Act

Maddy summaryHR 350, the "Prosecutors Need to Prosecute Act," requires district attorneys in jurisdictions with 380,000 or more residents that receive federal Byrne grant funds to submit annual reports to the Attorney General. The reports must detail how many cases involving serious crimes - like murder, robbery, aggravated assault, and gun offenses - they referred for prosecution, declined, or resolved via plea deals, including data on repeat offenders and bail decisions. The Attorney General will establish uniform reporting standards and share the collected data with Congress and the public via a website. This bill directly affects large prosecutor offices receiving federal crime-fighting funds, aiming to increase transparency in prosecution practices for specific violent and property crimes.

In committee Jan 13, 2025 1 co-sponsor
Showing 211 to 220 of 728 bills
Previous 1 … 21 22 23 … 73 Next