

Maddy summaryHR 1024, the US-Kazakhstan Trade Modernization Act, terminates the application of Title IV of the Trade Act of 1974 to Kazakhstan. This means the U.S. will no longer apply special trade restrictions tied to Kazakhstan's emigration policies, as Kazakhstan has been found compliant since 1997. The bill allows the President to determine that Title IV no longer applies and extend normal trade relations (NTR) treatment to Kazakhstan's products. As a result, Kazakhstan's exports to the U.S. will be subject to standard U.S. trade rules rather than the specific Title IV provisions.
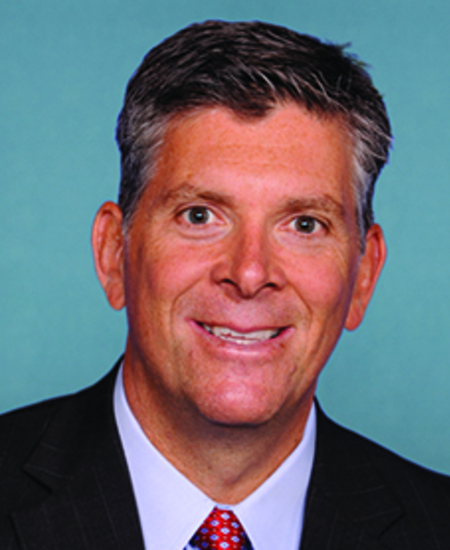
Rep. Darin LaHood
Sponsored bills
Maddy summaryHR 953 establishes a new Indo-Pacific Trade Strategy Commission to develop a comprehensive US trade strategy for the region. The bill directs the US International Trade Commission to study how existing agreements like RCEP and CPTPP affect US exports, supply chains, and competitiveness, and requires the Commission to submit recommendations within 18 months. The Commission, composed of 12 non-congressional experts, will focus on countering China's trade influence, promoting US economic leadership, and addressing supply chain vulnerabilities. This legislation directly affects US businesses, workers, and government policymakers by shaping future trade policy in a region critical to global economic growth.
Maddy summaryHR 833 creates a federal tax credit for individuals and corporations that contribute to scholarship granting organizations (SGOs) providing scholarships for elementary and secondary education. The credit allows taxpayers to deduct up to 10% of their adjusted gross income or $5,000 (whichever is less) for contributions to SGOs serving students from households with income up to 300% of the area median income. The bill establishes a $10 billion annual cap on the tax credit program, requires SGOs to verify student eligibility and maintain separate accounts, and prohibits government control over SGOs or private schools. It ensures scholarships can be used at public, private, or religious schools without discrimination based on religious character. The tax credit would be available for contributions made after December 31, 2025, with annual volume cap increases based on usage.
Maddy summaryHCONRES 4 is a symbolic resolution expressing Congress's support for tax-exempt fraternal benefit societies (like mutual aid organizations). It recognizes these groups, which have over 7 million members nationwide, as historically and currently providing critical community benefits - including life/health insurance, charitable work, and volunteer services - valued at over $3.8 billion annually. The resolution affirms that their tax-exempt status under Section 501(c)(8) of the Internal Revenue Code remains beneficial and should continue to be promoted. This is a non-binding expression of congressional sentiment, not a policy change.
Maddy summaryHRES 74 is a symbolic House resolution supporting Catholic schools and celebrating the 51st annual National Catholic Schools Week (January 26-February 1, 2025). It recognizes Catholic schools’ contributions, citing their role in educating 1.7 million students, serving diverse communities (including 20.5% racial minorities and 15.5% Hispanic students), and maintaining a 98.9% high school graduation rate. The resolution specifically applauds the National Catholic Educational Association and U.S. Conference of Catholic Bishops for their work in promoting Catholic education and the 2025 theme, "United in Faith and Community." As a procedural resolution, it has no legal effect but formally acknowledges these schools’ academic and community impact.
Maddy summaryHR 817, the Educational Choice for Children Act of 2025, creates a new tax credit allowing individuals to claim up to 10% of their adjusted gross income (capped at $5,000) for charitable contributions to scholarship granting organizations. These organizations provide education scholarships to eligible students from households with income not exceeding 300% of the area median gross income, covering qualified expenses like tuition, curriculum materials, and educational therapies. The bill establishes strict requirements for scholarship organizations, including verifying household income, conducting annual audits, and distributing scholarships to multiple students without government control. It also prohibits government entities from mandating or controlling scholarship organizations or excluding private or religious schools from receiving scholarship funds, while exempting scholarship amounts from taxable income for recipients. The tax credit is limited to $5 billion annually for 2025-2028, allocated on a first-come, first-serve basis.
Maddy summaryHR 786 extends Medicare incentive payments for providers participating in "eligible alternative payment models" (like bundled care programs) by adjusting key timeline and percentage references in the Social Security Act. It specifically delays the expiration of these incentives from 2026 to 2027 for certain payments (adding a 3.53% rate for 2027) and extends subsequent years' references accordingly. This bill directly affects Medicare providers using alternative payment models by preserving their access to these financial incentives for an additional year. The key mechanism is technical, updating specific years and payment percentages in Medicare law without changing the underlying program structure. The bill does not create new programs but ensures existing incentives continue for providers in 2027 and beyond.
Maddy summaryHR 801, the Charitable Act, creates a new tax deduction for individuals who do not itemize deductions on their federal tax returns. It allows these taxpayers to deduct up to one-third of their standard deduction amount for charitable contributions in 2026 and 2027. The bill directly affects non-itemizing individual taxpayers by providing a limited, direct deduction for charitable giving without requiring them to itemize. The deduction is capped at 1/3 of the standard deduction amount for those tax years, effective for returns filed in 2027 and 2028.
Life at Conception Act This bill declares that the right to life guaranteed by the Constitution is vested in each human being at all stages of life, including the moment of fertilization, cloning, or other moment at which an individual comes into being. Nothing in this bill shall be construed to authorize the prosecution of any woman for the death of her unborn child.
Maddy summaryHR 21, the Born-Alive Abortion Survivors Protection Act, requires medical staff at abortion facilities to provide the same immediate care and hospital admission to any infant born alive during an abortion as they would for any newborn. It mandates reporting failures to provide this care to law enforcement and imposes penalties of up to 5 years in prison for violations, with harsher penalties for intentional killing. The bill also allows women who undergo abortions to sue for civil damages, including triple the abortion cost, and provides for attorney fees. It defines "abortion" to exclude procedures performed after viability to preserve a live birth. This law directly affects healthcare providers at abortion facilities and creates new federal legal obligations for them.