

Maddy summaryHR 2925, the Maritime Fuel Tax Parity Act, extends an existing tax exemption for alternative motorboat fuels to small vessels operating exclusively between ports on the Atlantic or Pacific coasts of the United States. The bill amends the Internal Revenue Code to include these single-coast vessels under the current exemption, ensuring they pay the same excise tax rate as other qualifying vessels. This change applies to fuel sales after December 31, 2023, directly affecting small maritime businesses that operate only along one coastal region. The key provision modifies Section 4041(g) to clarify that the tax exemption covers these specific vessels, promoting tax parity without creating new taxes or altering broader fuel regulations.
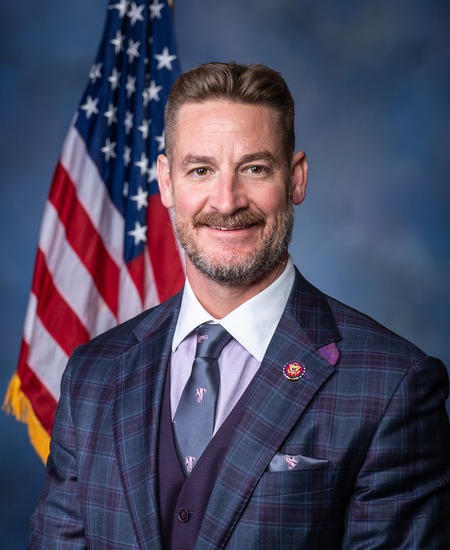
Rep. W. Gregory Steube
Sponsored bills
Maddy summaryThe STATES 2.0 Act would allow states to regulate cannabis markets within their borders without federal interference, while establishing a low federal excise tax that doesn't compound with state taxes. It would amend the Controlled Substances Act to exempt state-legal marijuana activities from federal prosecution, remove marijuana from the federal controlled substances schedule for state-compliant activities, and allow the FDA to regulate marijuana products as food, drugs, or cosmetics. The bill would require a study on marijuana legalization's effects on traffic safety and address regulatory barriers contributing to the illicit market, which currently accounts for 75% of the marijuana market. This legislation directly affects states that have legalized cannabis, marijuana businesses, and consumers by creating a regulatory framework that supports state autonomy and reduces illegal market activity.
Maddy summaryHR 2918, the "Family Business Legacy Act of 2025," would create a new estate tax deduction for bequests to specific nonprofit organizations. It allows estates to deduct the full value of transfers to organizations exempt under IRS sections 501(c)(4), (5), or (6), reducing the taxable value of an estate. This applies to estates of people who die after December 31, 2025, and directly affects individuals leaving assets to qualifying nonprofits like community foundations or social welfare groups. The bill does not change tax rates or directly support family-owned businesses, as the title suggests, but rather modifies how certain charitable bequests are treated for estate tax purposes.
Maddy summaryThe Safeguarding Charity Act clarifies that tax exemptions for charitable organizations under the Internal Revenue Code (such as 501(c) status) do not count as "federal financial assistance" for regulatory purposes. This means tax-exempt charities and nonprofits will no longer be subject to federal rules or requirements typically applied to organizations receiving direct federal funding. The bill amends U.S. Code to explicitly exclude tax benefits from the definition of "federal financial assistance" unless a law specifically states otherwise. It does not change tax status or funding for these organizations but prevents misclassification under existing regulations. The law applies to all organizations with tax-exempt status under sections 501(c) or 401(a) of the Internal Revenue Code.
Maddy summaryThis bill requires FEMA to reimburse local governments and electric cooperatives for interest paid on disaster recovery loans. It covers interest calculated as the lesser of actual payments or what would have been paid at the current prime rate, for loans where at least 90% of funds were used for disaster-related projects. The reimbursement includes interest from the past nine years and mandates FEMA to process payments within one year of the bill's enactment.
Maddy summaryThis bill expands Medicare coverage to include audiology services provided by qualified audiologists without requiring a physician referral or supervision. Starting January 1, 2027, Medicare will pay 80% of the standard rate for these services, which include hearing and balance assessments and treatment. It specifically allows audiologists to legally provide these services under state law, as long as they are covered if provided by a physician. The bill does not expand the types of services covered beyond those already payable under Medicare as of December 31, 2026.
Nuclear Family Priority Act This bill imposes limits on various types of family-sponsored immigration visas. The non-U.S. national ( alien under federal law) parents of U.S. citizens shall not qualify for visas for immediate relatives, which are not subject to any direct numerical limits. Currently, the spouses, unmarried children under 21, and parents of citizens are considered immediate relatives. The bill also creates a nonimmigrant visa for such parents of citizens. Such non-U.S. nationals shall not be eligible for employment or any public benefits. The bill also reduces the baseline annual cap for family-sponsored visas from 480,000 to 88,000, and revises the methods for calculating the cap. Currently, the 480,000 cap may be adjusted depending on various factors but shall not be less than 226,000. The bill eliminates preference allocations (visa categories subject to various annual caps) for various family-sponsored visas, including those for the siblings and married children of citizens. The bill provides for a preference allocation for the unmarried children under 21 and spouses of permanent residents, subject to the 88,000 annual cap.
Maddy summaryHR 2745, the Catch Up Act, allows married couples to both make extra contributions to their shared Health Savings Account (HSA) once they turn 55. Currently, only one spouse can make these "catch-up" contributions; this bill changes that so both spouses can contribute the additional amount if they qualify. It specifically allows the catch-up limit to be split equally between spouses (or agreed upon otherwise) if both are 55+ and have family health coverage under a high-deductible plan. The change applies to tax years starting after December 31, 2025.
Maddy summaryThis bill codifies Executive Order 14249 (signed March 25, 2025) into law, making its provisions about preventing fraud, waste, and abuse in federal spending legally binding. It directly affects all federal agencies managing taxpayer funds by requiring them to implement the order's specific measures. The key mechanism is converting the executive order into permanent statutory law, ensuring its requirements have enforceable legal effect rather than relying on executive authority alone. This does not create new spending rules but formalizes existing directives for oversight of government financial operations.
Maddy summaryHRES 287 is a procedural resolution that sets the rules for the House of Representatives to debate and vote on four specific bills and resolutions: S.J. Res. 18 (disapproving a consumer finance rule), S.J. Res. 24 (disapproving a digital payment rule), H.R. 1526 (limiting court injunctions), and H.R. 22 (requiring citizenship proof for voter registration). It waives all procedural objections to these measures, limits debate to one hour equally divided between committee leaders, and allows one motion to recommit for each. This resolution directly affects House members by enabling streamlined consideration of these measures without procedural delays.