

Passed Feb 1, 2018
1 co-sponsor
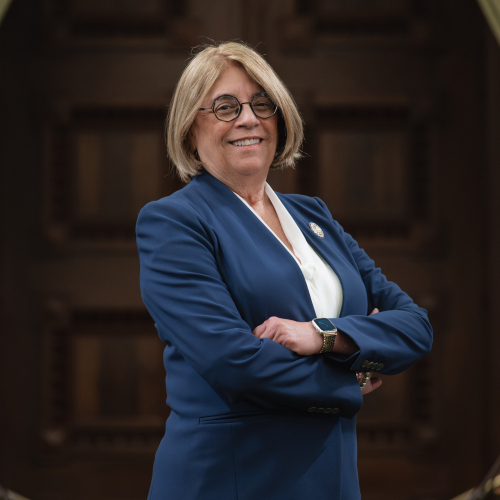
Asm. Cecilia Aguiar-Curry
Total votes
22,547
all sessions
Attendance
96%
805 missed
Near the chamber average
With party
99%
of cast votes
Near the chamber average
Bipartisan score
0%
crosses aisle rarely
Near the chamber average
Sponsored
2,169
bills & resolutions
Higher than 82% of chamber peers
Committees
13
assignments
2,169 bills and resolutions
Sponsored bills
Total
2,169
Primary
236
Co-sponsor
1,933
This page
2,169
matching current filters
Developmental services.
Existing law, the Lanterman Developmental Disabilities Services Act, requires the State Department of Developmental Services to contract with regional centers to provide services and supports to individuals with developmental disabilities. Existing law states the intent of the Legislature that persons with developmental disabilities have certain rights, including a right to prompt medical care and treatment and a right to be free from harm. This bill would instead provide that persons with developmental disabilities have the rights described above. The bill would also specify that it is declaratory of existing law that those rights apply to a person with developmental disabilities in a developmental center, community placement, or other housing placement.
Failed Feb 1, 2018
0 co-sponsors
Sales and use taxes: exemption: manufacturing and research: useful life: electric power generation.
Existing sales and use tax laws impose taxes on retailers measured by gross receipts from the sale of tangible personal property sold at retail in this state, or on the storage, use, or other consumption in this state of tangible personal property purchased from a retailer for storage, use, or other consumption in this state, measured by sales price. Those laws partially exempt from those taxes, for a specified period, the gross receipts from the sale of, and the storage, use, or other consumption of, specified tangible personal property purchased for use by a qualified person, as defined, to be used primarily in manufacturing or other processes, and in research and development. On and after July 1, 2014, tangible personal property with a useful life of one or more years, as defined by reference to state income or franchise taxes, is deemed to have a useful life of one or more years for purposes of the exemption. This bill would define "useful life" for periods on and after July 1, 2014, to also include tangible personal property that is expensed for state income or franchise tax purposes and that has a physical useful life of one or more years. The bill, with respect to property with a useful life of one or more years as redefined by this bill, would require the State Board of Equalization to cancel any notice of determination and any related penalties and interest and would prohibit the board from issuing any notice of determination with respect to the purchase or sale of that property. The bill would authorize a qualified person to offset the amount of sales tax reimbursement or use tax paid against any sales and use tax imposed on the qualified person when a qualified person has paid sales tax reimbursement or use tax on purchases of qualified tangible personal property that has a useful life of one or more years, as redefined by the bill, as provided. The bill, beginning on and after January 1, 2018, and before July 1, 2026, would additionally exempt from those taxes special purpose buildings and foundations used for the generation or production or storage and distribution, as defined, of electric power and qualified tangible personal property purchased for used by a qualified person to be used primarily in the generation or production or storage and distribution of electric power or purchased for use by a contractor for the qualified person, as specified. The bill, on and after January 1, 2018, would expand the definition of qualified person to include, among others, a person primarily engaged in the business of electric power generation. The bill would declare the intent of the Legislature to enact legislation that would improve the state's sales and use tax incentives to promote a stronger California economy by securing a greater share of the high-paying, high-skilled jobs in manufacturing and research and development.
In committee Feb 1, 2018
1 co-sponsor
Sales and use taxes: exemption: manufacturing and research: useful life: electric power generation.
Existing sales and use tax laws impose taxes on retailers measured by gross receipts from the sale of tangible personal property sold at retail in this state, or on the storage, use, or other consumption in this state of tangible personal property purchased from a retailer for storage, use, or other consumption in this state, measured by sales price. Those laws partially exempt from those taxes, until July 1, 2018, the gross receipts from the sale of, and the storage, use, or other consumption of, specified tangible personal property purchased for use by a qualified person, as defined, to be used primarily in manufacturing or other processes, and in research and development. Consumables with a useful life of less than one year do not qualify for exemption, and useful life is defined by reference to state income or franchise taxes. This bill, on and after January 1, 2018, and before July 1, 2028, would additionally define useful life by reference to manufacturer or other warranties, maintenance contracts, and normal replacement as established by industry or business practices, would additionally exempt from those taxes special purpose buildings and foundations used for the generation, production, storage, or distribution, as defined, of electric power, and would expand the definition of qualified person to include, among others, a person primarily engaged in the business of electric power generation. The bill would declare the intent of the Legislature to enact legislation that would improve the state's sales and use tax incentives to promote a stronger California economy by securing a greater share of the high-paying, high-skilled jobs in manufacturing and research and development. This bill would take effect immediately as a tax levy.
Failed Feb 1, 2018
1 co-sponsor
California Advanced Services Fund.
Under existing law, the Public Utilities Commission has regulatory authority over public utilities, including telephone corporations. Existing law establishes, among other funds related to telecommunications, the California Advanced Services Fund (CASF) in the State Treasury. Existing law requires the commission to develop, implement, and administer the CASF to encourage the deployment of high-quality advanced communications services to all Californians that will promote economic growth, job creation, and the substantial social benefits of advanced information and communications technologies, as provided in specified decisions of the commission and in the CASF statute. Existing law requires the commission to give priority to projects that provide last-mile broadband access to households that are unserved by an existing facilities-based broadband provider. Existing law establishes that the goal of the program is, no later than December 31, 2015, to approve funding for infrastructure projects that will provide broadband access to no less than 98% of California households. Existing law authorizes the commission to collect a surcharge for deposit into the CASF not to exceed $315,000,000 in total, authorizes the surcharge until 2020, and requires that those moneys be deposited into 3 specified accounts within the CASF, as specified. Existing law requires the commission to transfer a total of $25,000,000 from 2 of those accounts to a 4th account, the Broadband Public Housing Account, which is also in the CASF, but only if the commission is otherwise authorized to collect moneys for CASF purposes in excess of $315,000,000. This bill would repeal the condition that the commission must be authorized to collect more than $315,000,000 for CASF purposes before transferring the $25,000,000 to the Broadband Public Housing Account.
Failed Feb 1, 2018
0 co-sponsors
Farm labor contractors.
Existing law provides for the licensing and regulation of farm labor contractors by the Labor Commissioner. Existing law defines "farm labor contractor" for purposes of these provisions and excludes a commercial packing house, as specified, from the definition. This bill would also exclude a nonprofit organization that is engaged in administering an accredited apprenticeship program, as specified, from the definition of "farm labor contractor."
Failed Feb 1, 2018
0 co-sponsors
State responsibility areas: fire prevention fees: amnesty program.
Existing law requires the state to have the primary financial responsibility for preventing and suppressing fires in areas that the State Board of Forestry and Fire Protection has determined are state responsibility areas, as defined. Existing law requires that a fire prevention fee be charged on each habitable structure on a parcel that is within a state responsibility area, collected annually by the State Board of Equalization, in accordance with specified procedures, and specifies that the annual fee shall be due and payable 30 days from the date of assessment by the state board. Existing law authorizes a petition for redetermination of the fee to be filed within 30 days after service of a notice of determination, as specified. This bill would extend the time when the fire prevention fee is due and payable from 30 to 60 days from the date of assessment by the State Board of Equalization and would authorize the petition for redetermination to be filed within 60 days after service of the notice of determination, as specified. The bill would establish the Fire Prevention Fee Amnesty Program. The bill would require the State Board of Equalization to develop and administer the amnesty program for a person subject to the fees described above. The bill would require the program to be conducted for a 6-month time period, as provided, and would apply to fire prevention fee liabilities due and payable for the fee reporting periods beginning before March 1, 2018. The bill would require the program to apply to a person who meets specified requirements, including the filing of a completed amnesty application under penalty of perjury. By requiring the application to be completed under penalty of perjury, the bill would create a crime, and thus impose a state-mandated local program. The bill would require the state board to waive all penalties and interest for the specified fee reporting period for which the fire prevention fee amnesty is allowed for the nonpayment or underpayment of fee liabilities for a person who meets the above requirements. The bill would require the state board to adequately publicize the program so as to maximize public awareness of and participation in the program. The California Constitution requires the state to reimburse local agencies and school districts for certain costs mandated by the state. Statutory provisions establish procedures for making that reimbursement. This bill would provide that no reimbursement is required by this act for a specified reason.
Failed Feb 1, 2018
1 co-sponsor
Agricultural pest control: citrus disease prevention: funding.
Existing law creates the California Citrus Pest and Disease Prevention Committee in the Department of Food and Agriculture to, among other things, develop a statewide citrus specific pest and disease work plan. Existing law provides for a monthly assessment to be paid by producers, as defined, which is deposited in the Citrus Disease Management Account in the Department of Food and Agriculture Fund. Moneys in the Citrus Disease Management Account are available upon appropriation by the Legislature for specified activities relating to citrus disease prevention. This bill would appropriate $10,000,000 from the General Fund to the Citrus Disease Management Account in the Department of Food and Agriculture Fund, and would make those funds available for expenditure by the department, without regard to fiscal year, for the purpose of combating citrus specific pests, diseases, and their vectors.
Failed Feb 1, 2018
1 co-sponsor
Department of Transportation: broadband: fiber optic cables: priority areas.
Existing law provides that the Department of Transportation has full possession and control of state highways and associated property. Existing law requires the department to notify companies and organizations working on broadband deployment on its Internet Web site of specified department-led highway construction projects and authorizes those companies and organizations to collaborate with the department to install broadband conduits as part of those projects. This bill would require the department, as part of those projects that are located in priority areas, as defined, to install broadband conduits capable of supporting fiber optic communication cables.
Failed Feb 1, 2018
1 co-sponsor
Income and corporate taxes: credits: winter-flooded rice.
The Personal Income Tax Law and the Corporation Tax Law allow various credits against the taxes imposed by those laws. Existing law requires any bill authorizing a new income tax credit to contain, among other things, specific goals, purposes, and objectives that the tax credit will achieve, detailed performance indicators, and data collection requirements, as provided. This bill, for taxable years beginning on or after January 1, 2018, and before January 1, 2022, would allow as a credit against those taxes an amount equal to 40% of costs paid or incurred by a qualified taxpayer to maintain winter-flooded rice. The bill would require the qualified taxpayer to submit, among other things, evidence of costs paid or incurred to the Department of Food and Agriculture for certification and for the Department of Food and Agriculture to provide a copy of each credit certificate to the taxpayer and, upon request, to the Franchise Tax Board. The bill would also include the additional information required for any bill authorizing a new income tax credit. This bill would take effect immediately as a tax levy.
Failed Feb 1, 2018
0 co-sponsors
Ask Maddy
·
AI policy assistant
Ask Maddy about Cecilia Aguiar-Curry
Scope: california
Hi! I can help you understand Cecilia Aguiar-Curry's legislative record. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline