

Chiropractic Medicare Coverage Modernization Act of 2025 This bill expands Medicare coverage of chiropractic services to include all services provided by chiropractors, rather than only subluxation corrections through manual manipulation of the spine.
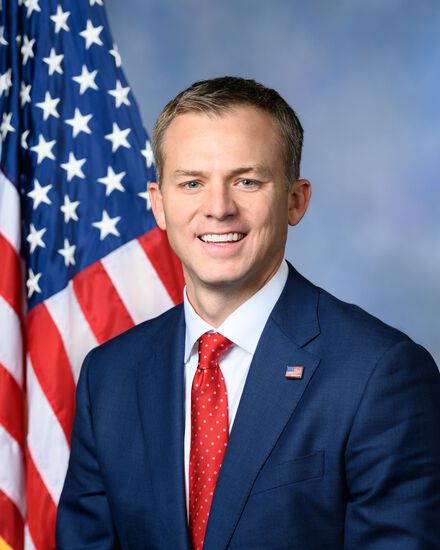
Rep. Blake D. Moore
Sponsored bills
This bill increases the annual limit on the tax credit for qualified railroad track maintenance expenses (also referred to as the short line railroad tax credit) and expands eligibility for claiming the credit. Under current law, the tax credit is limited each tax year to $3,500 multiplied by the sum of the number of miles of railroad track owned or leased by the taxpayer (miles owned or leased) and the number of railroad track miles assigned to the taxpayer by a Class II or III railroad (miles assigned). This bill increases the annual limit to $6,100 multiplied by the sum of miles owned or leased and miles assigned. The $6,100 amount used in the calculation of the tax credit limit is adjusted for inflation for tax years beginning after 2025. The bill also expands eligibility for the tax credit to include gross expenses for maintaining railroad tracks owned or leased as of January 1, 2024. Under current law, the tax credit is limited to gross expenses for maintaining railroad tracks owned or leased as of January 1, 2015.
Maddy summaryThis bill amends the Antiquities Act to require Congress, not the president, to authorize the creation or expansion of national monuments. It directly affects presidents and federal agencies by ending the current practice of presidentially designating monuments under the Antiquities Act. The key provision replaces the existing authority with a requirement for explicit congressional approval for any new monument or extension. This would change the legal process for establishing protected public lands, shifting decision-making power from the executive branch to Congress.
Maddy summaryThis bill creates special tax rules for certain Taiwanese residents with income from U.S. sources, primarily addressing double taxation concerns. It reduces withholding tax rates on interest, dividends, and royalties from 30% to 10% (or 15% for certain dividends) for qualified Taiwanese residents, and eliminates tax on certain wages paid to Taiwanese workers in the U.S. It also sets a $30,000 annual limit on tax-free income from entertainment or athletic activities. To qualify, individuals must meet specific residency and ownership criteria, and the bill requires reciprocal tax benefits from Taiwan before taking effect. This legislation is designed to facilitate economic activity between the U.S. and Taiwan without requiring a formal tax treaty.
Maddy summaryHR 404, the "Hearing Protection Act," reclassifies firearm silencers (devices that reduce gunfire noise) as firearms for federal tax and regulatory purposes. It imposes a 10% federal tax on silencers, requires the destruction of all existing federal silencer registration records within one year, and preempts state laws that tax or regulate silencers. The bill clarifies that silencers are treated as firearms under federal law, including for licensing and marking requirements, and defines "firearm silencer" to include specific components. Note: The bill’s title is misleading - it addresses firearm silencer regulation, not hearing protection for people.
Maddy summaryThe TRUST in Congress Act requires current and new Members of Congress, along with their spouses and dependent children, to place certain investments - such as stocks, commodities, and derivatives - into a blind trust within 90 to 180 days of taking office. It excludes U.S. Treasury securities and widely held mutual funds from this requirement and exempts investments tied to a spouse’s or dependent child’s primary job. Members must certify the trust’s setup to the House Clerk or Senate Secretary within 15 days, with these records posted publicly online. The act also prohibits dissolving such trusts until 180 days after a member leaves office.
Maddy summaryHR 376, the Historic Roadways Protection Act, prohibits the use of federal funds to finalize or implement specific travel management plans for certain areas in Utah during an ongoing legal period. The bill directly affects the Bureau of Land Management (BLM), blocking funding for 10 designated travel management areas (like the Henry Mountains and San Rafael Swell) and four specific plans (including the Indian Creek and San Rafael Desert plans) until all related R.S. 2477 legal cases are resolved. The restriction applies only to Utah lands and remains in effect from the bill's enactment until the Secretary of the Interior certifies the resolution of all 22 named legal cases. This is a funding prohibition, not a policy change to road access.
Maddy summaryThis resolution formally assigns members to four standing committees of the U.S. House of Representatives for the 119th Congress. It names specific representatives (e.g., Rep. Stefanik to Armed Services, Rep. Jordan to Oversight) without altering committee rules or policy. As a procedural resolution, it does not create new laws or affect constituents; it simply confirms committee membership under existing House rules. The resolution serves to organize House committee assignments at the start of the new Congress.
Maddy summaryThis bill would permanently expand the Child Tax Credit to provide $4,200 per year for each child under age 6 and $3,000 per year for each child ages 6-17. It also creates a new $2,800 credit for pregnant mothers with unborn children at 20 weeks gestation or more, requiring physician certification of gestational age. Both credits phase out for higher-income taxpayers, with the Child Tax Credit phasing out at $400,000 for joint filers and $200,000 for other taxpayers. The bill would affect low and middle-income families with children, particularly those with young children or who are pregnant, with changes applying to taxable years beginning after December 31, 2025.
Maddy summaryHR 354, the Small Business Growth Act, increases tax deduction limits for small businesses purchasing equipment. It raises the annual deduction cap from $1 million to $2 million and the phaseout threshold from $2.5 million to $3.5 million under Section 179 of the tax code. These changes directly affect small businesses that buy qualifying depreciable assets like machinery or vehicles, allowing them to deduct more of the cost upfront. The provisions apply to property placed in service after December 31, 2025, with inflation adjustments updated to reference 2025 and 2026.