

Tax on Wall Street Speculation Act This bill imposes an excise tax on the transfer of ownership in certain securities (covered transaction), including any share of stock in a corporation; any partnership or beneficial interest in a partnership or trust; any note, bond, debenture, or other evidence of indebtedness (excluding tax-exempt municipal bonds); and derivative financial instruments. The bill includes exceptions for initial issues, certain traded short-term indebtedness, and securities lending arrangements. The bill also (1) imposes a penalty on taxpayers who fail to include a covered transaction on their tax return or information statement, and (2) allows an individual taxpayer whose modified adjusted gross income does not exceed $50,000 ($75,000 for married taxpayers filing joint returns) a tax credit for the amount of tax paid on covered transactions.
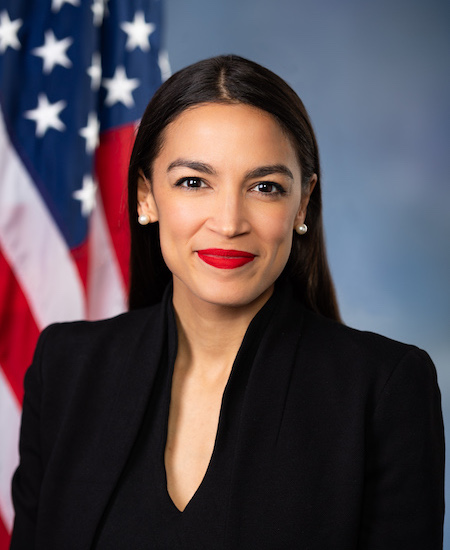
Rep. Alexandria Ocasio-Cortez
Sponsored bills
College for All Act of 2021 This bill establishes measures to expand access to higher education, including by eliminating tuition and required fees for eligible students, revising the Federal Pell Grant program, and reauthorizing certain programs to assist students from disadvantaged backgrounds. Specifically, the bill provides funding to eliminate tuition and required fees for (1) all students at community colleges and two-year tribal colleges and universities; (2) working- and middle-class students at four-year public institutions of higher education (IHEs) and tribal colleges and universities; and (3) eligible students at private, nonprofit historically Black colleges and universities (HBCUs) and minority-serving institutions. The bill permanently reauthorizes and otherwise revises the Federal Pell Grant program by providing funding to increase the maximum award for each eligible student, increasing the duration limit for the use of Pell Grants, and allowing students to use their awards to cover living and non-tuition expenses. Next, the bill makes Dreamer students (i.e., students who have been granted Deferred Action for Childhood Arrivals status) who entered the United States before the age of 16 and who meet certain educational criteria eligible for federal financial aid. Further, the bill requires the Department of Education to award grants to underfunded IHEs, HBCUs, and minority-serving institutions for investing in support programs to improve student outcomes (e.g., graduation rates). The bill also reauthorizes through FY2031 the Federal TRIO Programs and reauthorizes through FY2025 the Gaining Early Awareness and Readiness for Undergraduate Programs.
Civilian Climate Corps for Jobs and Justice Act This bill establishes a Civilian Climate Corps Program and generally revises benefits provided to national service program participants. The bill establishes a Civilian Climate Corps to operate (1) a national climate service program; and (2) a national climate service grant program to help communities respond to climate change and transition to a clean economy, including through reducing carbon emissions. The bill also provides for allowances for participants in certain national service programs, including the Volunteers in Service to America (VISTA) program and the National Civilian Community Corps. The bill expands the exclusion from gross income, for income tax purposes, to exclude amounts received as educational awards or benefits and income attributable to discharges of student loan debt under the National and Community Service Act of 1990.
Green New Deal for Public Housing Act This bill addresses energy efficiency and workforce development in the context of public housing. Specifically, the Department of Housing and Urban Development (HUD) must award grants to public housing agencies (PHAs) and other eligible entities under a variety of new programs, including programs for facilitating workforce development and high-income employment transition; conducting physical needs assessments and subsequent energy efficiency retrofits; and making upgrades, replacements, and improvements for energy efficiency, building electrification, and water quality upgrades. Recipients of these grants must provide relocation assistance for residents who are displaced during construction and must ensure that they can return to their homes once retrofitting is completed. A certain percentage of the employment positions generated by these grant programs and other specified federal grant programs must be filled by low-income individuals, and a specified percentage of certain contracts associated with these programs must be awarded to businesses owned by residents of public housing. The bill also repeals a provision that prohibits a PHA from using HUD funds to construct or operate new public housing units if doing so would result in the PHA owning or operating more units than it did on October 1, 1999.
Tax Fairness for Workers Act This bill allows an above-the-line tax deduction for union dues and expenses. (An above-the-line deduction is subtracted from gross income and is available whether or not a taxpayer itemizes other deductions.) The bill also reinstates the miscellaneous itemized tax deduction for unreimbursed expenses attributable to the performance of services as an employee (Under current law, all miscellaneous itemized deductions are suspended through 2025).
Defending the Human Rights of Palestinian Children and Families Living Under Israeli Military Occupation Act This bill limits U.S. assistance to Israel and establishes reporting requirements related to Israel's activities in the West Bank and its expenditures for offshore procurement. Specifically, the bill prohibits the use of any funds that are made available for assistance to Israel in support of (1) military detention, interrogation, abuse, or ill treatment of Palestinian children; (2) seizure, appropriation, or destruction of Palestinian property and forcible transfer of civilians in the West Bank; or (3) unilateral annexation by Israel of West Bank territory. The Department of State must report on the nature and extent of such activities carried out by Israel. Further, the Government Accountability Office must submit a report identifying and analyzing Israel's expenditures for offshore procurement, including (1) specific programs and items to which funds for offshore procurement in Israel have been allocated, and (2) identifying all end-use monitoring to which Israel is subject with respect to U.S.-origin defense articles.
For the 99.5 Percent Act This bill imposes increased tax rates on decedent estates, gifts, and generation-skipping transfers. Estates with a value of over $1 billion are taxed at a 65% tax rate. The basic exclusion amount is reduced to $3.5 million. The bill increases (1) to $3 million the reduction in valuations of farmland for estate tax purposes and adjusts such increased amount for inflation, and (2) to $2 million the maximum estate tax exclusion for contributions of conservation easements. It also increases to 60% the applicable percentage for such exclusion. The bill requires (1) consistent basis reporting for property acquired by gift and transfers in trust, and (2) executors of estates and donors of gifts required to file a gift tax return to disclose to the Department of the Treasury, and to recipients of any interest in an estate or a gift, information identifying the value of each interest received. The bill sets forth estate valuation rules for certain transfers of nonbusiness assets and limits estate tax discounts for certain individuals with minority interests in a business acquired from a decedent. The bill expands rules for valuing assets in grantor retained annuity trusts to require that (1) the right to receive fixed amounts from an annuity last for a term of not less than 10 years and not more than the life expectancy of the annuitant plus 10 years, and that such fixed amounts not decrease during the first 10 years of the annuity term, and (2) the remainder interest have a value when transferred that is not less than the the greater of 25% of the fair market value of the trust property or $500,000. The bill also sets forth rules for the application of transfer taxes to a grantor trust (a trust in which the grantor retains control over the trust assets and has the right to receive income from the trust). The bill eliminates the generation-skipping transfer tax exemption for any trust whose termination date is not greater than 50 years after its creation. The bill modifies the tax exclusion for annual gifts to eliminate the present interest requirement for such exclusion and to impose a new, aggregate per donor limit equal to twice the annual exclusion amount in effect for the taxable year.
Lead Abatement for Families Act of 2021 This bill requires the Department of Housing and Urban Development (HUD) to identify federally assisted housing projects that use lead-based water pipes and allows HUD to award grants for the replacement of these pipes to public housing agencies and other owners.
Commission to Study and Develop Reparation Proposals for African Americans Act This bill establishes the Commission to Study and Develop Reparation Proposals for African Americans. The commission shall examine slavery and discrimination in the colonies and the United States from 1619 to the present and recommend appropriate remedies. The commission shall identify (1) the role of the federal and state governments in supporting the institution of slavery, (2) forms of discrimination in the public and private sectors against freed slaves and their descendants, and (3) lingering negative effects of slavery on living African Americans and society.
Healthy Families Act This bill provides for paid and unpaid sick leave for employees to meet their own medical needs and those of their families. It requires employers with 15 or more employees to provide their employees with at least one hour of earned paid sick leave for every 30 hours worked, up to a maximum of 56 hours of paid sick leave in a year. An employer with fewer than 15 employees may also provide the same amount of paid sick leave, but may opt out of such requirement, in which case such employer must provide its employees at least 56 hours of unpaid leave in a year. An employee may use sick leave for absences (1) resulting from a physical or mental illness, injury or medical condition; (2) resulting from obtaining professional medical diagnosis or care, or preventive medical care; (3) to care for a child, parent, spouse, a domestic partner, or other blood or close relative; and (4) resulting from domestic violence, sexual assault, or stalking. The bill makes it unlawful for any employer to interfere with, restrain, or deny the exercise of an employee's right to accrue sick leave as provided by this bill. An employee may take legal action to enforce the right to sick leave granted by this bill and the Department of Labor must investigate complaints of violations of the requirements of this bill. Labor is authorized to conduct a public awareness campaign to educate and inform the public of the requirements for paid sick leave provided by this bill.