

Maddy summaryThis bill would prohibit the FDA from approving new abortion medications or investigational uses of existing ones. It would restrict currently approved abortion drugs to in-person administration only in clinics, hospitals, or medical offices by certified providers who can handle complications like ectopic pregnancy or severe bleeding. The law requires detailed adverse event reporting (excluding patient identifiers) to the FDA by both manufacturers and prescribers, and mandates provider certification covering pregnancy assessment, surgical intervention capabilities, and patient safety documentation. These provisions apply directly to healthcare providers, patients seeking medication abortions, and manufacturers of abortion drugs.
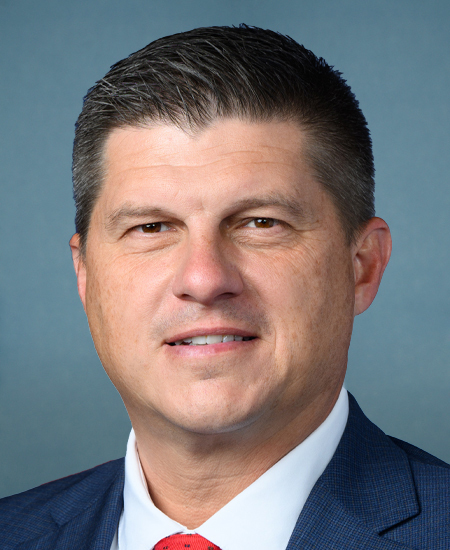
Rep. Brad Finstad
Sponsored bills
Maddy summaryThis bill prohibits federal funding to Planned Parenthood Federation of America and its affiliates for one year unless they certify they won't perform or fund abortions (with exceptions for rape/incest or life-threatening conditions). It redirects $235 million in existing funding to community health centers for women's health services like contraception, cancer screenings, and prenatal care. The bill explicitly states that redirected funds will continue to support all women's health services previously provided by Planned Parenthood. It also requires repayment of funds if Planned Parenthood violates the certification, and clarifies that overall federal funding for women's health services remains unchanged.
Protecting Life from Chemical Abortions Act This bill nullifies certain changes made by the Food and Drug Administration (FDA) to dispensing requirements for mifepristone. (Mifepristone is a drug that is approved to end pregnancies through 10 weeks gestation when used in conjunction with the drug misoprostol. The procedure is often referred to as medication abortion or the abortion pill.) The FDA regulates the use of mifepristone through the Mifepristone Risk Evaluation and Mitigation Strategy (REMS) program. The program requires health care providers to comply with certain requirements in order to prescribe or dispense mifepristone to end a pregnancy; the program previously included an in-person dispensing requirement that required mifepristone to be directly dispensed to patients in clinics, medical offices, or hospitals. During the COVID-19 public health emergency, the FDA temporarily stopped enforcing the in-person dispensing requirement, which allowed mail-order pharmacies to fill and dispense mifepristone prescriptions. In January 2023, the FDA modified program requirements so as to (1) remove the in-person dispensing requirement, and (2) require pharmacies to be certified in the program in order to dispense mifepristone. The modifications allow retail pharmacies, after receiving certification, to dispense mifepristone pursuant to prescriptions that are written by program-certified prescribers. The bill nullifies the January 2023 changes and prohibits the FDA from (1) exercising any enforcement discretion with respect to program requirements, or (2) reducing program protections until every state submits certain data regarding abortions to the Centers for Disease Control and Prevention. The bill also generally prohibits the declaration of a public health emergency with respect to abortions.
Maddy summaryThe Educational Choice for Children Act creates tax credits for individuals and corporations that contribute to scholarship granting organizations providing education scholarships. Individuals can claim a credit up to $5,000 or 10% of their income, while corporations can claim up to 5% of taxable income. The scholarships are available to students from households with income up to 300% of the area median income, and can be used for private school tuition, tutoring, and other educational expenses at elementary and secondary schools. The bill includes strict requirements for scholarship organizations to verify income, conduct audits, and prevent misuse of funds, while also prohibiting government control over these organizations and protecting private and religious schools from discrimination in the program. It establishes a $10 billion annual cap on the total tax credits available.
Maddy summaryThe Military Child Educational Freedom Act amends the tax code to allow active duty military families to deduct home school expenses as private school costs for federal income tax purposes. It specifically applies to military members or their spouses on active duty who use home schools recognized by state law as home or private schools. The bill changes the Internal Revenue Code definition of "private school" to include such home schools for education expense deductions. This change takes effect for tax years beginning after the bill's enactment.
Maddy summaryHR 496, the PELL Act, creates "Workforce Pell Grants" to support short-term workforce training programs instead of traditional college degrees. It directly affects students enrolled in qualifying short programs (150-600 hours, 8-15 weeks) that align with in-demand jobs. To qualify, programs must meet strict standards: 70%+ completion rates, 70%+ job placement rates, and demonstrate graduates earn at least 150% above the poverty line within three years. The bill also requires annual public reporting of program outcomes like completion rates, job placement, and graduate earnings to ensure accountability.
Maddy summaryThis bill expands foreign investment review to cover U.S. agriculture by requiring transactions involving foreign control of agricultural businesses to undergo scrutiny by the Committee on Foreign Investment (CFIUS). It classifies agricultural supply chains as both critical infrastructure and critical technologies, directly affecting foreign entities seeking to acquire or influence U.S. farms, food production, and supply chains. The bill mandates annual reports from the Secretary of Agriculture and the Government Accountability Office on foreign investments in agriculture, including risks to food security and intellectual property. These provisions aim to mitigate potential threats to U.S. food supply chains from foreign adversaries through enhanced oversight.
Maddy summaryThis bill prohibits all federal funding from being provided to EcoHealth Alliance, Inc. and its directly controlled subsidiaries, related organizations, or subgranted entities. It directly affects EcoHealth Alliance by cutting its access to federal grants, contracts, or other funding sources. The bill also requires the Government Accountability Office (GAO) to study and report on all federal funds provided to EcoHealth Alliance - whether intentionally or accidentally - to Chinese entities like the Wuhan Institute of Virology or the Chinese Communist Party, during the prior decade. The report must detail these funds and include any related agreements involving foreign entities. The bill focuses on restricting funding flows and requiring transparency, not on policy outcomes or advocacy.
Maddy summaryThis bill requires healthcare providers to give the same medical care to infants born alive during abortions as they would to any newborn, and to immediately admit such infants to a hospital. It mandates reporting of non-compliance to law enforcement and imposes penalties including up to 5 years in prison for violations. Women who undergo abortions can file civil lawsuits seeking money damages for injuries, three times the abortion cost, and punitive damages if care standards are not met. The bill also clarifies that abortion includes intentionally killing an unborn child or terminating pregnancy without specific exceptions (e.g., after viability to preserve life or removing a dead fetus).
Maddy summaryHR 23, the Family and Small Business Taxpayer Protection Act, rescinds unobligated funds previously allocated to the Internal Revenue Service (IRS) under the Inflation Reduction Act of 2022. Specifically, it cancels unused balances from certain IRS funding provisions (sections 10301(1)(A)(ii), (iii), (B), (2), (3), (4), and (5)) of the Inflation Reduction Act. This bill does not change tax laws or directly affect taxpayers; it only redirects unspent IRS budget authority. The provision applies solely to funds that were not obligated by the IRS as of the bill’s enactment date.