

Maddy summaryHR 479, the Healthy SNAP Act of 2025, revises which foods are eligible for purchase using Supplemental Nutrition Assistance Program (SNAP) benefits. It prohibits SNAP benefits from being used for alcoholic beverages, tobacco, soft drinks, candy, ice cream, and prepared desserts like cakes or pies. The bill requires the Secretary of Agriculture to establish regulations within 180 days designating specific foods that contain nutrients lacking in U.S. diets, promote health based on nutrition science, and align with cultural eating patterns, while limiting fat, sugar, and salt. The Secretary must also review and update these designations at least every five years to reflect current science, and states may substitute culturally appropriate foods if nutritionally equivalent. This directly affects SNAP recipients and the program's food eligibility rules.
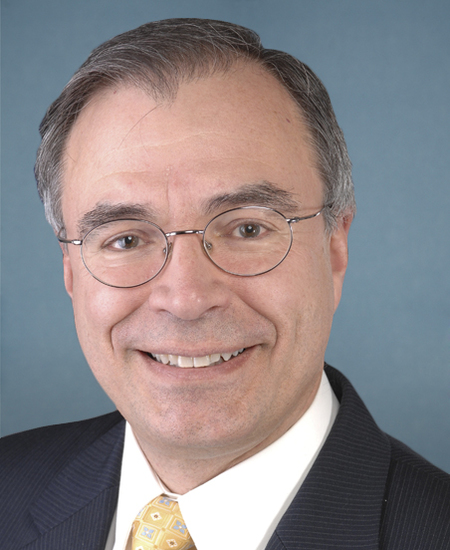
Rep. Andy Harris
Sponsored bills
This concurrent resolution declares that Congress should not impose any new performance fee, tax, royalty, or other charge relating to the public performance of sound recordings on a local radio station for broadcasting sound recordings over the air, or on any business for such public performance of sound recordings.
Maddy summaryHR 1301, the Death Tax Repeal Act, would eliminate the federal estate tax and generation-skipping transfer tax for estates of individuals dying on or after its enactment date. It directly affects individuals inheriting significant assets, as it removes taxes on estates exceeding $10 million (adjusted for inflation) and repeals taxes on large transfers between generations. The bill modifies the gift tax by establishing a $10 million lifetime exemption with annual inflation adjustments, replacing previous tax brackets. It applies to estates, gifts, and transfers occurring on or after the bill's effective date.
More Homes on the Market Act This bill increases the amount of gain from the sale of a principal residence that an individual may exclude from gross income (for federal tax purposes). Under the bill, an individual may exclude from gross income gain from the sale of a principal residence of up to $500,000 (currently $250,000), and taxpayers who are married and file a joint federal income tax return may exclude up to $1 million (currently $500.000). The bill also requires these amounts to be adjusted annually for inflation.
Maddy summaryHR 1351, the "Promoting American Patriotism In Our Schools Act," requires public elementary and secondary schools receiving federal education funds to implement specific patriotism-related practices. The bill mandates that all students, teachers, and staff recite the Pledge of Allegiance daily (with an exception for religious or personal reasons), prominently display the American flag in every classroom and gymnasium, and incorporate age-appropriate flag history and significance into civics or history curricula. Schools must annually certify compliance with these requirements to state education agencies, which then report to the federal government. This bill directly affects all public K-12 schools receiving funds under the Elementary and Secondary Education Act.
This bill repeals the Impoundment Control Act of 1974 (ICA). The ICA generally limits the authority of the President to impound (i.e., withhold from obligation or expenditure) funds that have been appropriated by Congress and establishes related procedures. It also establishes expedited legislative procedures that Congress may use to consider legislation to enact rescissions proposed by the President.
Maddy summaryThis bill, titled "Emergency Border Control Resolution," is actually a budget resolution establishing fiscal year 2025-2034 budget levels for the U.S. government. It sets detailed revenue, spending, and deficit targets across various government functions, including defense, health, and social programs. The resolution includes reconciliation instructions for committees to adjust laws within their jurisdictions to meet deficit targets. The title appears to be a political label rather than an accurate description of the bill's content, as it contains no actual border control provisions.
Maddy summaryThis bill redefines certain medical care arrangements for tax purposes. It creates a new category called "direct medical care service arrangements," which are fixed-fee payments (like a monthly subscription) for primary or specialty care directly from doctors, nurse practitioners, or physician assistants - bypassing traditional insurance. These arrangements will no longer be treated as "health plans" under tax law, and their fees will qualify as deductible medical expenses. Employers must also report these fees on employees' W-2 forms. The changes apply to tax years starting after December 2024.
Maddy summaryThis bill expands 529 college savings account flexibility by allowing funds to cover costs for industry-recognized postsecondary credentials, not just traditional degrees. It defines "qualified expenses" to include tuition/fees for recognized credential programs (like certifications or apprenticeships), required testing fees, and continuing education needed to maintain credentials. To qualify, programs must meet specific criteria, such as appearing on state lists under the Workforce Innovation and Opportunity Act or being listed in VA or Defense directories. The change applies to 529 distributions made after the law's enactment, giving families more options to use these accounts for job-focused training.
Maddy summaryHR 1040, the Senior Citizens Tax Elimination Act, would stop taxing Social Security benefits for seniors by repealing the current tax rule that includes some benefits in gross income. It directly affects senior citizens who currently pay federal income tax on portions of their Social Security payments. The bill adds a provision stating Section 86 of the tax code (which taxes Social Security benefits) no longer applies after enactment. To offset the lost tax revenue, the bill requires the government to appropriate funds to the Social Security and Railroad Retirement trust funds, ensuring they remain fully funded without requiring tax increases.