Requires the executive office of health and human services to increase Medicaid payment rates for primary care services furnished by primary care providers to be commensurate with Medicare rates.
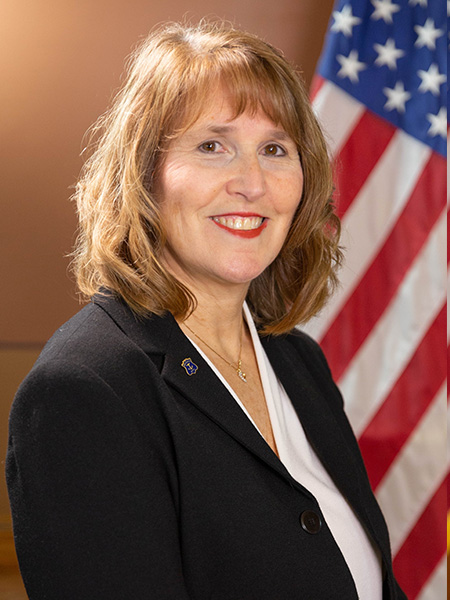
Rep. Michelle McGaw
Sponsored bills
Maddy summaryThis resolution symbolically declares June 3, 2025, as "Pharmacy Advocacy Day" in Rhode Island to recognize pharmacists' roles in healthcare. It does not create new laws or policies but encourages citizens, healthcare professionals, and organizations to participate in activities highlighting pharmacists' contributions to patient care and public health. The resolution specifically acknowledges pharmacists as accessible healthcare providers who support medication therapy and collaborate with other health teams. It has no direct regulatory impact on individuals or healthcare delivery.
Maddy summaryHB 5270 exempts the real and tangible personal property of the Friends of Little Compton Wellness Center, Inc. from local property taxes. This bill amends Rhode Island's property taxation law to specifically add this nonprofit organization to the list of entities eligible for tax exemption. The exemption applies to all physical assets (like buildings, land, and equipment) owned or used by the wellness center for its operations. This change directly affects only the Friends of Little Compton Wellness Center, Inc., providing them with tax relief on their property holdings. The bill passed through the legislature and became effective without the governor's signature on May 30, 2025.

Validates and ratifies the amendments to the Tiverton Home Rule Charter which were approved by the electors of the town of Tiverton on November 5, 2024.
Maddy summaryHR 6017 would allocate $450,000 in state funds to the Rhode Island Food Bank for the 2025-2026 fiscal year. This funding aims to address Rhode Island's food insecurity crisis, where 38% of households face difficulty accessing food and a $400 million funding gap is projected. The resolution directs the state controller to pay the funds upon receipt of proper documentation. This is a direct funding measure to support existing food bank operations, not a new program.
Maddy summaryHB 5974 expands eligibility for the state's crime victim compensation program to include victims of hit-and-run incidents that cause serious bodily injury or death. The bill amends existing law to explicitly add "failure to stop by a driver in circumstances which result in serious bodily injury or death" as a qualifying offense under the program. This means victims of such hit-and-run accidents, who previously might not have been covered, can now apply for financial assistance through the compensation program. The change directly affects individuals injured or killed in hit-and-run crashes where the driver fled the scene.
Adds to those persons exempt from payment of parking fees at any recreational facility owned and operated by the state those individuals determined by the executive office of HHS, or its designee, to be disabled for purposes of Medicaid eligibility.
Maddy summaryHB 5738 proposes a tax credit for individual taxpayers in Rhode Island who convert their gas-powered vehicles to run on alternative fuels. This credit covers equipment and labor costs incurred for the conversion. Taxpayers can receive up to 50% of these costs, with a maximum credit of $2,000 for lighter vehicles and $3,000 for heavier vehicles. Eligible alternative fuels include natural gas, electricity, hydrogen, and certain other fuel types. The credit cannot exceed the taxpayer's income tax liability and takes effect for the 2026 tax year.
Maddy summaryHB 5475 proposes to exempt new and used bicycles from state sales and use taxes. This means that individuals purchasing a bicycle would no longer be charged sales tax on that transaction. The bill amends existing state laws that outline which goods and services are exempt from sales and use taxes, adding bicycles to that list. This change directly affects consumers who buy bicycles and businesses that sell them.
Maddy summaryHB 5468 proposes to modify how the state's motor fuel tax is adjusted for inflation. Beginning July 1, 2025, and every two years thereafter, the gasoline tax rate will be updated based on the percentage increase in the Consumer Price Index for all Urban Consumers. The bill specifies that this adjustment will now reflect inflation over the preceding two-year period, rather than the current one-year period. The updated tax rate will be rounded to the nearest cent and cannot fall below the existing 32 cents per gallon, affecting motor fuel distributors and ultimately consumers.