

Maddy summaryHB 1204 modifies interest rates for unpaid taxes and refund delays in Oklahoma. It sets interest on delinquent taxes at the prime rate plus 2% (published in *The Wall Street Journal*), while changing refund interest deadlines: taxpayers get interest on refunds not paid within 90 days (for most returns), 30 days for electronic filings (2004-2010), or 45 days (2010+). The bill directly affects all Oklahoma taxpayers who owe taxes or are due refunds, including individuals and businesses. It becomes effective November 1, 2025.
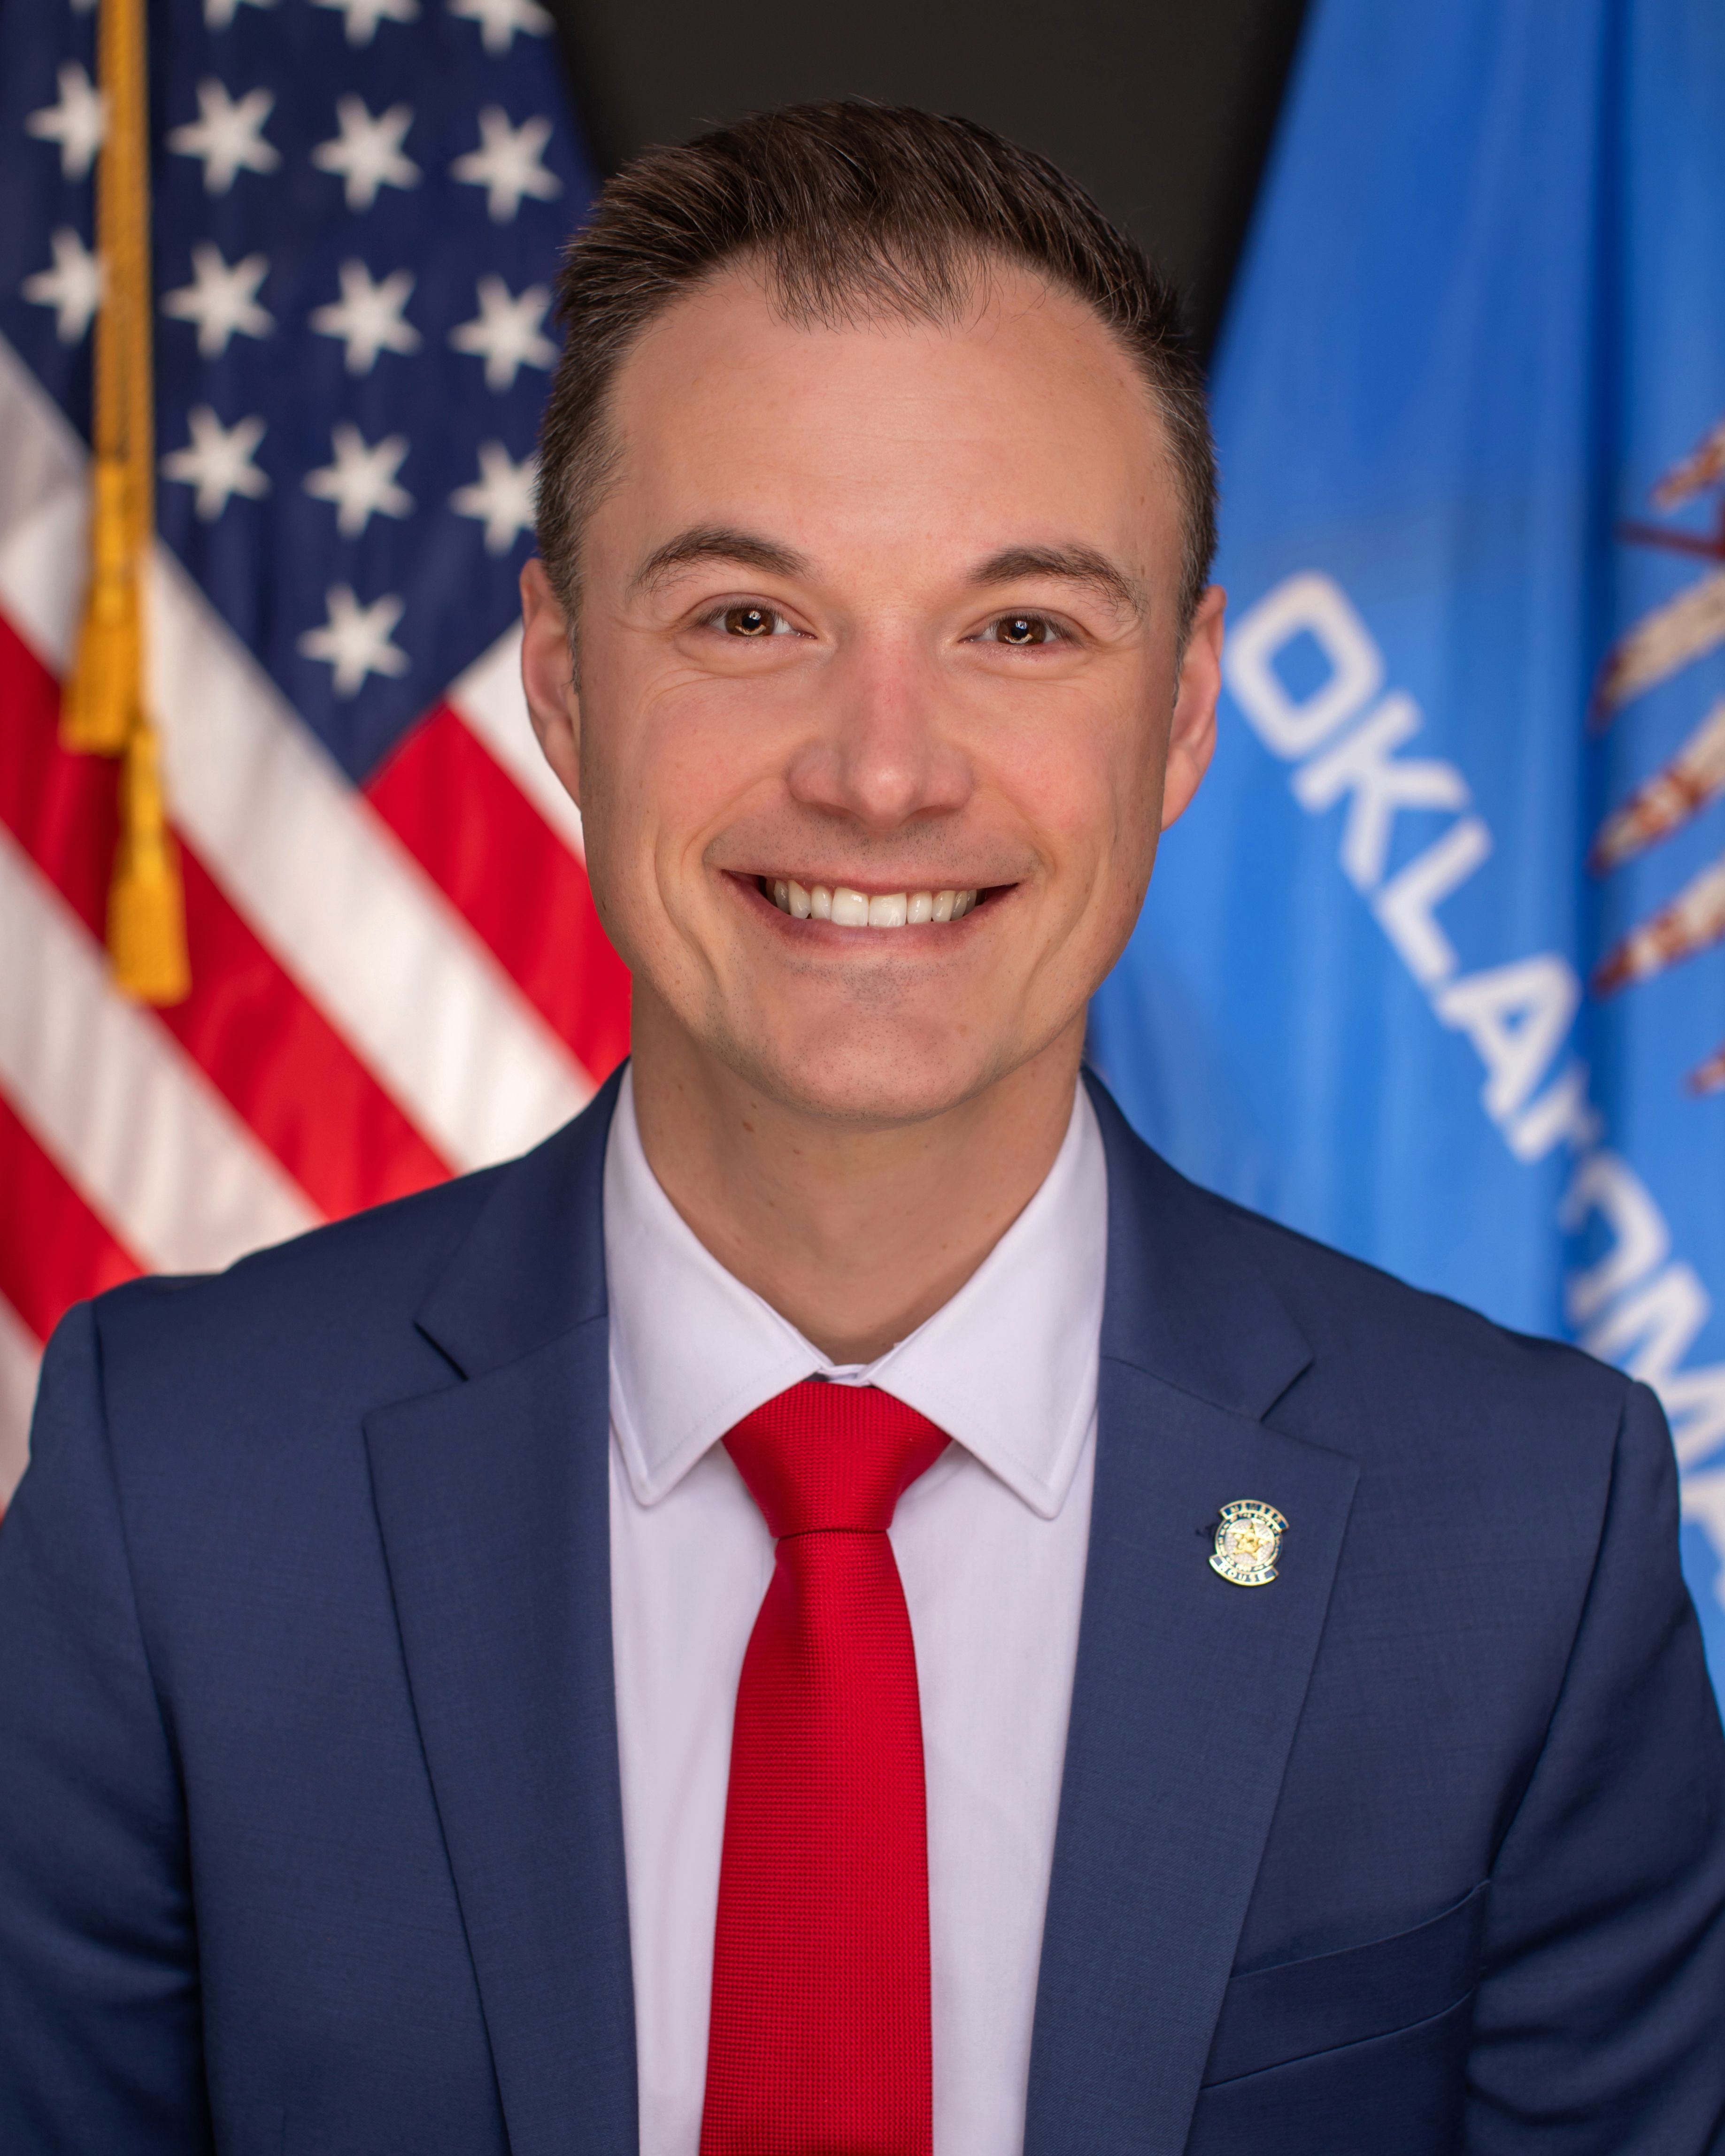
Rep. Cody Maynard
Sponsored bills
Maddy summaryHB 1206 amends Oklahoma's individual income tax code to lower tax rates for all taxable years beginning in 2024. It reduces rates across all income brackets - for example, lowering the top rate for single filers from 5.50% to 4.75% on income above certain thresholds, with similar reductions for married filers. The bill also eliminates the deduction for federal income taxes paid when calculating taxable income. This affects all Oklahoma residents and nonresidents filing individual income tax returns. The changes take effect for tax years starting in 2024.
Maddy summaryHB 1209 modifies Oklahoma's individual income tax structure for tax years beginning in 2024 and 2026. For 2024-2025, it lowers the top marginal tax rate from 5.5% to 4.75% for both single filers and married couples filing jointly, while reducing rates across all income brackets (e.g., 0.25% on the first $1,000 for singles instead of 0.5%). The bill also eliminates the deduction for federal income taxes paid when calculating Oklahoma taxable income. This directly affects all Oklahoma residents and nonresidents filing state income tax returns. The 2026+ tax rates are referenced but not fully detailed in the provided text.
Maddy summarySB 66 creates the Oklahoma Southeastern Regional Airport Improvement Revolving Fund to finance airport upgrades at small regional airports. It specifically targets airports located east of U.S. Highway 69, south of U.S. Highway 70, and within Oklahoma municipalities with populations between 10,000 and 20,000 people. The fund requires $10 million in matching contributions from local, county, tribal, federal sources, or donations before state funds can be used for repairs, improvements, or air traffic control towers. The bill appropriates $10 million from the state's General Revenue Fund, with unspent funds transferring to the General Revenue Fund by July 1, 2027, if no eligible projects are approved.
Maddy summarySB 425 updates Oklahoma's property tax relief program by lowering the age requirement for eligibility from 65 to 60 years and raising the income limit from $12,000 to $40,000 for gross household income. This change directly affects older Oklahomans (60+) and totally disabled individuals who are heads of households and reside in the state year-round. Eligible residents can now claim property tax relief on their primary residence if their prior year's household income stays below $40,000, with only one claim permitted per household annually. The bill takes effect November 1, 2025, and updates administrative procedures for filing claims.
Maddy summaryThis Oklahoma bill (SB 114) clarifies and updates existing rules about non-citizens owning land. It defines "bona fide resident" as a lawful permanent U.S. resident and specifies that current non-citizen landowners retain their property. The law allows non-citizens who become bona fide residents to own land on the same terms as citizens, but requires them to sell property within five years if they stop living in Oklahoma. The bill makes statutory language gender-neutral and declares an emergency to take effect immediately.
Maddy summaryHB 1202 amends Oklahoma's sales and use tax remittance rules by reducing the vendor retention rate from 1% to 0.5% for certain tax collections. This change directly affects businesses (vendors) that collect sales tax on transactions, requiring them to remit a lower percentage of collected taxes to the state. The key provision modifies the statutory rate in the tax code to decrease the amount vendors must hold back from customer payments. The bill is currently pending in the Appropriations and Budget Finance Subcommittee.
Maddy summaryOklahoma's SJR 15 proposes a constitutional amendment to eliminate all property taxes by January 1, 2030, replacing them with county-level consumption taxes on goods and services sold to end consumers. Counties would need to develop voter-approved proposals by January 2028, including new service districts and tax rates, with final voter approval required for any tax levy by January 2029. The amendment requires counties to fund schools and services previously supported by property taxes through these consumption taxes, prohibits tax exemptions, and mandates special elections if proposals are rejected. This would directly affect all Oklahoma counties and their voters, with the first tax levies scheduled to take effect in 2030.
Maddy summaryHB 3031 amends Oklahoma law to add ambulance districts to the list of entities exempt from state motor fuel taxes. This change directly affects rural ambulance service districts and ambulance districts established under the Oklahoma Constitution by allowing them to use fuel without paying the applicable tax. The bill also updates the existing list of other tax-exempt uses, which includes schools, agricultural operations, and various public service organizations. The new exemption takes effect on November 1, 2024.