

Maddy summaryHB 5074 appropriates additional funds from the General Fund to the Department of Energy and Environmental Protection for farmland preservation during the 2026-2027 fiscal year. The bill directly affects farmland preservation programs by increasing available funding for land conservation efforts. Key provision: It allocates specific budget resources to support the state's existing farmland preservation initiatives. This is a funding measure, not a new policy, aimed at strengthening current conservation work without altering program rules.
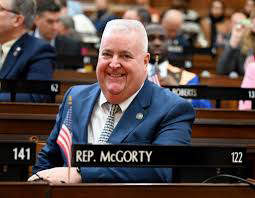
Rep. Ben McGorty
Sponsored bills
Maddy summaryHB 5079 repeals a $5 annual fee called the "Passport to the Parks" that was added to motor vehicle registrations. This change directly affects all vehicle owners in the state who previously paid this fee when registering their cars. The bill simply removes the fee from the law, eliminating the charge without creating new programs or requirements. It does not alter park access or funding mechanisms, only eliminating the registration fee. The bill is procedural and focuses solely on removing this specific fee from statute.
Maddy summaryHB 5065 would create a personal income tax deduction for stipends paid to volunteer firefighters and volunteer ambulance members. The deduction applies to stipends received from municipalities, volunteer fire departments, or volunteer ambulance associations. This would reduce the taxable income of qualifying volunteers who receive these small payments for their service. The bill directly affects volunteer emergency responders in these roles who currently have no tax relief for such stipends.
Maddy summaryHB 5064 creates a $5,000 annual tax credit for farmers who donate food to charitable organizations, adjusted each year based on inflation using the consumer price index. This credit directly benefits farmers by reducing their state tax liability for food donations and supports charitable organizations receiving surplus food. The bill establishes a concrete financial incentive to encourage food donations, aiming to reduce waste while aiding food-insecure communities. It does not change existing food donation laws but provides a new tax benefit for qualifying donations.
Maddy summarySB 95 creates a $500 credit against personal income tax for employees working at defense contractors or their direct suppliers/subcontractors. To qualify, individuals must earn under $125,000 annually as single filers or under $250,000 as married couples filing jointly. The credit directly benefits lower-to-moderate income workers in the defense supply chain by reducing their state tax burden. This is a specific tax incentive targeting employees in defense-related industries, not a general tax cut. The bill establishes this credit through an amendment to existing tax law.
Maddy summaryThis bill appropriates $150,000 from the General Fund to the Department of Energy and Environmental Protection for the fiscal year ending June 30, 2027. The funds are specifically designated to cover the disposal of surface debris at the mouth of the Housatonic River in Stratford. The bill directly affects the town of Stratford and the state's environmental cleanup efforts by providing targeted funding for this specific debris removal project. It does not create new regulations or alter existing laws, but rather allocates existing budget resources for a defined environmental maintenance task.
Maddy summarySB 64 authorizes Connecticut to issue up to $1 million in state bonds to fund renovations at the Connecticut Air and Space Center in Stratford. The proceeds will be provided as a grant to the Center through the Department of Economic and Community Development for upgrading an existing hangar. This funding directly supports the Center’s operations, specifically expanding its educational and community programming. The bill focuses on physical infrastructure improvements rather than new facilities or broader policy changes.
Maddy summarySB 28 requires the state budget for fiscal year 2027 to appropriate funds directly from the General Fund to support nine regional fire training schools, rather than using specific taxes or fees like insurance premium surcharges. This bill directly affects the nine regional fire training schools by securing their funding through standard state budget appropriations. The key provision mandates that funding must come from the General Fund in the state budget, eliminating reliance on targeted revenue sources. The bill does not change the schools' operations but specifies how their funding will be allocated. This is a procedural budgetary measure with no new policy requirements.
Maddy summarySB 42 creates a tax credit that allows taxpayers to reduce their personal income tax bill by the amount paid for Medicare and Medicare Advantage plan premiums. This directly affects individuals who pay Medicare premiums and file personal income tax returns. The credit applies to premiums paid during a taxable year and lowers the taxpayer's overall income tax liability. The bill does not change Medicare eligibility or premium amounts but provides a direct tax benefit for those already paying for Medicare coverage.
Maddy summarySB 70 would exempt all Social Security benefits and pension or annuity income from state personal income tax for every taxpayer. This policy change directly affects residents receiving these income types, removing them from the taxable base. The bill amends Section 12-701 of the general statutes to implement this universal exemption. It creates a concrete tax relief measure without altering other income tax provisions.