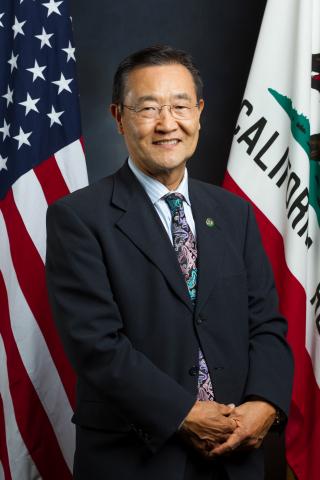
Photo of Steve Choi
R California Senate · District 37

Sen. Steve Choi

Compare
Total votes
16,057
all sessions
Attendance
84%
2,232 missed
Near the chamber average
With party
98%
of cast votes
Near the chamber average
Bipartisan score
1%
crosses aisle rarely
Near the chamber average
Sponsored
1,211
bills & resolutions
Near the chamber average
Committees
5
assignments
1,211 bills and resolutions

Sponsored bills

Total
1,211
Primary
190
Co-sponsor
1,021
This page
1,211
matching current filters
Co-sponsor ACR 216
Signed into law · California Assembly · Co-sponsor
Relative to 529 College Savings Day.

This measure would designate May 29, 2018, as 529 College Savings Day, to raise awareness about the importance of saving for college with the help of 529 college savings plans.

Signed into law Jun 1, 2018 1 co-sponsor
Primary AB 1803
In committee · California Assembly · Lead sponsor
Postsecondary education: career placement and job search services for graduates.

Existing law establishes the California Community Colleges, under the administration of the Board of Governors of the California Community Colleges, the California State University, under the administration of the Trustees of the California State University, the University of California, under the administration of the Regents of the University of California, independent institutions of higher education, and private postsecondary educational institutions as the segments of postsecondary education in this state. This bill would require a public or private institution of higher education that offers a baccalaureate degree program, provides career placement and job search services to students, and receives state funds for student financial assistance to provide career placement and job search services to a person for five years after the person receives a baccalaureate degree at the institution.

In committee May 25, 2018 0 co-sponsors
Primary AB 2932
In committee · California Assembly · Lead sponsor
Corporation Tax Law: credit: employment.

The Corporation Tax Law allows various credits against the taxes imposed by that law. Existing law requires any bill authorizing a new tax credit to contain, among other things, specific goals, purposes, and objectives that the tax credit will achieve, detailed performance indicators, and data collection requirements. This bill, for each taxable year beginning on and after January 1, 2019, and before January 1, 2024, unless the annual budget act lacks a specific appropriation of funds to reimburse the Franchise Tax Board for administrative costs, would allow a credit against the taxes imposed under that law to a qualified taxpayer, as defined to mean a taxpayer that increases its workforce by 20 annual full-time equivalent qualified employees, as compared to the taxpayer's base year, in an amount equal to 17.5% of qualified wages paid or incurred during the taxable year to a qualified employee, not to exceed $5,000,000 per qualified taxpayer per taxable year. The bill would limit the credit to the first 5 consecutive, taxable years after a qualified taxpayer first qualifies to receive the credit, subject to specified requirements. The bill would limit the aggregate amount of credits to be allocated in each calendar year to up to $50,000,000 plus the unused allocation credit amount, if any, for the preceding calendar year. The bill would require the Franchise Tax Board to allocate and certify credits to taxpayers on a first-come-first-served basis. The bill also would include that additional information required for any bill authorizing a new income tax credit. This bill would take effect immediately as a tax levy.


In committee May 25, 2018 0 co-sponsors
Co-sponsor AB 1765
In committee · California Assembly · Co-sponsor
Personal income taxes: credits: qualified disaster area.

Existing law, the Personal Income Tax law, allows various credits against the taxes imposed by that law. This bill would allow a credit against that tax for each taxable year beginning on or after January 1, 2019, and before January 1, 2020, in an amount equal to 50% of the amount paid or incurred, not to exceed $1,000, for losses sustained by a taxpayer and not compensated for by insurance or otherwise that occurred in a qualified disaster area, as defined. This bill would take effect immediately as a tax levy.
In committee May 25, 2018 1 co-sponsor
Showing 951 to 960 of 1,211 bills
Previous 1 … 95 96 97 … 122 Next