

Passed Mar 14, 2024
1 co-sponsor
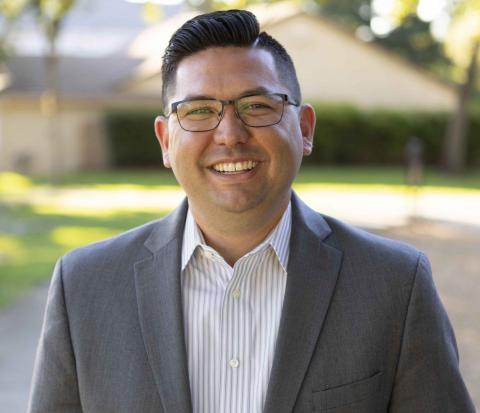
Asm. Joshua Hoover
Total votes
11,020
all sessions
Attendance
88%
954 missed
Lower than 85% of chamber peers
With party
98%
of cast votes
Near the chamber average
Bipartisan score
2%
crosses aisle rarely
Near the chamber average
Sponsored
849
bills & resolutions
Higher than 82% of chamber peers
Committees
11
assignments
849 bills and resolutions
Sponsored bills
Total
849
Primary
93
Co-sponsor
756
This page
849
matching current filters
Passed Mar 14, 2024
1 co-sponsor
Relative to Reverend Dr. Martin Luther King, Jr.
This measure would honor the late civil rights pioneer Reverend Dr. Martin Luther King, Jr. and commemorate Dr. Martin Luther King, Jr. Day.
Signed into law Mar 12, 2024
1 co-sponsor
Motor Vehicle Fuel Tax Law: adjustment suspension.
(1) The Motor Vehicle Fuel Tax Law, administered by the California Department of Tax and Fee Administration, imposes a tax upon each gallon of motor vehicle fuel removed from a refinery or terminal rack in this state, entered into this state, or sold in this state, at a specified rate per gallon. Existing law requires the department to adjust the tax on July 1 each year by a percentage amount equal to the increase in the California Consumer Price Index, as calculated by the Department of Finance. Article XIX of the California Constitution restricts the expenditure of revenues from the Motor Vehicle Fuel Tax Law, Diesel Fuel Tax Law, and other taxes imposed by the state on fuels used in motor vehicles upon public streets and highways to street and highway and certain mass transit purposes. This bill would authorize the Governor to suspend an adjustment to the motor vehicle fuel tax, as described above, scheduled on or after July 1, 2025, upon making a determination that increasing the rate would impose an undue burden on low-income and middle-class families. The bill would require the Governor to notify the Legislature of an intent to suspend the rate adjustment on or before January 10 of that year, and would require the Department of Finance to submit to the Legislature a proposal by January 10 that would maintain the same level of funding for transportation purposes as would have been generated had the scheduled adjustment not been suspended. (2) The California Constitution provides for the establishment of the State Board of Equalization, which, before July 1, 2017, had primary responsibility for most of the state's duties, powers, and responsibilities regarding the administration of taxes and fees. Existing law, on July 1, 2017, transferred to the California Department of Tax and Fee Administration various duties, powers, and responsibilities of the State Board of Equalization, including administration of the Motor Vehicle Fuel Tax Law and the Diesel Fuel Tax Law, as specified. This bill would also change references in these provisions of law from the "State Board of Equalization" to the "California Department of Tax and Fee Administration" or "department," as applicable, to reflect the transfer of the board's duties, powers, and responsibilities to the department. (3) This bill would take effect immediately as a tax levy.
In committee Mar 11, 2024
1 co-sponsor
Hazardous materials: Green Ribbon Science Panel: meetings.
Existing law establishes the Green Ribbon Science Panel and authorizes the panel to, among other things, assist the Department of Toxic Substances Control in developing green chemistry and chemical policy recommendations and implementation strategies and details. Existing law requires the department to provide for staff and administrative support to the panel. Existing law requires the panel to meet at least twice each year. This bill would increase the number of times the panel is required to meet to at least 3 times each year.
In committee Mar 11, 2024
0 co-sponsors
Passed Mar 11, 2024
1 co-sponsor
Passed Mar 7, 2024
1 co-sponsor
Worker classification: employees and independent contractors.
Existing law, as established in the case of Dynamex Operations W. v. Superior Court (2018) 4 Cal.5th 903 (Dynamex) , creates a presumption that a worker who performs services for a hirer is an employee for purposes of claims for wages and benefits arising under wage orders issued by the Industrial Welfare Commission. Existing law requires a 3-part test, commonly known as the "ABC" test, to determine if workers are employees or independent contractors for those purposes. Existing law establishes that, for purposes of the Labor Code, the Unemployment Insurance Code, and the wage orders of the Industrial Welfare Commission, a person providing labor or services for remuneration is considered an employee rather than an independent contractor unless the hiring entity demonstrates that the person is free from the control and direction of the hiring entity in connection with the performance of the work, the person performs work that is outside the usual course of the hiring entity's business, and the person is customarily engaged in an independently established trade, occupation, or business. This test is known as the "ABC" test, as described above. Existing law charges the Labor Commissioner with the enforcement of labor laws, including worker classification. Existing law exempts specified occupations and business relationships from the application of the ABC test described above. Existing law, instead, provides that these exempt relationships are governed by the multifactor test previously adopted in the case of S. G. Borello & Sons, Inc. v. Department of Industrial Relations (1989) 48 Cal.3d. This bill would repeal the above-described provisions that codify the ABC test. The bill would declare that its purpose is to suspend and nullify the California Supreme Court's decision in Dynamex and provide that this decision does not apply for purposes of California law.
In committee Mar 6, 2024
1 co-sponsor
Governor's Office of Business and Economic Development: International trade and investment.
Existing law requires the Governor's Office of Business and Economic Development (GO-Biz) to develop and implement an International Trade and Investment Program and authorizes the director of GO-Biz to establish international trade and investment offices, as specified. Existing law authorizes GO-Biz to accept nonstate moneys for the purposes of operating an international trade and investment office, as specified. Existing law requires GO-Biz to post a report on its internet website for each donation that it receives to fund an international trade and investment office that is funded in whole or in part by nonstate funds, as specified, or operated under a contract with a nonprofit entity, as specified, and for each donation that it receives for the purposes of promoting international trade and investment events, as specified, within 30 days of receiving those donations. This bill would instead require GO-Biz to post the above-described reports on its internet website from within 15 days of GO-Biz receiving those donations. Existing law authorizes GO-Biz to contract with a nonprofit entity to operate an international trade and investment office. Existing law requires a contract for that purpose to, among other things, require the nonprofit entity to provide GO-Biz with specified information sufficient to satisfy the internet website posting requirement described above within 30 days of the receipt by the nonprofit of each donation used to fund an international trade and investment office. This bill would instead require the contract to require the nonprofit entity to provide GO-Biz with the specified information sufficient to satisfy the internet posting requirement within 15 days of the nonprofit receiving those donations.
In committee Mar 4, 2024
0 co-sponsors
Relative to disc golf.
This measure would recognize the month of August 2023 as Disc Golf Month, and August 5, 2023, as California Disc Golf Day.
Signed into law Mar 4, 2024
1 co-sponsor
Ask Maddy
·
AI policy assistant
Ask Maddy about Joshua Hoover
Scope: california
Hi! I can help you understand Joshua Hoover's legislative record. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline