Issue · Budget & Taxes

Budget & Taxes (Income Tax)

Every budget & taxes bill, vote, and legislator stance in California, automatically classified by Maddy, our AI policy reader.

Total bills
62
2025-2026 Regular Session
Top supporter
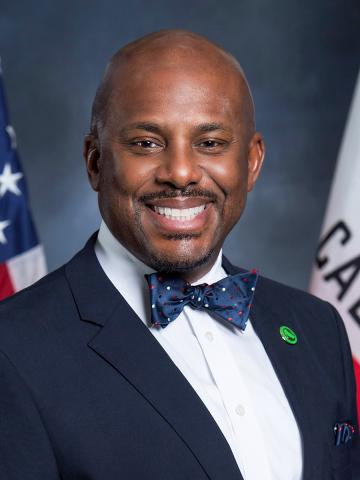
Mike Gipson
100% support rate
Top opponent
Carl DeMaio
0% support rate
Ranked legislators
10
5 support · 5 oppose
Key legislators

Who's moving income tax in California

Legislators moving income tax in California
Legislator Party Stance Support rate Decisive votes
Mike Gipson
Mike Gipson House · District 65
D
Strong +
100% 15
Sharon Quirk-Silva
Sharon Quirk-Silva House · District 67
D
Strong +
100% 15
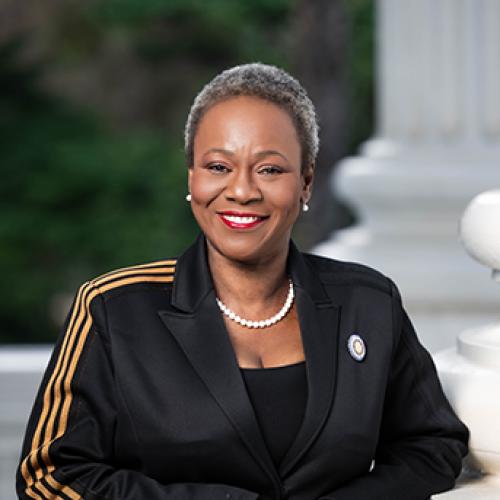
Tina McKinnor
Tina McKinnor House · District 61
D
Strong +
100% 15
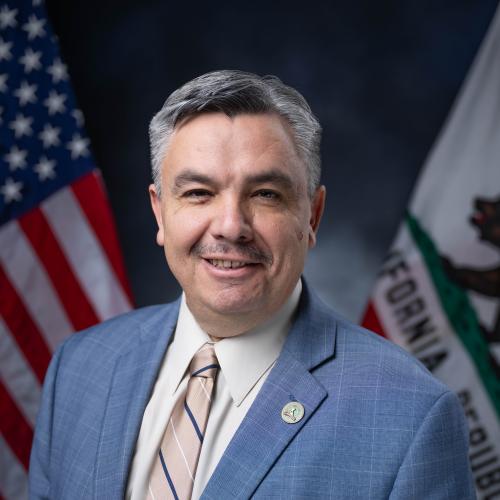
Juan Carrillo
Juan Carrillo House · District 39
D
Strong +
100% 11
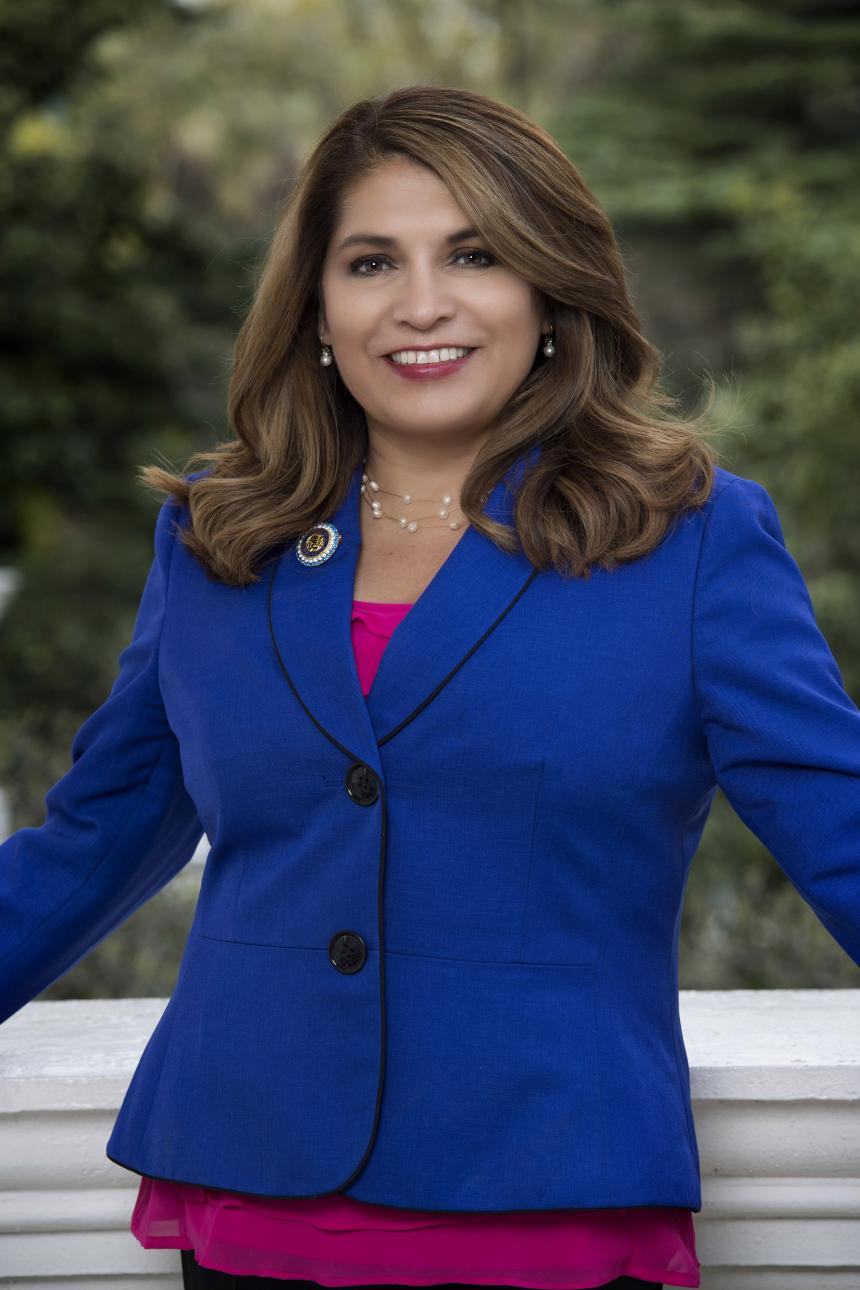
Michelle Rodriguez
Michelle Rodriguez House · District 53
D
Strong +
100% 9
Carl DeMaio
Carl DeMaio House · District 75
R
Strong −
0% 15
David Tangipa
David Tangipa House · District 8
R
Strong −
0% 7
Joshua Hoover
Joshua Hoover House · District 7
R
Strong −
0% 7
Kelly Seyarto
Kelly Seyarto Senate · District 32
R
Strong −
0% 7
Megan Dahle
Megan Dahle Senate · District 1
R
Strong −
0% 7
Showing 51–60 of 62 bills

All budget & taxes bills

failed · California · Assembly Feb 2, 2026

AB 490: Personal Income Tax Law: deduction from gross income: car loan interest payments.

The Personal Income Tax Law, in modified conformity with federal income tax laws, allows various deductions from gross income in calculating adjusted gross income. This bill, for taxable years beginning on or after January 1, 2026, and before January 1, 2031, would allow a deduction from adjusted gross income for an amount equal to the interest paid on a qualified motor vehicle loan, as defined. The bill would limit this deduction to one qualified motor vehicle loan per taxpayer. Existing law requires any bill authorizing a new tax expenditure to contain, among other things, specific goals that the tax expenditure will achieve, detailed performance indicators, and data collection requirements. This bill also would include additional information required for any bill authorizing a new tax expenditure. This bill would take effect immediately as a tax levy.
failed · California · Assembly Feb 2, 2026

AB 834: Personal Income Tax Law: deduction: teachers.

The Personal Income Tax Law, in general conformity with federal tax law, allows various deductions from gross income in calculating adjusted gross income. The Personal Income Tax Law generally applies the federal definition of adjusted gross income, but excepts the deduction allowed for certain expenses of elementary and secondary school teachers. This bill would conform with federal law for purposes of the deduction allowed for certain expenses of elementary and secondary school teachers for taxable years beginning on or after January 1, 2026, and before January 1, 2031. Existing law requires any bill authorizing a new tax expenditure, as defined, to include tax credits, deductions, exclusions, or exemptions, to contain, among other things, specific goals, purposes, and objectives that the tax credit will achieve, detailed performance indicators, and data collection requirements. This bill would include findings and collection requirements in compliance with this requirement. This bill would take effect immediately as a tax levy.
failed · California · Assembly Feb 2, 2026

AB 1282: Personal Income Tax Law: credits: medical expenses.

The Personal Income Tax Law in modified conformity with federal income tax laws, generally allows various deductions in computing the income that is subject to tax imposed under that law. This bill would, for taxable years beginning on or after January 1, 2025, and before January 1, 2030, allow a deduction in computing income for out-of-pocket medical costs, as defined. The bill would limit the deduction to $5,000 per taxable year. Existing law requires any bill authorizing a new tax expenditure to contain, among other things, specific goals, purposes, and objectives that the tax expenditure will achieve, detailed performance indicators, and data collection requirements. This bill would include additional information required for any bill authorizing a new tax expenditure. This bill would take effect immediately as a tax levy.
failed · California · Assembly Feb 2, 2026

AB 389: Personal Income Tax: tax credits: fire-resistant home improvements.

The Personal Income Tax Law allows various credits against the taxes imposed by that law. This bill would allow a credit against those taxes for each taxable year beginning on or after January 1, 2025, and before January 1, 2030, to a qualified taxpayer, as defined, in an amount equal to 40% of the taxpayer's qualified expenses, as defined, not to exceed $400 per taxable year, or $2,000 cumulatively. Existing law requires any bill authorizing a new tax credit to contain, among other things, specific goals, purposes, and objectives that the tax credit will achieve, detailed performance indicators, and data collection requirements. The bill would also include additional information required for any bill authorizing a new tax expenditure. This bill would take effect immediately as a tax levy.
failed · California · Senate Feb 2, 2026

SB 17: Personal income taxes: deductions: tips.

The Personal Income Tax Law, in modified conformity with federal income tax laws, allows various deductions from gross income in calculating adjusted gross income. This bill, for taxable years beginning on or after January 1, 2026, and before January 1, 2036, would allow a deduction in determining adjusted gross income for an amount equal to the qualified tips, as defined, received by a qualified taxpayer, as defined, during the taxable year, not to exceed $20,000. Existing law requires any bill authorizing a new tax expenditure to contain, among other things, specific goals that the tax expenditure will achieve, detailed performance indicators, and data collection requirements. This bill also would include additional information required for any bill authorizing a new tax expenditure. This bill would take effect immediately as a tax levy.
failed · California · Senate Feb 2, 2026

SB 267: Personal income tax: credit: qualified teacher: school supplies.

The Personal Income Tax Law allows various credits against the taxes imposed by that law. This bill would allow a credit against those taxes for taxable years beginning on or after January 1, 2026, and before January 1, 2031, in an amount equal to the unreimbursed amount paid or incurred by a qualified teacher during the taxable year for instructional materials and classroom supplies, as defined, not to exceed $250. The bill would define qualified teacher as a teacher in a public, charter, or private school offering instruction in kindergarten or any of grades 1 to 12, inclusive, for at least 900 hours during a school year. Existing law requires any bill authorizing a new tax expenditure to contain, among other things, specific goals that the tax expenditure will achieve, detailed performance indicators, and data collection requirements. This bill also would include additional information required for any bill authorizing a new tax expenditure. This bill would take effect immediately as a tax levy.
failed · California · Senate Feb 2, 2026

SB 666: Personal income tax: credit: home security surveillance.

The Personal Income Tax Law allows various credits against the taxes imposed by that law. This bill would allow a credit against those taxes for each taxable year beginning on or after January 1, 2026, and before January 1, 2031, in an amount equal to the amount paid or incurred, not to exceed $250, during the taxable year for the purchase and installation of a security surveillance system at the taxpayer's principal dwelling or housing unit located in the state. Existing law requires any bill authorizing a new tax expenditure, as defined, to include tax credits, to contain, among other things, specific goals, purposes, and objectives that the tax credit will achieve, detailed performance indicators, and data collection requirements. This bill would include findings and reporting requirements in compliance with this requirement. This bill would take effect immediately as a tax levy.
failed · California · Senate Feb 2, 2026

SB 269: Personal income taxes: Fire Safe Home Tax Credits Act.

The Personal Income Tax Law allows various credits against the tax imposed by that law. Existing law requires any bill authorizing a new tax credit to contain, among other things, specific goals, purposes, and objectives that the tax credit will achieve, detailed performance indicators, and data collection requirements. This bill would allow credits against the tax imposed by the Personal Income Tax Law for each taxable year beginning on or after January 1, 2026, and before January 1, 2031, to a qualified taxpayer for qualified costs relating to qualified home hardening, as defined, and for qualified costs relating to qualified vegetation management, as defined, in specified amounts, not to exceed an aggregate amount of $50,000,000 per taxable year. This bill would require a qualified taxpayer to reserve a credit for qualified costs relating to qualified home hardening or qualified vegetation management to be eligible for the above-described credits and provide all necessary information for this purpose, as specified. This bill also would include additional information required for any bill authorizing a new income tax credit and would require the Legislative Analyst's Office to prepare a written report regarding the credits, as provided. This bill would take effect immediately as a tax levy.
Sub-Topics Income Tax Tax Credits
failed · California · Senate Feb 2, 2026

SB 1: Personal income taxes: exclusion: Military Services Retirement and Surviving Spouse Benefit Payment Act.

The Personal Income Tax Law, in conformity with federal income tax laws, defines "gross income" as income from whatever source derived, except as specifically excluded, and provides various exclusions from gross income, including an exclusion for combat-related special compensation. This bill, for taxable years beginning on or after January 1, 2025, and before January 1, 2035, would exclude from gross income retirement pay received by a qualified taxpayer, as defined, during the taxable year, not to exceed $20,000, from the federal government for service performed in the uniformed services, as defined. The bill, for taxable years beginning on or after January 1, 2025, and before January 1, 2035, would also exclude from gross income annuity payments received by a qualified taxpayer, as defined, during the taxable year, not to exceed $20,000, pursuant to a United States Department of Defense Survivor Benefit Plan. The bill would make related findings and declarations. Existing law requires any bill authorizing a new tax expenditure to contain, among other things, specific goals, purposes, and objectives that the tax expenditure will achieve, detailed performance indicators, and data collection requirements. This bill also would include additional information required for any bill authorizing a new tax expenditure. This bill would take effect immediately as a tax levy.
passed · California · Senate Jun 30, 2026

SB 353: Income tax: credits: food banks.

The Personal Income Tax Law and the Corporation Tax Law allow various credits against the taxes imposed by those laws, including, for taxable years beginning on or after January 1, 2017, and before January 1, 2027, a credit for qualified taxpayers in an amount equal to 15% of the qualified value of fresh fruits or vegetables and specified raw agricultural products or processed foods donated to a food bank. This bill would extend the authorization for those tax credits for taxable years beginning before January 1, 2032. Existing law requires any bill authorizing a new tax expenditure to contain, among other things, specific goals that the tax expenditure will achieve, detailed performance indicators, and data collection requirements. For purposes of complying with these requirements, existing law requires the Franchise Tax Board to submit a report to the Legislature regarding the utilization of the credit on or before December 1 of each year until January 1, 2026. This bill would extend that reporting requirement to December 1, 2035. This bill would take effect immediately as a tax levy.
Showing 51 to 60 of 62 bills
Previous 1 … 5 6 7 Next