

Maddy summarySenate Bill 47 proposes changes to Arkansas's financial statutes by amending both the Uniform Commercial Code (UCC) and the Arkansas Banking Code of 1997. The bill introduces a definition for "Central Bank Digital Currency" (CBDC) within the UCC and modifies other UCC definitions related to "money" and "deposit account." A key provision clarifies that under the Arkansas Banking Code, "deposit" and "deposit account" will explicitly not include central bank digital currency or investment property. This legislation aims to update the legal framework for classifying certain digital assets and traditional bank accounts for financial institutions in Arkansas.
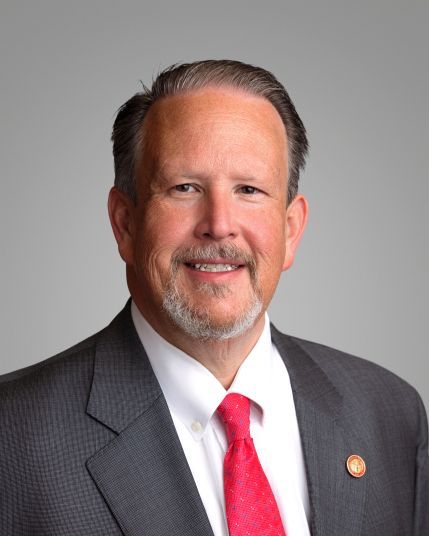
Rep. Howard Beaty
Sponsored bills
Maddy summaryHouse Bill 1534 proposes to increase the existing homestead property tax credit. This bill directly affects homeowners by reducing the amount of property taxes they owe on their primary residence. The key mechanism is an adjustment to the credit amount, providing a larger tax reduction for eligible households.
Maddy summarySB 526 proposed to prohibit the retail sale of specific disposable vapor products in Arkansas. It defined a "disposable vapor product" as one with a non-detachable battery that cannot be refilled and is designed for disposal after use. The bill would have banned retailers from selling such products if they originated from a "prohibited foreign party." The Director of Arkansas Tobacco Control could seize non-compliant products, with violations being a Class A misdemeanor, although FDA-approved products were exempt. A 90-day grace period was included for businesses to liquidate existing inventory.
Maddy summarySenate Bill 73, known as the "Access to Credit for Our Rural Economy (ACRE) Act," proposed an amendment to Arkansas's income tax laws. It aimed to provide an income tax deduction for eligible lending institutions, such as national and state banks or trust companies. This deduction would apply to the net interest income received from "qualified agricultural loans." These qualified loans are defined as those made on personal property for agricultural purposes (like equipment or livestock) or on real property substantially used for agricultural production, meeting specific lien and loan-to-value requirements. The act was intended to take effect for tax years beginning on or after January 1, 2025.
Maddy summaryBased on the provided information, Senate Bill 469 aimed to amend existing laws concerning county campaign political party committees and modify portions of Initiated Act 1 of 1996. The provided text, however, only includes an amendment to add Representative Beaty Jr. and does not detail the specific policy changes or mechanisms of the bill itself. The bill ultimately failed to pass and died on the Senate Calendar.
Maddy summarySenate Bill 204 proposes to exempt certain financial gains from state gross income for tax purposes. This exemption would apply to taxpayers whose property is acquired by a government or entity under the right of eminent domain or the threat of condemnation. Essentially, any profit a property owner makes from such a forced sale would not be considered taxable income under this bill.
Maddy summaryHouse Bill 1626, as amended, aimed to prohibit the sale of certain disposable vapor products. The bill's central provision was to ban the sale of disposable vapor products that originate from a "prohibited foreign party," a term defined by referencing an existing legal statute (§ 18-11-802). This measure would have directly impacted retailers selling vapor products and consumers who purchase them. The bill did not pass and died in committee.
Maddy summaryHJR 1014 proposes an amendment to the Arkansas Constitution. This amendment would authorize the state's General Assembly to create economic development districts. These districts would be established to promote economic development throughout Arkansas. An amendment to the resolution clarified that these districts could also be used for environmental mitigation or reclamation purposes.
Maddy summaryHouse Bill 1971 proposed to amend the process by which the Arkansas Department of Finance and Administration (DFA) provides vendor information to city and county governments. Upon request, the DFA would furnish an electronic report listing vendors within the requesting jurisdiction who hold state sales tax permits, including each vendor's name and their North American Industry Classification System (NAICS) code. To receive this report, city or county governments would need to submit an electronic request by August 1, register for an account with the Arkansas Taxpayer Access Point, and may be charged a fee to cover the DFA's costs. The bill specified that the information provided to local governments must remain confidential and cannot be disclosed.
Maddy summaryHB 1501 aimed to align Arkansas state income tax laws regarding depreciation and the expensing of property with federal income tax provisions. The bill specifically adopted various sections of the U.S. Code (Title 26 U.S.C. §§ 167, 168, and 179) related to how businesses deduct the cost of assets. This change would have increased the amount allowed for immediately expensing certain depreciable business assets on state income tax returns to match federal limits. It directly affected Arkansas businesses and individuals who purchase depreciable property and claim these deductions.