Issue · Budget & Taxes

Budget & Taxes (Audits & Accountability)

Every budget & taxes bill, vote, and legislator stance in Arizona, automatically classified by Maddy, our AI policy reader.

Total bills
14
57th Legislature - Second Regular Session
Top supporter
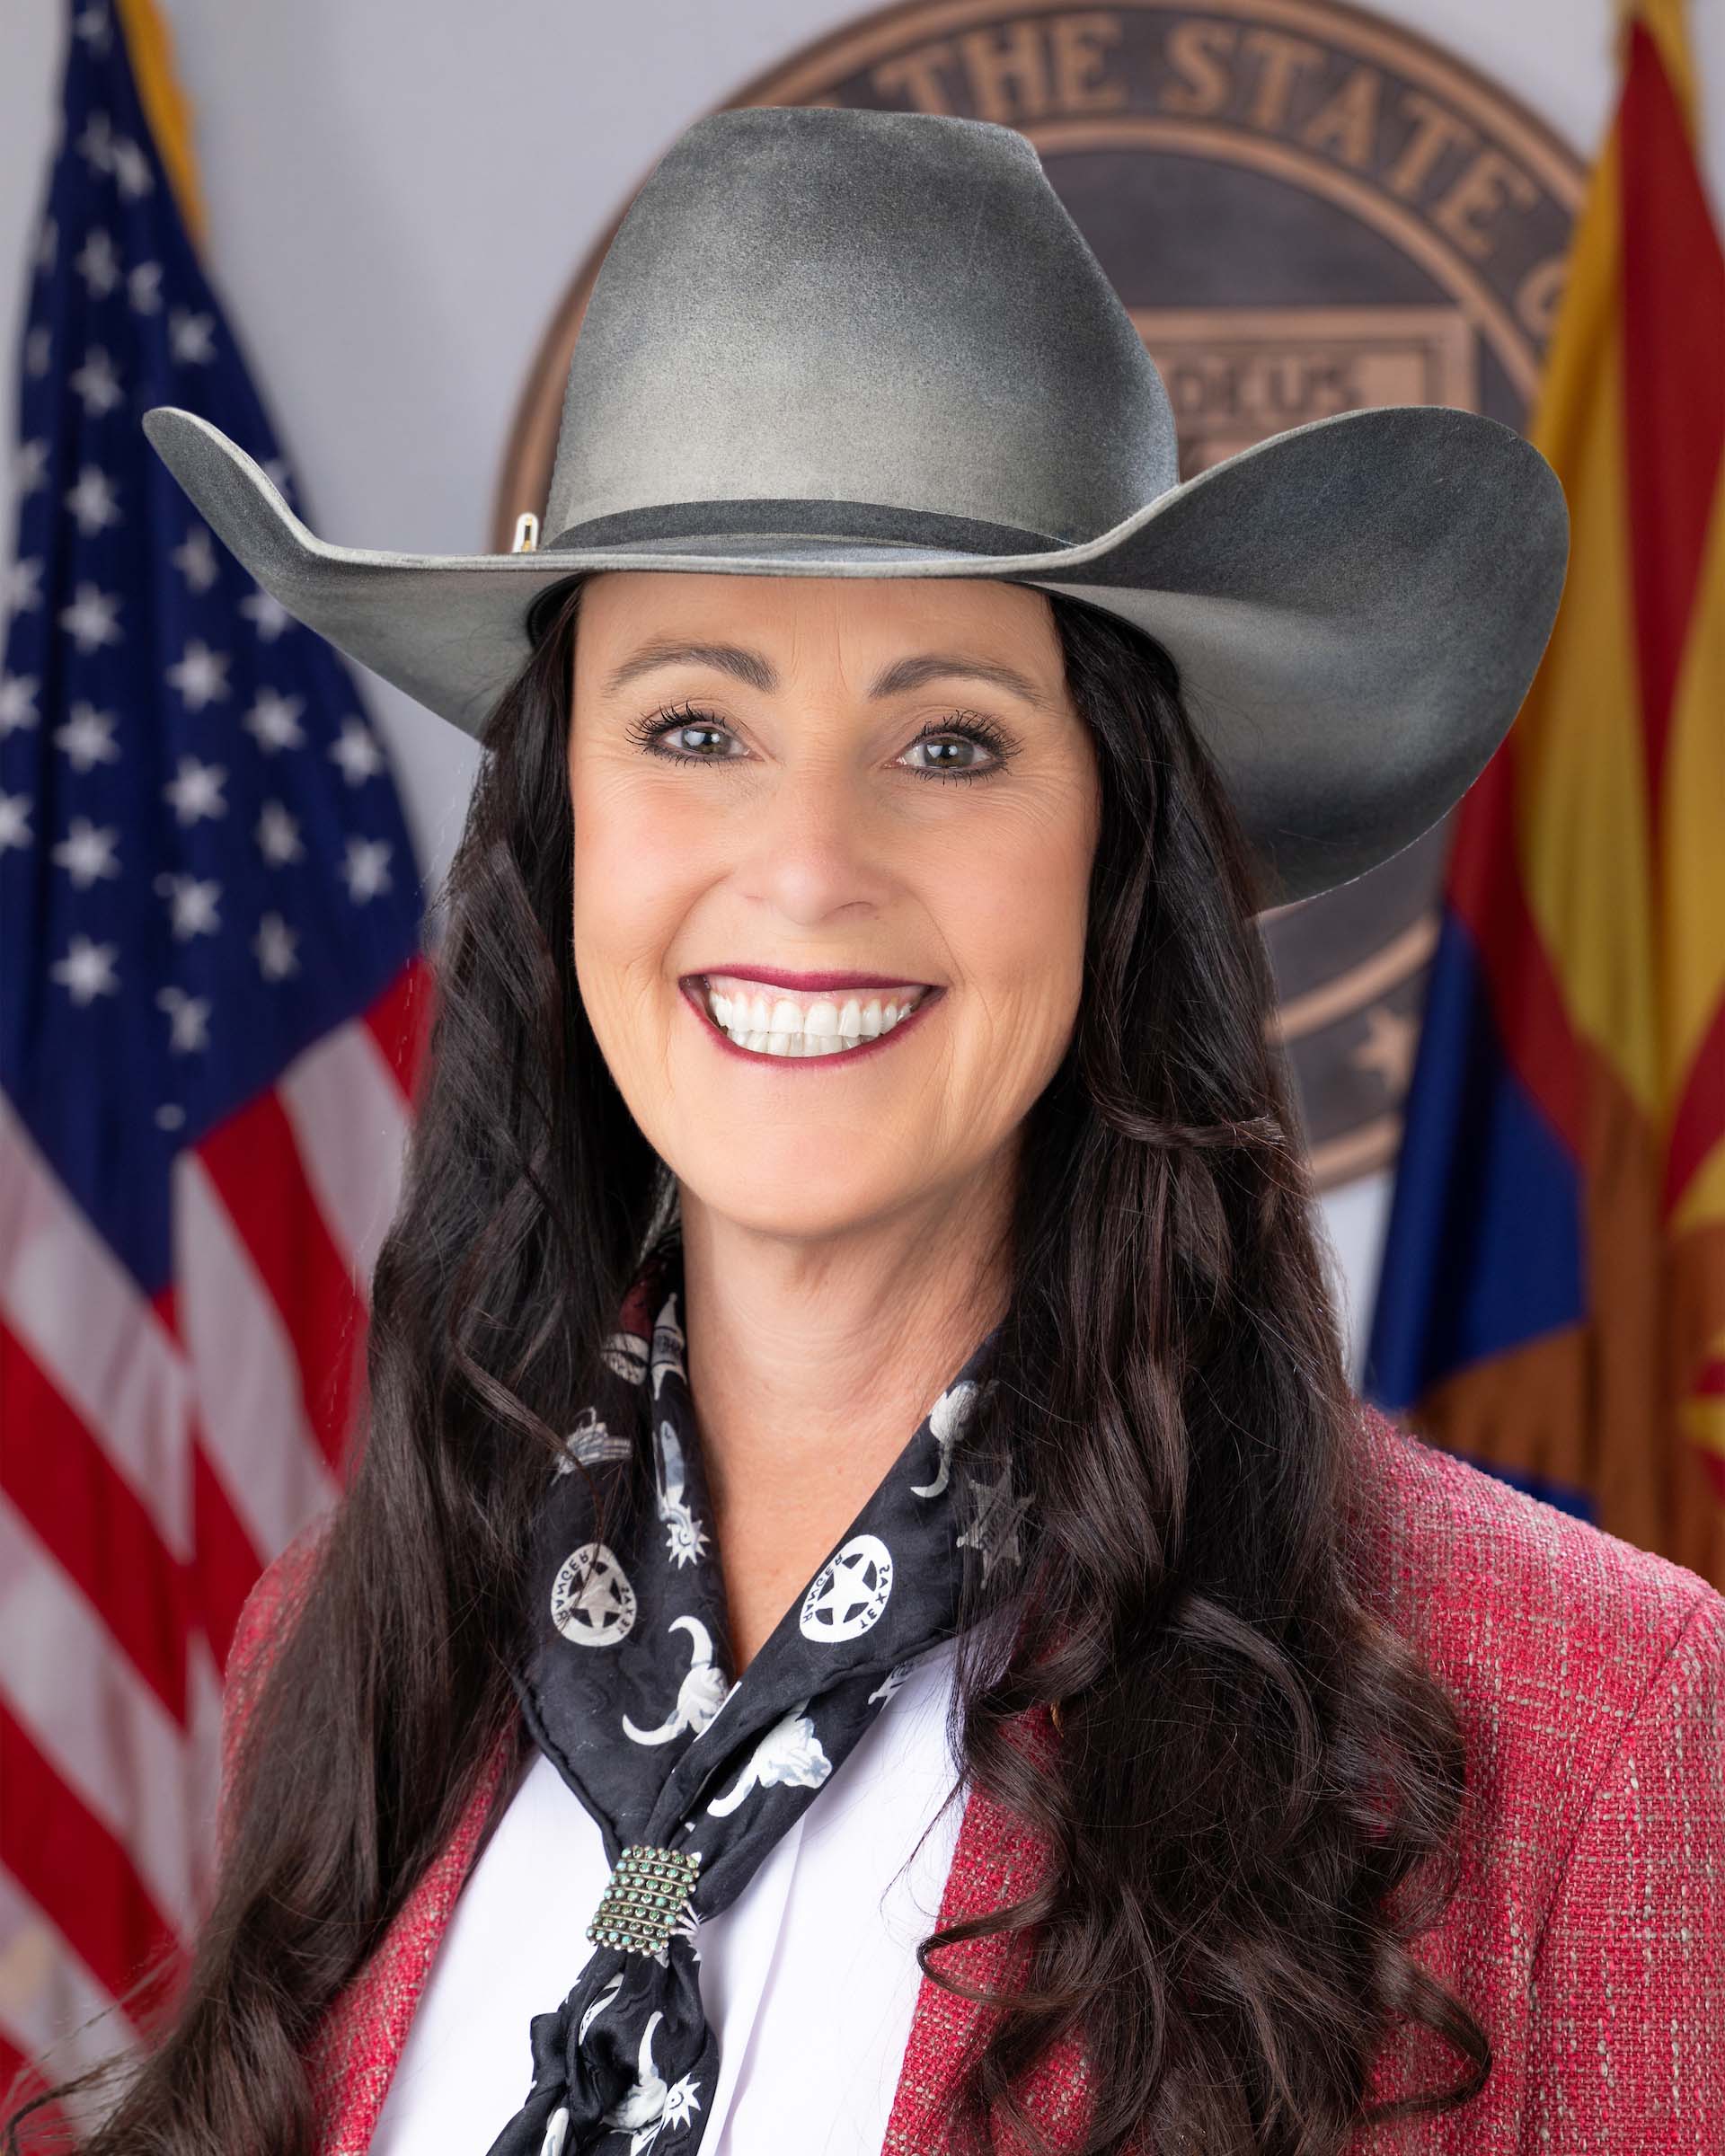
Janae Shamp
100% support rate
Top opponent
Cesar Aguilar
0% support rate
Ranked legislators
10
5 support · 5 oppose
Key legislators

Who's moving audits & accountability in Arizona

Legislators moving audits & accountability in Arizona
Legislator Party Stance Support rate Votes
Janae Shamp
Janae Shamp Senate · District 29
R
Strong +
100% 3
Alex Kolodin
Alex Kolodin House · District 3
R
Strong +
90% 10
Beverly Pingerelli
Beverly Pingerelli House · District 28
R
Strong +
90% 10
Chris Lopez
Chris Lopez House · District 16
R
Strong +
90% 10
Gail Griffin
Gail Griffin House · District 19
R
Strong +
90% 10
Cesar Aguilar
Cesar Aguilar House · District 26
D
Strong −
0% 9
Janeen Connolly
Janeen Connolly House · District 8
D
Strong −
0% 9
Anna Abeytia
Anna Abeytia House · District 24
D
Strong −
0% 8
Nancy Gutierrez
Nancy Gutierrez House · District 18
D
Strong −
0% 8
Mae Peshlakai
Mae Peshlakai House · District 6
D
Strong −
0% 4
Showing 11–14 of 14 bills

All budget & taxes bills

passed · Arizona · House Mar 10, 2026

HB 2427: land department; audit; recommendations; checklist

HB 2427 requires Arizona's state land department to implement 51 specific recommendations from an auditor general's 2025 performance audit within two years. The bill mandates monthly progress meetings with the auditor general, a public checklist tracking completion, and quarterly updates to legislative committees, the governor, and oversight chairs. If the department fails to comply within the deadline, the auditor general must notify key officials and request a special committee meeting to address the issue. The law expires December 31, 2028, and aims to ensure proper management of state trust lands and their beneficiaries.
introduced · Arizona · House Jan 21, 2026

HB 2487: corporate income tax; disclosure; database

HB 2487 requires publicly traded corporations doing business in Arizona - including those traded on foreign exchanges or owned by publicly traded entities - to file annual disclosure statements with the Arizona Commission. These statements must include specific financial data like Arizona gross income, apportionment factors, tax liabilities, and details on affiliated payments, with filings due within 30 days of Arizona tax return deadlines. Corporations not required to file Arizona tax returns may use an alternative simplified statement reporting gross receipts ranges and reasons for non-filing. The bill establishes a unique corporate identifier to track data consistently year-to-year and mandates revised filings for amended returns or audit adjustments. This applies directly to corporations meeting the ownership or trading criteria operating within Arizona.
introduced · Arizona · House Feb 19, 2026

HB 2856: early childhood education; child care

HB 2856 establishes Arizona's Department of Early Childhood Education and creates a voluntary certification program for early learning institutions (like childcare centers). The department will set academic standards for children aged 3-5 (including science basics and pre-reading skills), oversee certification, audit facilities, and manage online applications for licensing, background checks, and subsidies. Certified institutions must meet these standards and use state funds solely for education, with failure to comply risking probation or revocation. The bill also grants certified centers access to the same educational grants, tax credits, and zoning privileges available to public schools.
vetoed · Arizona · House Jun 19, 2026

HB 2015: budget procedures; late filing penalty

HB 2015 imposes financial penalties on state agencies that miss deadlines for submitting required financial reports. If agencies fail to submit final state financial statements by October 31 or federal expenditure reports by December 31, they face penalties of 1/12 of 1% of their state general fund appropriation for every 30 days late. The total penalty for any agency in a fiscal year cannot exceed $8 million or 1% of its state general fund appropriation, whichever is lower. This applies to all state organizations receiving state funds or handling federal monies that must meet financial reporting requirements.
Showing 11 to 14 of 14 bills