

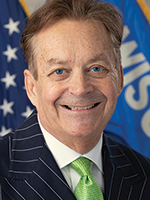
Photo of Rob Kreibich
R Wisconsin Assembly · District 28 On the 2026 ballot

Rep. Rob Kreibich

Compare
Total votes
245
all sessions
Attendance
100%
of floor votes
Near the chamber average
With party
100%
of cast votes
Near the chamber average
Bipartisan score
0%
crosses aisle rarely
Near the chamber average
Sponsored
377
bills & resolutions
Near the chamber average
Committees
5
assignments
377 bills and resolutions

Sponsored bills

Total
377
Primary
377
Co-sponsor
0
This page
377
matching current filters
Primary AB 759
Signed into law · Wisconsin Assembly · Lead sponsor
Relating to: eligibility to receive occupational credentials for recipients of deferred action under the Deferred Action for Childhood Arrivals program. (FE)

Maddy summaryAB 759 allows individuals with deferred action under the federal DACA program to obtain state occupational licenses (like nursing or cosmetology credentials) if they have valid federal work permits. It requires state licensing agencies to verify DACA recipients' federal work authorization through official systems before issuing licenses. Licenses issued under this law expire when the federal work permit expires, and recipients must renew both simultaneously. The bill explicitly states it does not grant eligibility for public benefits beyond occupational credentials.

Signed into law Apr 9, 2026 0 co-sponsors
Primary AB 194
Signed into law · Wisconsin Assembly · Lead sponsor
Relating to: modifications to housing programs under the Wisconsin Housing and Economic Development Authority. (FE)

Maddy summaryAB 194 modifies Wisconsin's housing programs under the Wisconsin Housing and Economic Development Authority. It redefines "developer" to include tribal housing authorities (Section 3) and clarifies "residential housing" to include tax-exempt reservation or trust lands (Section 4). The bill reduces maximum loan limits for housing projects from 33% to 20% of development costs (Section 10) and from 25% to 10% (Section 11). It also requires local governments to submit cost-reduction analyses showing how zoning or fee changes lowered housing costs (Section 7), directly affecting developers, tribal entities, and local governments administering housing programs.

Signed into law Apr 9, 2026 0 co-sponsors
Primary AB 182
Signed into law · Wisconsin Assembly · Lead sponsor
Relating to: changes to the low-income housing tax credit. (FE)

Maddy summaryAB 182 amends state tax statutes to clarify how low-income housing tax credits are allocated to owners in multi-entity business structures. It specifies that partnerships, limited liability companies, and tax-option corporations cannot claim the credit directly; instead, partners, members, or shareholders must claim it based on their ownership share or a written agreement. A new provision (76.639(3)(b)) explicitly allows insurers who are partners/members/shareholders to claim credits based on their stake in qualifying housing projects. The bill requires entities to calculate and provide credit allocations to owners, with written agreements needed for non-proportional allocations, and holds individual claimants responsible for tax disputes.

Signed into law Apr 9, 2026 0 co-sponsors
Primary AB 454
Signed into law · Wisconsin Assembly · Lead sponsor
Relating to: a workforce home loan program. (FE)

Maddy summaryAB 454 establishes a statewide "workforce home loan" revolving loan program to help low-to-moderate income workers purchase homes. It creates a new fund that will provide loans to first-time homebuyers whose household income is at or below 100% of the local area median income, with requirements including no prior residential property ownership in the past three years and meeting specific debt-to-income and credit score standards (minimum 580 FICO score for deferred payment options). The program uses repayments from existing loans to replenish the fund, allowing it to serve more borrowers over time. This directly affects eligible workforce households in housing markets across the state who qualify under the defined income and underwriting criteria.

Signed into law Apr 9, 2026 0 co-sponsors
Primary AB 373
Signed into law · Wisconsin Assembly · Lead sponsor
Relating to: creating a refundable individual income tax credit for the parent of a stillbirth and making an appropriation. (FE)

Maddy summaryAB 373 creates a refundable $2,000 individual income tax credit for parents who experience a stillbirth in the state, as documented by a fetal death report. The credit is refundable, meaning parents who owe less in income tax than the credit amount will receive the difference as a cash payment from state funds. Eligibility requires the stillbirth to meet state reporting criteria (per §69.18), and rules specify $2,000 for joint filers per stillbirth or $1,000 each for unmarried parents or separate filers. The credit must be claimed within the standard tax filing deadline and cannot be used by nonresidents or for partial tax years.

Signed into law Apr 9, 2026 0 co-sponsors
Primary AB 374
Signed into law · Wisconsin Assembly · Lead sponsor
Relating to: compliance with the federal Electoral Count Reform Act. (FE)

Maddy summaryAB 374 updates election procedures to align with the federal Electoral Count Reform Act. It modifies deadlines for handling ballots and canvassing results, requiring municipal clerks to deliver presidential election ballots to county clerks by 9 a.m. on the Saturday after the election (instead of Monday). The bill also clarifies processes for reconciling absentee and in-person ballots to prevent double-voting and mandates public canvassing of election results by specific deadlines, including a 5 p.m. Friday deadline for presidential elections. These changes directly affect local election officials managing municipal and presidential elections.

Signed into law Apr 9, 2026 0 co-sponsors
Primary AB 375
Signed into law · Wisconsin Assembly · Lead sponsor
Relating to: modifications to the historic rehabilitation tax credit. (FE)

Maddy summaryAB 375 modifies Wisconsin's historic rehabilitation tax credit program. It extends the credit to cover rehabilitation work completed after 2025, maintaining a 20% credit on qualified rehabilitation costs (minimum $50,000) for certified historic structures and qualified rehabilitated buildings. The bill adds new certification requirements through the Wisconsin Economic Development Corporation and allows taxpayers to transfer unused credits to other entities subject to state taxes. This directly affects property owners and developers who rehabilitate historic buildings in Wisconsin, providing them with a tax incentive for such projects. The changes align Wisconsin's credit with federal rules while updating eligibility and claim procedures.

Signed into law Apr 9, 2026 0 co-sponsors
Primary AB 699
Signed into law · Wisconsin Assembly · Lead sponsor
Relating to: a long-term care insurance assessment and a long-term care insurance assessment tax credit. (FE)

Maddy summaryAB 699 creates a 20% tax credit for disability insurers who pay long-term care insurance assessments. The credit applies to the taxable year after the assessment is paid and the next four years, reducing taxes owed under Wisconsin law. It directly affects disability insurers (defined in the bill) who collect these assessments, not individual consumers. The credit cannot be claimed by partnerships or their members if the entity claims it, and unused credits are paid by the state from a dedicated fund. This bill establishes a new tax credit mechanism without changing insurance requirements for consumers.

Signed into law Apr 9, 2026 0 co-sponsors
Primary AB 700
Signed into law · Wisconsin Assembly · Lead sponsor
Relating to: an appropriation for refundable long-term care insurance assessment credits and making an appropriation. (FE)

Maddy summaryAB 700 appropriates state funds to cover refundable credits for Wisconsin taxpayers who pay long-term care insurance assessments. It directly affects residents who pay these assessments by ensuring they receive the full credit amount through a dedicated budget appropriation. The bill amends statute 20.835(2)(de) to specify the funding needed for credits under existing laws (sections 71.07(12)(d)2., 71.28(12)(d)2., 71.47(12)(d)2., and 76.633(4)). This creates a permanent funding mechanism for the credits rather than relying on annual budget adjustments.

Signed into law Apr 9, 2026 0 co-sponsors
Primary AB 992
Failed · Wisconsin Assembly · Lead sponsor
Relating to: requirements for proposed administrative rules that impose costs. (FE)

Maddy summaryAB 992 revises cost thresholds for administrative rule reviews, lowering the trigger point from $10 million to $4 million in projected costs for businesses, local governments, and individuals over two years. It prohibits agencies from splitting a single rule into multiple rules to avoid this cost analysis requirement. Agencies must halt rulemaking if costs exceed the threshold unless they modify the rule to reduce costs, then re-evaluate. This directly affects state agencies creating regulations and entities bearing compliance costs.

Failed Apr 6, 2026 0 co-sponsors
Showing 41 to 50 of 377 bills
Previous 1 … 4 5 6 … 38 Next