

Issue · Budget & Taxes
Budget & Taxes (Sales Tax)
Every budget & taxes bill, vote, and legislator stance in Washington, automatically classified by Maddy, our AI policy reader.
Total bills
146
2025-2026 Regular Session
Top supporter
Andrew Engell
87% support rate
Top opponent
Zach Hall
11% support rate
Ranked legislators
10
5 support · 5 oppose
Key legislators
Who's moving sales tax in Washington
| Legislator | Party | Stance | Support rate | Votes |
|---|---|---|---|---|

Andrew Engell
House · District 7
|
R |
Strong +
|
87% | 79 |

Dave Stuebe
House · District 17
|
R |
Strong +
|
87% | 79 |
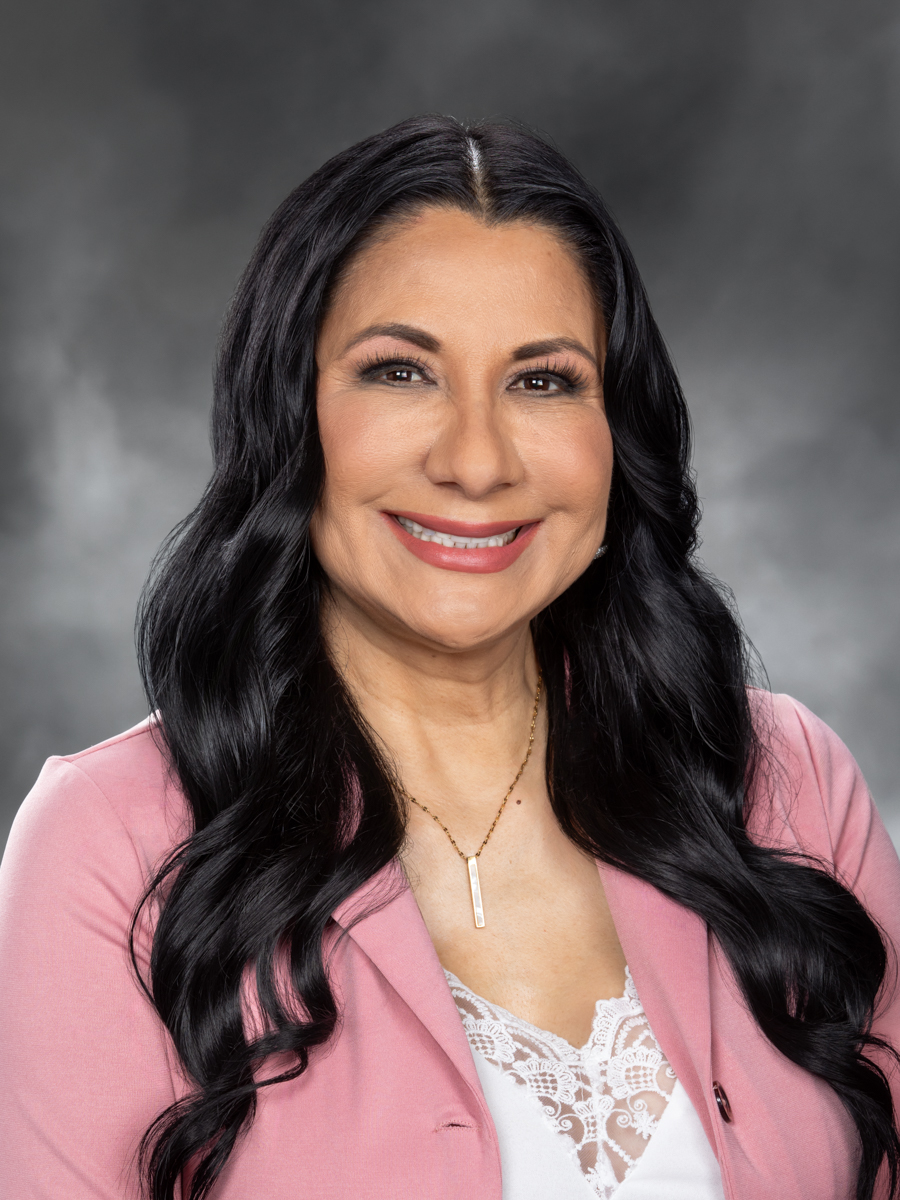
Gloria Mendoza
House · District 14
|
R |
Strong +
|
87% | 78 |
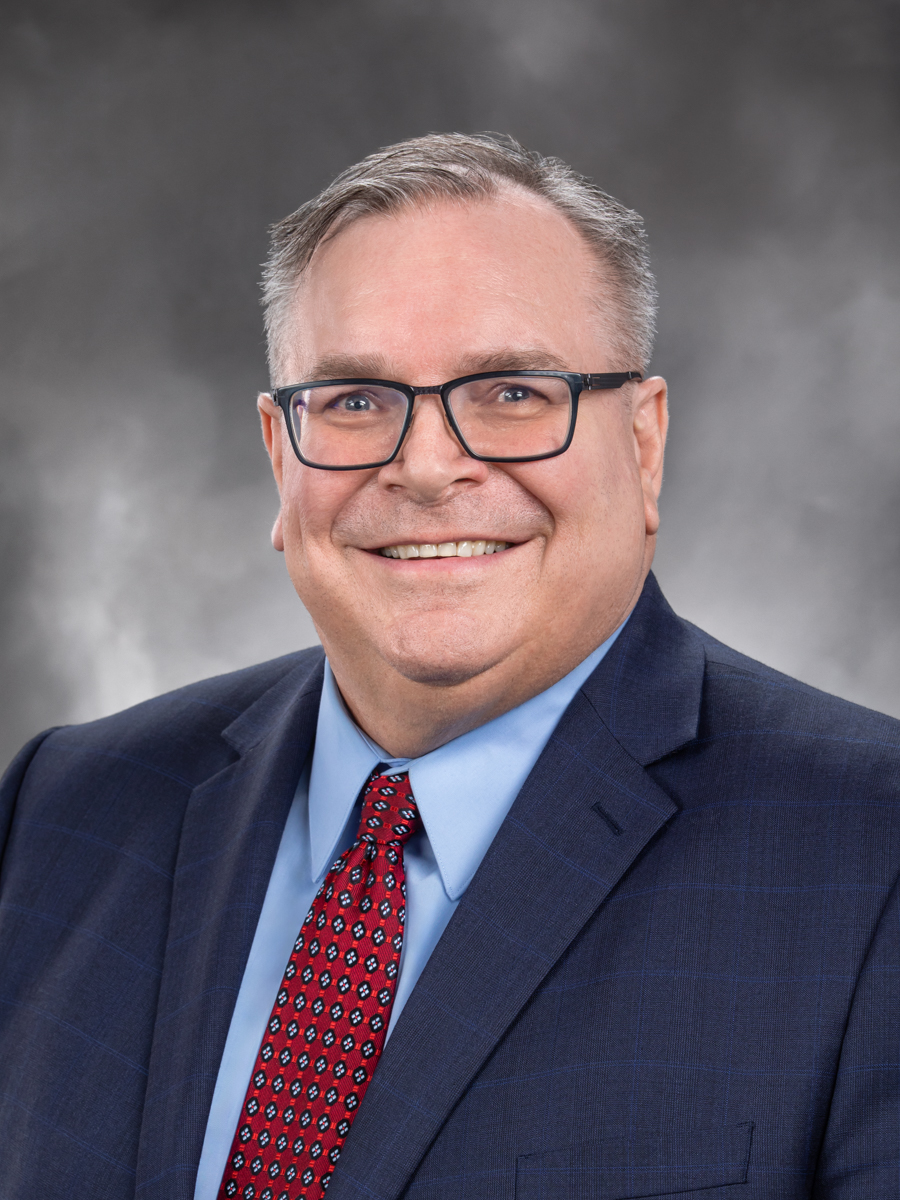
Mike Volz
House · District 6
|
R |
Strong +
|
87% | 52 |

Alex Ybarra
House · District 13
|
R |
Strong +
|
86% | 79 |

Zach Hall
House · District 5
|
D |
Strong −
|
11% | 74 |

David Hackney
House · District 11
|
D |
Strong −
|
14% | 74 |
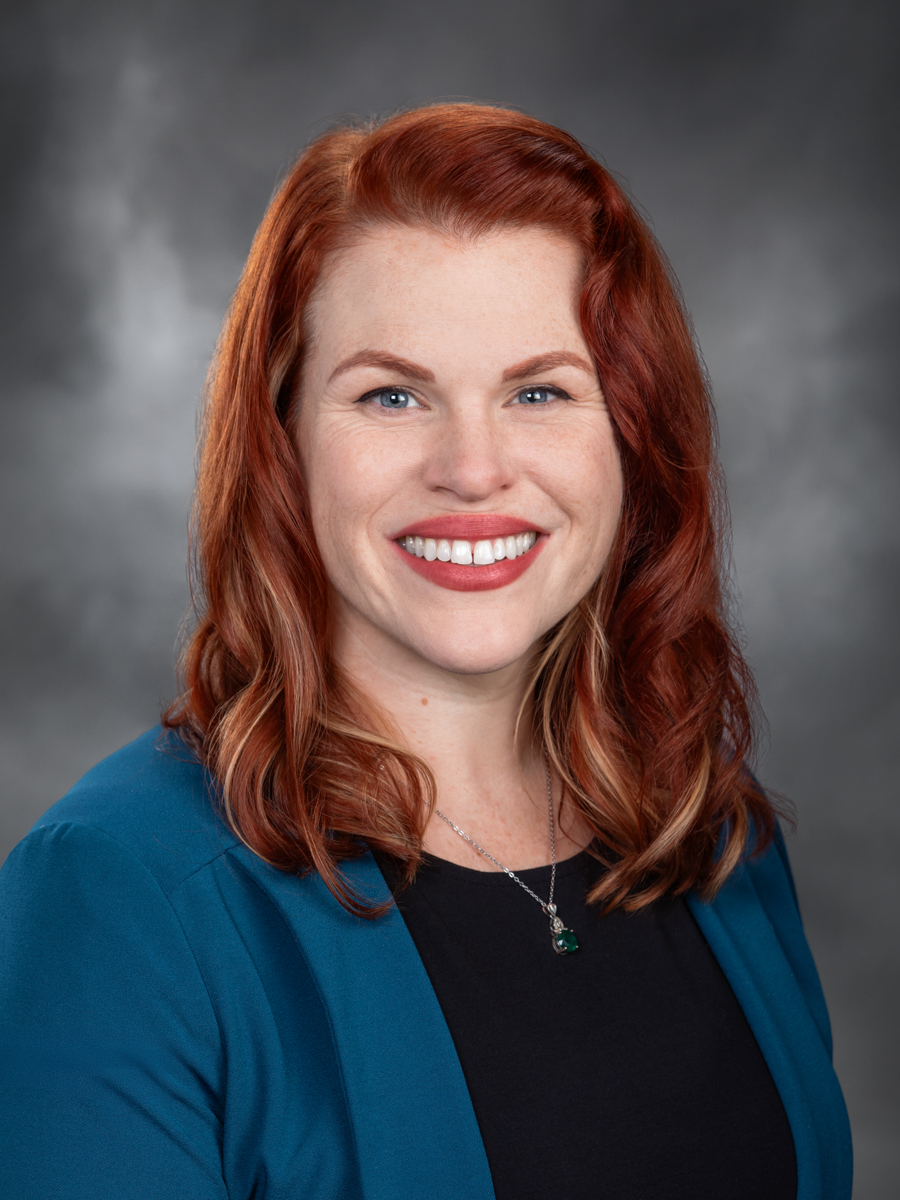
Mary Fosse
House · District 38
|
D |
Strong −
|
14% | 78 |
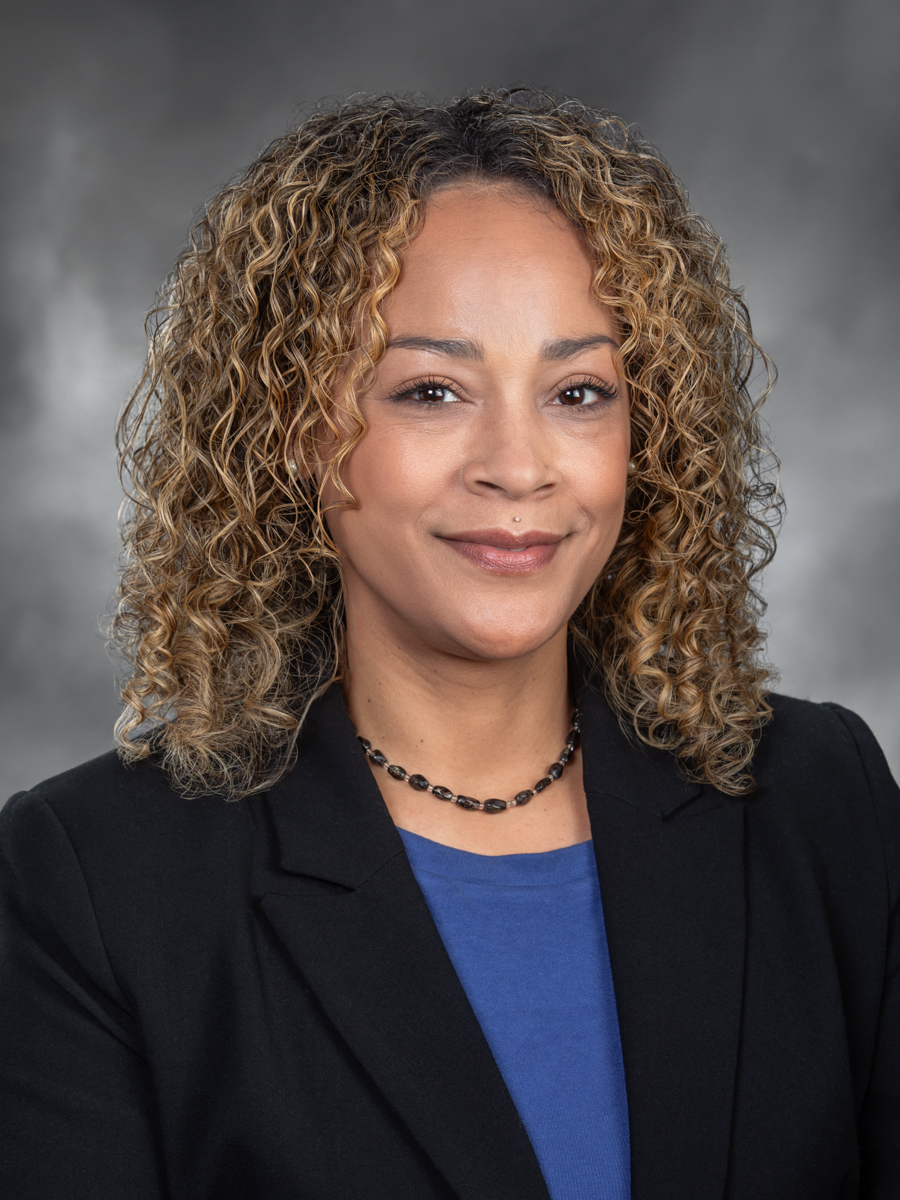
Natasha Hill
House · District 3
|
D |
Strong −
|
14% | 78 |
Timm Ormsby
House · District 3
|
D |
Strong −
|
14% | 77 |
Showing 91–100 of 146
bills
All budget & taxes bills
SB 5092: Providing a sales and use tax exemption for qualifying farm machinery and equipment.
SB 5768: Expanding eligibility for the working families' tax credit to everyone age 18 and older.
Topics
✓ Budget & TaxesSupports Budget & TaxesExpands tax credit eligibility to low-income residents 18+, providing direct tax relief to middle/lower income households without increasing taxes or reducing funding.
✓ Labor & EmploymentSupports Labor & EmploymentExpands tax credit eligibility to all low-income workers 18+, increasing financial support for labor force participation and income stability.
HB 1805: Creating a local sales and use tax to fund services for children and families that enhance well-being, promote mental health, and provide early interventions.
Topics
✓ Budget & TaxesSupports Budget & TaxesCreates a new local 0.01% sales tax to fund mental health, childcare, and family services, directly increasing public funding for essential programs within budget constraints.
✓ EducationSupports EducationFunds school-based health services (directly supporting student well-being and access to education) and addresses gaps in educational support systems through targeted funding.
✓ HealthcareSupports HealthcareFunds mental health, early interventions, school-based health services, and behavioral health programs through new local tax to address Medicaid gaps.
✓ HousingSupports HousingBill explicitly funds 'rental assistance' and 'shelter' as core services, directly supporting affordable housing and tenant stability.
HB 1924: Providing a sales and use tax exemption for manufacturing facilities and green manufacturing facilities.
Topics
✗ Budget & TaxesOpposes Budget & TaxesBill provides tax exemption for manufacturing facilities, reducing state revenue and creating business tax break, weakening budget strength per 'oppose' indicators.
✓ EnergySupports EnergyTax exemption for green-certified manufacturing facilities promotes renewable energy adoption through financial incentives for sustainable infrastructure development.
✓ EnvironmentSupports EnvironmentBill provides tax exemptions for green-certified manufacturing facilities requiring sustainability certifications, incentivizing eco-friendly practices and reducing environmental impact through targeted incentives.
HB 1109: Concerning public facilities districts.
Sub-Topics
Sales Tax
HB 2025: Increasing the working families' tax credit to reflect the economic impact of property taxes incorporated into rental amounts charged to residential tenants.
Topics
✓ Budget & TaxesSupports Budget & TaxesAdds $300 annual tax credit for low-income renters, providing direct tax relief to offset property tax costs in rent, aligning with tax relief for lower income.
✓ HousingSupports HousingProvides $300 annual tax credit to low-income renters for property tax embedded in rent, directly increasing housing affordability and tenant financial relief.
HB 1751: Establishing a sales and use tax exemption for required course materials at public institutions of higher education.
Topics
✓ Budget & TaxesSupports Budget & TaxesExempts required course materials from sales tax, providing tax relief for students at public institutions, aligning with tax relief indicators for lower-income groups.
✓ EducationSupports EducationExempts required course materials from sales tax, reducing costs for higher education students and improving access to educational resources.
HB 2069: Concerning the taxation of precious metal bullion made of gold and silver and monetized bullion, and providing that the use of bullion as tender is voluntary.
Sub-Topics
Sales Tax
SB 5553: Providing a sales and use tax incentive for multifamily affordable housing.
Topics
✓ Budget & TaxesSupports Budget & TaxesCreates sales tax deferral incentive for affordable housing development, requiring 10% low-income units, aligning with tax relief for essential housing programs.
✓ HousingSupports HousingRequires 10% affordable units for low-income households for 10 years via tax incentive, directly advancing affordable housing development.
Sub-Topics
Business Taxes
Sales Tax
Tax Incentives
Affordable Housing
Historic Preservation
Housing Finance