

Passed Nov 21, 2022
0 co-sponsors
R
Virginia House of Delegates
·
District 40
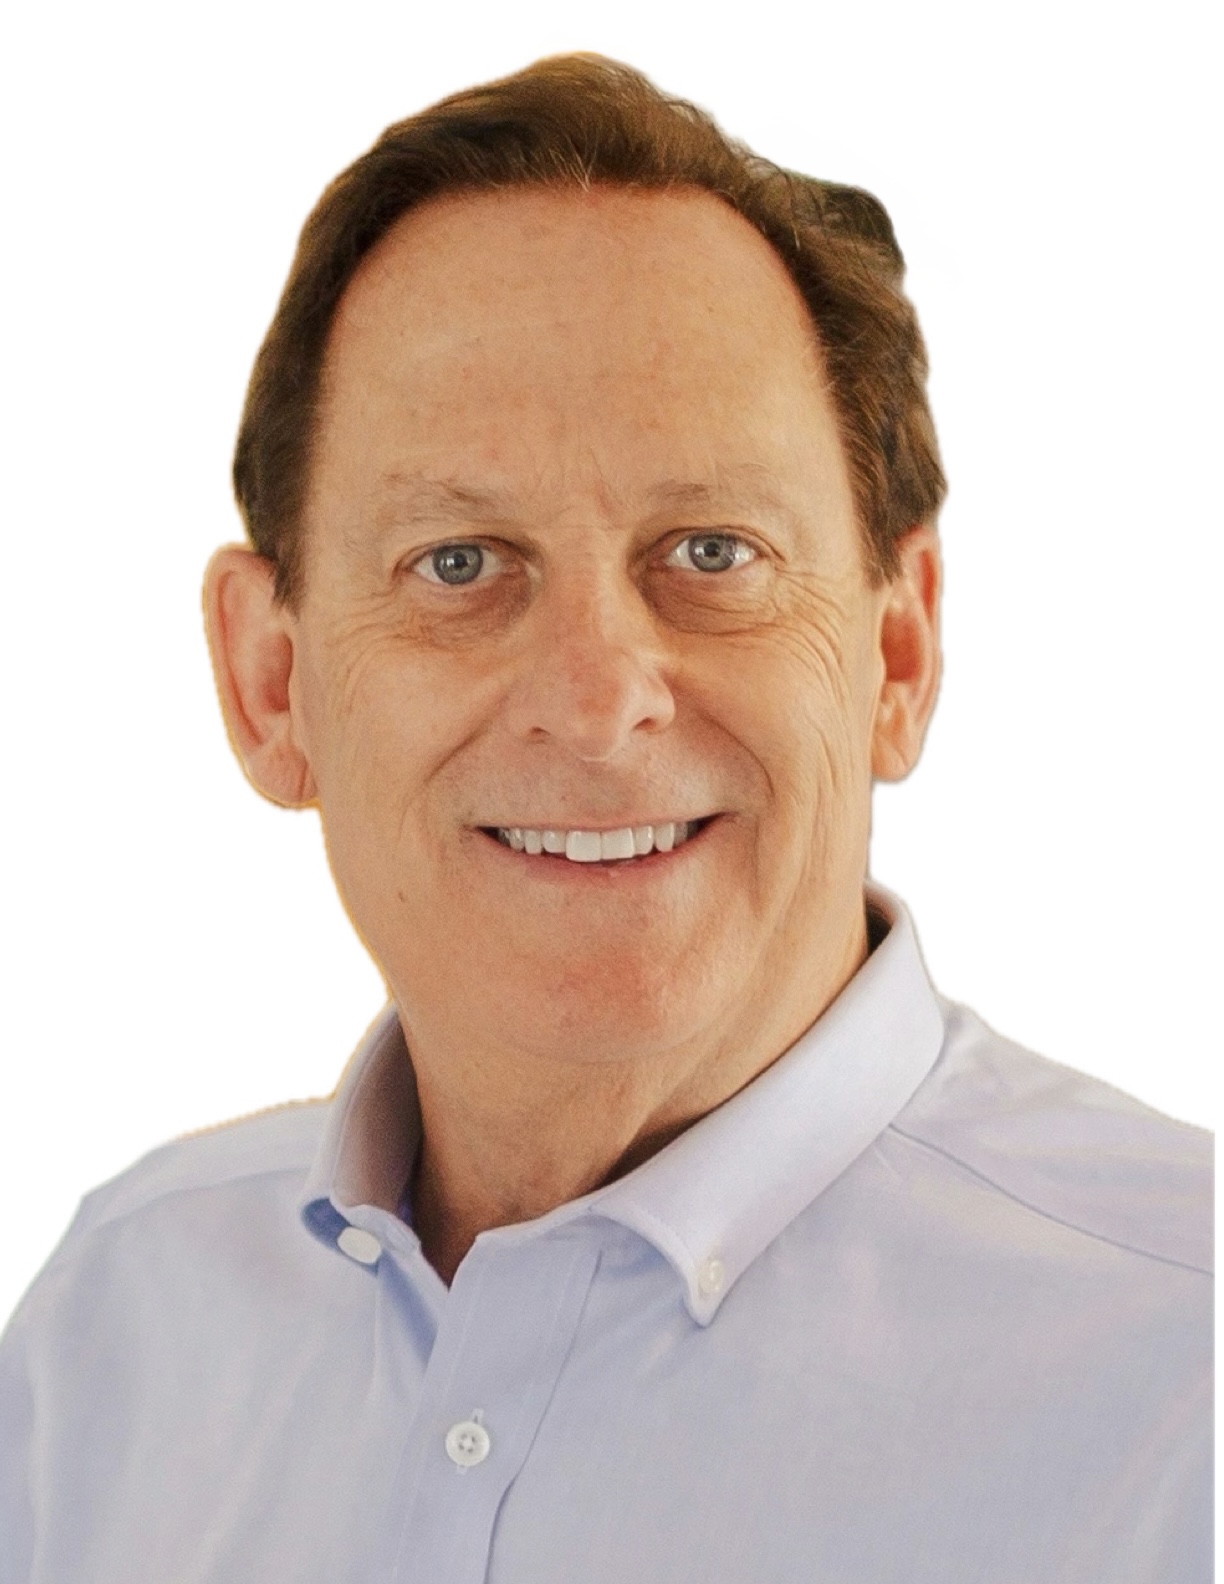
Del. Joe McNamara
Total votes
12,781
all sessions
Attendance
99%
119 missed
Lower than 84% of chamber peers
With party
94%
of cast votes
Near the chamber average
Bipartisan score
3%
crosses aisle rarely
Near the chamber average
Sponsored
399
bills & resolutions
Lower than 87% of chamber peers
Committees
3
assignments
399 bills and resolutions
Sponsored bills
Total
399
Primary
120
Co-sponsor
279
This page
399
matching current filters
Introduced Sep 7, 2022
0 co-sponsors
Signed into law Aug 4, 2022
0 co-sponsors
RS&UT; exemption for food purchased for human consumption & essential personal hygiene products.
Sales tax; exemption for food purchased for human consumption and essential personal hygiene products. Exempts food purchased for human consumption and essential personal hygiene products (the grocery tax) from all state, regional, and local sales taxes. The bill dedicates an amount equal to a 0.182 percent sales and use tax to cities and counties as a supplemental school payment. Such payment shall, from July 1, 2022, until July 1, 2024, be distributed based on each city and county's estimated average share of monthly distributions attributable to the tax on such food and hygiene products between February 2020 and December 2021. Beginning July 1, 2024, such payment shall be based upon each city and county's pro rata share of total local sales and use taxes.
Signed into law Aug 4, 2022
0 co-sponsors
School principals; incident reports, written threats against school personnel, etc.
School principals; incident reports. Requires that school principals report to law enforcement certain enumerated acts that may constitute a misdemeanor offense and report to the parents of any minor student who is the specific object of such act that the incident has been reported to law enforcement. Under current law, principals are required to make such reports only for such acts that may constitute a felony offense. The bill provides, as an exception to the requirement to report any written threats against school personnel while on a school bus, on school property, or at a school-sponsored activity, that a principal is not required but may report to the local law-enforcement agency any such incident committed by a student who has an individualized education plan. This bill is identical to SB 36.
Signed into law May 27, 2022
1 co-sponsor
Writ of vacatur; victims of sex trafficking, payment of fees or costs.
Writ of vacatur; victims of sex trafficking;payment of fees or costs. Provides that a petitioner for a writof vacatur for victims of sex trafficking shall not be required topay any fees or costs for filing such petition if the petitioneris found to be unable to pay them.
Signed into law Apr 11, 2022
1 co-sponsor
Income tax, state; pass-through entities, elective tax.
Income taxation; pass-through entities. Permits a qualifying pass-through entity, defined in the bill, to make an annual election in taxable years 2021 through 2025 to pay an elective income tax at a rate of 5.75 percent, created by the bill, at the entity level for the taxable period covered by the return. The bill also (i) creates a corresponding refundable income tax credit for taxable years 2021 through 2025 for any amount of income derived from a pass-through entity having Virginia taxable income if such pass-through entity makes such election and pays the elective income tax imposed at the entity level and (ii) allows an individual to claim a credit for similar taxes paid to other states for taxable years 2021 through 2025. This bill is identical to SB 692.
Signed into law Apr 11, 2022
0 co-sponsors
Local government; hiring people with disabilities.
Local government hiring; people with disabilities. Requires any locality to take into consideration or give preferenceto an individual's status as a person with a disability in its employmenthiring policies and practices, provided that such person with a disabilitymeets all of the knowledge, skills, and eligibility requirementsfor the available position.
Signed into law Apr 11, 2022
1 co-sponsor
Restaurants; on-site certified food protection managers.
Prepared foods; certified food protection managers. Provides that regulations adopted by the State Board of Health shall not require an establishment that sells only prepared food to have a certified food protection manager on site during all hours of operation.
Signed into law Apr 11, 2022
1 co-sponsor
Group health benefit plans; sponsoring associations, formation of benefits consortium, definitions.
Group health benefit plans; bona fide associations; formation of benefits consortium. Provides that certain trusts constitute a benefits consortium and are authorized to sell health benefit plans to members of a sponsoring association that (i) has been formed and maintained in good faith for purposes other than obtaining or providing health benefits; (ii) does not condition membership in the sponsoring association on any factor relating to the health status of an individual, including an employee of a member of the sponsoring association or a dependent of such an employee; (iii) makes any health benefit plan available to all members regardless of any factor relating to the health status of such members or individuals eligible for coverage through a member; (iv) does not make any health benefit plan available to any person who is not a member of the association; (v) makes available health plans or health benefit plans that meet requirements provided for in the bill; (vi) operates as a nonprofit entity under § 501(c)(5) or 501(c)(6) of the Internal Revenue Code; and (vii) has been in active existence for at least five years. The bill replaces references to "bona fide association," as used in provisions applicable to health care plans in the small employer market, with the term "sponsoring association."The bill requires any health benefit plan issued by a self-funded multiple employer welfare arrangement (MEWA) that covers one or more employees of one or more small employers to (a) provide essential health benefits and cost-sharing requirements; (b) offer a minimum level of coverage designed to provide benefits that are actuarially equivalent to 60 percent of the full actuarial value of the benefits provided under the plan; (c) not limit or exclude coverage for an individual by imposing a preexisting condition exclusion on that individual; (d) be prohibited from establishing discriminatory rules based on health status related to eligibility or premium or contribution requirements as imposed on health carriers; (e) meet the renewability standards set forth for health insurance issuers; (f) establish base rates formed on an actuarially sound, modified community rating methodology that considers the pooling of all participant claims; and (g) utilize each employer member's specific risk profile to determine premiums by actuarially adjusting above or below established base rates, and utilize either pooling or reinsurance of individual large claimants to reduce the adverse impact on any specific employer member's premiums.The bill prohibits a self-funded MEWA from issuing health benefit plans in the Commonwealth until it has obtained a license pursuant to regulations promulgated by the State Corporation Commission. The bill authorizes the Commission to adopt regulations applicable to self-funded MEWAs, including regulations addressing financial condition, solvency requirements, and the exclusion of self-funded MEWAs from the Virginia Life, Accident and Sickness Insurance Guaranty Association. This bill is identical to SB 195.
Signed into law Apr 11, 2022
1 co-sponsor
Ask Maddy
·
AI policy assistant
Ask Maddy about Joe McNamara
Scope: virginia
Hi! I can help you understand Joe McNamara's legislative record. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline