

Stop the Wait Act of 2025 This bill phases out the initial waiting period for Social Security Disability Insurance (SSDI) benefits and eliminates the waiting period for certain disabled individuals to become eligible for Medicare. Under current law, individuals generally must wait five months after the onset of disability to begin receiving SSDI benefits. The bill would gradually reduce this waiting period before eliminating it entirely in the year 2030. Further, the bill would eliminate the 24-month waiting period for certain disabled workers and other individuals to become eligible for Medicare. Under current law, individuals under the age of 65 may generally enroll in Medicare after they have been eligible for SSDI or Social Security child’s, widow’s, or widower’s benefits by reason of disability for 24 months. The bill would eliminate this waiting period for individuals for whom the annual cost of certain medical insurance would exceed a specified percentage of their household income (i.e., those who cannot afford minimum essential coverage). Medicare eligibility for these individuals must be available retroactively to the first month that an individual qualified for SSDI or Social Security child’s, widow’s, or widower’s benefits by reason of disability.
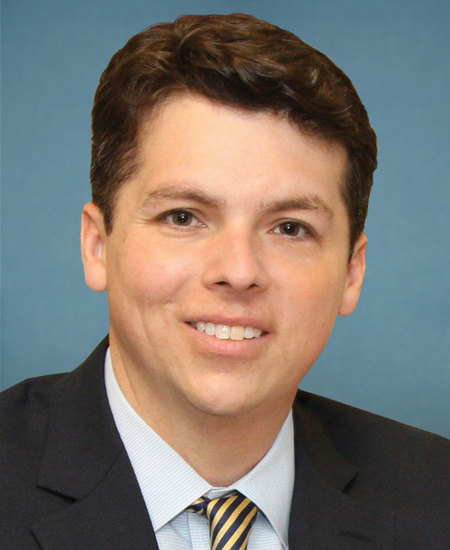
Rep. Brendan F. Boyle
Sponsored bills
National Origin-Based Antidiscrimination for Nonimmigrants Act or the NO BAN Act This bill imposes limitations on the President's authority to suspend or restrict aliens from entering the United States. It also prohibits religious discrimination in various immigration-related decisions, such as whether to issue an immigrant or nonimmigrant visa, unless there is a statutory basis for such discrimination. The President may temporarily restrict the entry of any aliens or class of aliens after the Department of State determines that the restriction would address specific and credible facts that threaten U.S. interests such as public safety. The bill also imposes limitations on such restrictions, such as requiring the President, State Department, and the Department of Homeland Security (DHS) to (1) only issue a restriction when required to address a compelling government interest, and (2) narrowly tailor the suspension to use the least restrictive means to achieve such an interest. Before imposing a restriction, the State Department and DHS shall consult with Congress. The State Department and DHS shall report to Congress about the restriction within 48 hours of the restriction's imposition. If such a report is not made, the restriction shall immediately terminate. Individuals or entities present in the United States and unlawfully harmed by such a restriction may sue in federal court. The bill transfers the authority to suspend the entry of aliens traveling to the United States on a commercial airline that failed to comply with regulations related to detecting fraudulent travel documents from the Department of Justice to DHS.
Maddy summaryHR 854, the DERAIL Act, requires the Transportation Secretary to update federal regulations defining "high-hazard flammable train" to include any train carrying flammable liquids or gases in tank cars. It also mandates that rail carriers report all toxic-by-inhalation materials on such trains to emergency responders within 24 hours after a derailment. The bill directly affects rail companies transporting hazardous materials and emergency agencies responding to train accidents. These changes aim to improve safety communication and response during incidents involving dangerous goods.
Maddy summaryHRES 88 is a symbolic House resolution designating January 31, 2025, as "Earned Income Tax Credit Awareness Day." It supports raising public awareness about the EITC - a refundable federal tax credit for low- and moderate-income workers - and calls on government agencies, nonprofits, and employers to promote access to the credit and free tax filing assistance. The resolution does not create new law or change eligibility; it solely aims to encourage more eligible workers to claim the credit they qualify for. Approximately 20% of eligible individuals currently do not claim the EITC, per the resolution’s background statements.
Maddy summaryHCONRES 4 is a symbolic resolution expressing Congress's support for tax-exempt fraternal benefit societies (like mutual aid organizations). It recognizes these groups, which have over 7 million members nationwide, as historically and currently providing critical community benefits - including life/health insurance, charitable work, and volunteer services - valued at over $3.8 billion annually. The resolution affirms that their tax-exempt status under Section 501(c)(8) of the Internal Revenue Code remains beneficial and should continue to be promoted. This is a non-binding expression of congressional sentiment, not a policy change.
Maddy summaryThis resolution expresses the House of Representatives' position that Congress should take steps to prevent the privatization of the United States Postal Service (USPS), ensuring it remains a federal independent agency. It highlights USPS’s constitutional role, self-sustaining nature (relying on service revenue, not taxpayer funds), and critical functions - serving 168 million addresses daily, supporting rural communities, and underpinning e-commerce. The resolution opposes privatization, noting it would raise prices, reduce services, and harm the $1.9 trillion mailing industry. As a non-binding resolution, it reflects the House’s stance but does not create new law or policy.
Maddy summaryHRES 74 is a symbolic House resolution supporting Catholic schools and celebrating the 51st annual National Catholic Schools Week (January 26-February 1, 2025). It recognizes Catholic schools’ contributions, citing their role in educating 1.7 million students, serving diverse communities (including 20.5% racial minorities and 15.5% Hispanic students), and maintaining a 98.9% high school graduation rate. The resolution specifically applauds the National Catholic Educational Association and U.S. Conference of Catholic Bishops for their work in promoting Catholic education and the 2025 theme, "United in Faith and Community." As a procedural resolution, it has no legal effect but formally acknowledges these schools’ academic and community impact.
Maddy summaryHR 768, the Holocaust Education and Antisemitism Lessons Act, requires the U.S. Holocaust Memorial Museum Director to study how states and school districts currently teach about the Holocaust and antisemitism in K-12 schools. The study will examine curriculum requirements, teacher training, educational materials used, and assessment methods across all states and a representative sample of school districts and schools. It specifically aims to identify gaps, resources needed, and how schools address antisemitism and genocide prevention in their teaching. The Museum must submit a report to Congress within three years of the bill's enactment, detailing findings on current practices and challenges. This bill does not mandate new teaching requirements but seeks to understand existing approaches to Holocaust education.
Maddy summaryHRES 68 is a non-binding House resolution expressing strong disapproval of the President’s announcement to withdraw the U.S. from the Paris Agreement. It commends states, businesses, and citizens supporting the Agreement, urges the President to reverse the withdrawal decision, and calls for Congress to prioritize U.S. climate leadership. The resolution does not create new laws or affect specific groups but formally states the House’s position against withdrawing from the international climate accord. It was introduced by 115 co-sponsors and reflects broad congressional concern about reversing U.S. climate commitments.
Maddy summaryThis bill creates a new above-the-line tax deduction for performing artists (like musicians, actors, and dancers) to deduct work-related expenses directly from their gross income, rather than itemizing deductions. It sets a $100,000 income threshold (adjusted annually for inflation), phasing out the deduction by 10% for every $2,000 earned above this amount. The bill also explicitly includes commissions paid to an artist’s manager or agent as deductible expenses and raises the $200 "nominal employer" threshold for expense deductions to $500 (with inflation adjustments). These changes apply to tax years beginning after December 31, 2024.