

Fix Our Flooded Basements Act of 2025 This bill expands the disaster assistance provided to individuals and households for repairs to and property in flood-damaged basements. It also expands eligibility and coverage for certain group flood insurance. Under current law, the Individual Assistance (IA) program of the Federal Emergency Management Agency (FEMA) limits home repair assistance for flood-damaged basements to damage affecting the safety, sanitation, or functionality of the home (e.g., structural damage, hazardous conditions). The bill allows home repair assistance for disaster-caused mold, mildew, and moisture damage in basements regardless of whether the damage affects safety, sanitation, or functionality. Additionally, flood-damaged basements are eligible for home repair assistance even when the basement is not required for occupying the dwelling. Also, currently, IA assistance for flood-damaged personal property in basements is limited to washers, dryers, and property essential for occupying the dwelling. The bill expands IA personal property assistance to more broadly cover property damaged by disaster-caused flooding in basements. The scope of such assistance must at least equal the coverage for such damage by a standard policy under the National Flood Insurance Program (e.g., covering air conditioning units and freezers in basements). Additionally, FEMA must expand the eligibility and coverage of the group flood insurance it provides to IA recipients, including increasing the maximum coverage and expanding coverage for basements. The bill also excludes from the maximum for IA housing assistance expenses for (1) hazard mitigation measures in flood-damaged basements, and (2) premiums for group flood insurance policies.
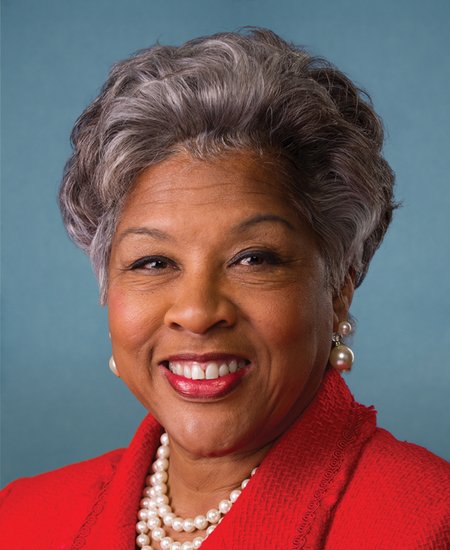
Rep. Joyce Beatty
Sponsored bills
Maddy summaryHR 4719, the Freedom to Move Act, would create $5 billion in federal grants to help cities, counties, and transit agencies make public transportation free and improve service quality. Local governments applying for these grants must demonstrate how they will redesign bus routes to prioritize low-income and minority neighborhoods, eliminate criminal penalties for fare evasion, and address transit gaps in underserved communities. The grants cover lost fare revenue and fund specific improvements like safer bus stops, dedicated bus lanes, and better service frequency. This directly affects transit agencies and riders in communities currently lacking reliable, affordable transportation options.
Resident Physician Shortage Reduction Act of 2025 This bill increases the number of residency positions eligible for graduate medical education payments under Medicare for qualifying hospitals, including hospitals in rural areas and health professional shortage areas. The bill provides for an additional increase of 2,000 positions per fiscal year from FY2026-FY2032; during this period, each hospital may receive up to 75 additional positions in total under the bill and current law. Additionally, one-third of the positions that are made available under the bill must be allocated to hospitals that are already operating above applicable resident limits. The bill also requires the Government Accountability Office to report on strategies to increase the diversity of the health professional workforce, including with respect to representation from rural, low-income, and minority communities.
Maddy summaryHR 4710, the No Surprises Act Enforcement Act, increases penalties for health insurance plans and issuers that violate balance billing protections, which prevent surprise medical bills. The bill raises fines from $100 to $10,000 per violation for specific balance billing rule violations and adds a new penalty of three times the difference between initial payment and out-of-network rates for late payments after Independent Dispute Resolution decisions. It requires health plans and nonparticipating providers to make timely payments within 30 days of a payment determination, with interest accruing on late payments. The bill also establishes new transparency reporting requirements for the Secretary to submit regular reports to Congress about audits, enforcement actions, and penalties. These provisions directly affect health insurance issuers, group health plans, and nonparticipating healthcare providers.
Maddy summaryH.J. Res. 108 proposes a constitutional amendment to remove legal immunity for federal officials, including the President, from criminal prosecution for actions taken while performing official duties. It would prohibit the President from granting pardons to themselves and eliminate the defense that "official authority" excuses violations of federal or state law (with limited exceptions for certain congressional actions). If ratified, this amendment would require Congress to pass implementing laws to enforce these changes. The proposal is currently in the House Judiciary Committee and requires approval by three-fourths of state legislatures to become part of the Constitution.
Maddy summaryHR 4606, the Ally’s Act, requires private health insurance plans (including employer-sponsored plans and individual coverage) to cover hearing implants and related services. It directly affects people with hearing loss who need cochlear implants, bone conduction devices, or external sound processors, as determined by a physician or audiologist. The bill mandates coverage for devices, maintenance, repairs, upgrades every 5 years, hearing assessments, surgery, and rehabilitation - without separate cost-sharing or stricter limits than other medical services. Insurers cannot deny coverage if a provider deems the service medically necessary. The law applies to all applicable health plans and takes effect for plan years beginning January 1, 2026.
Maddy summaryThis bill prohibits life, disability, and long-term care insurers from denying coverage, canceling policies, or increasing premiums based solely on a person's status as a living organ donor. It directly protects living organ donors by preventing insurance discrimination unrelated to actual health risks. The bill also requires the Health and Human Services Secretary to update public educational materials about organ donation benefits, risks, and insurance impacts within six months of enactment. These materials will include information on the new insurance protections established by the bill. The law relies on state insurance regulators for enforcement of the insurance provisions.
Maddy summaryThis bill amends the Family and Medical Leave Act (FMLA) and federal employee leave rules to clarify that recovery from organ donation surgery qualifies as a "serious health condition." It directly affects private-sector workers covered by the FMLA and federal civil service employees. The key change adds "including recovery from surgery related to organ donation" to the definitions of serious health conditions in both the FMLA and federal leave statutes. This ensures eligible employees can use their existing family and medical leave benefits to recover after donating an organ, without requiring new leave entitlements.
Maddy summaryHR 1450, the OFAC Licensure for Investigators Act, creates a 5-year pilot program allowing private investigation firms to obtain licenses from the Office of Foreign Assets Control (OFAC) for conducting small-scale financial transactions (nominal amounts) as part of their investigations. The program requires OFAC to establish the pilot within one year, coordinate with FinCEN, and mandate participating firms to submit detailed monthly activity reports. OFAC must also report annually to Congress on license requests, approvals, and program utility, plus provide classified briefings to relevant congressional committees on applicants, operations, and recommendations. This bill directly affects private sector investigation firms seeking to legally conduct minimal financial transactions during investigations, while imposing specific reporting and oversight requirements on OFAC.
Maddy summaryThe SUPPLY Act establishes a federal program to insure second loans (additional financing) for building accessory dwelling units (ADUs) on single-family properties. This insurance, administered by the Department of Housing and Urban Development, covers up to 30% of a standard one-unit home loan amount or 100% of the property value after construction (with potential increases based on 50% of projected rental income). Homeowners seeking to add ADUs - such as backyard cottages, converted basements, or detached units - can use this insurance to secure financing, with a government premium of up to 1% annually. The bill also requires Fannie Mae and Freddie Mac to purchase and securitize these insured loans, potentially expanding access to ADU financing.