

Maddy summaryHR 429, the Rosie the Riveter Commemorative Coin Act, authorizes the U.S. Treasury to mint and sell three types of commemorative coins ($5 gold, $1 silver, and half-dollar) to honor women who worked on the U.S. home front during World War II. The coins will be sold at face value plus surcharges ($35 for gold, $10 for silver, $5 for half-dollar), with all surcharge revenue directed to the Rosie the Riveter Trust to support the Rosie the Riveter WWII Home Front National Historical Park and related educational programs. The coins must be issued between January 1, 2028, and December 31, 2028, in specified quantities (50,000 gold, 400,000 silver, 750,000 half-dollar), with all costs covered by the sales revenue to avoid net government expense.
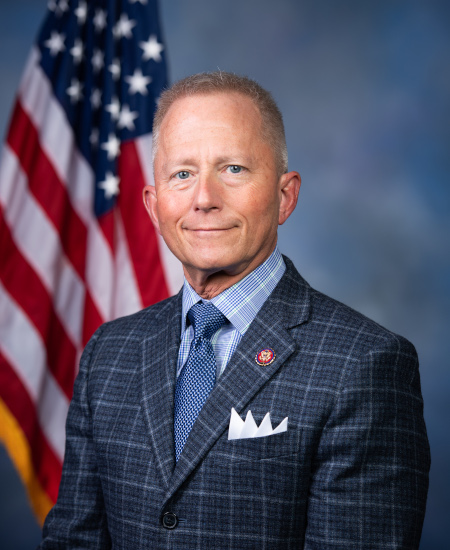
Rep. Jefferson Van Drew
Sponsored bills
Maddy summaryHR 418 requires federal agencies to have rules created under standard rulemaking procedures signed by a Senate-confirmed appointee or initiated by a senior agency official. This affects all agencies developing regulations, mandating that such rules follow specific leadership approval steps unless the agency head certifies public safety or security concerns require an exception. Agencies seeking to bypass this requirement must submit written justification to OIRA (Office of Information and Regulatory Affairs) and publish it in the Federal Register. OIRA will monitor compliance with these procedural requirements, which change the process for rulemaking without altering the substance of regulations.
Maddy summaryHR 413, the CHILD Act of 2025, increases the annual tax benefit limit for dependent care assistance programs from $5,000 to $10,000 (with $2,500 to $5,000 for single filers) for taxpayers using employer-sponsored dependent care accounts. It adds automatic annual cost-of-living adjustments to these limits based on inflation, rounding increases to the nearest $50. The bill also removes an outdated provision (previously referenced as subparagraph (D)) from the tax code. These changes directly affect working parents and caregivers who use dependent care benefits, applying to tax years beginning after December 31, 2024.
Maddy summaryThe READY Accounts Act creates a new tax-advantaged savings account that allows individuals to deduct up to $4,500 annually (adjusted for inflation) for contributions toward home disaster preparedness and recovery. These accounts can only be used for specific qualifying expenses, including disaster mitigation measures like reinforcing roofs, installing impact-resistant windows, or recovering from disaster damage like fire or storm. Contributions must be in cash, accounts must be administered by banks or approved entities, and distributions not used for qualifying expenses are taxable with a 20% additional tax penalty. The bill applies to taxable years beginning after December 31, 2024.
Maddy summaryHR 377, the Regulation Reduction Act of 2025, requires federal agencies to repeal three existing rules before issuing new ones that impose costs or responsibilities on businesses, state/local governments, or individuals. For major new rules, agencies must also certify that the new rule’s cost does not exceed the cost of the repealed rules. Agencies must publish all repealed rules in the Federal Register and submit a 90-day review to Congress identifying costly, ineffective, duplicative, or outdated regulations. This bill directly affects how federal agencies develop new rules, aiming to reduce regulatory burden by mandating rule removal before new rule creation.
Maddy summaryHR 378, the Thin Blue Line Act, adds a new aggravating factor for the death penalty in federal cases where a defendant kills or targets a law enforcement officer, firefighter, or other first responder. It specifically applies when the victim was killed or targeted while performing official duties, because of those duties, or due to their status as a public official. This amendment to federal death penalty law would make the death penalty a potential sentencing option for such crimes, as the killing would be considered an aggravating factor. The bill directly affects defendants convicted of homicides meeting these specific circumstances involving public safety personnel.
Maddy summaryHR 384, the One Agency Act, transfers primary antitrust enforcement authority from the Federal Trade Commission (FTC) to the Department of Justice's Antitrust Division. The bill requires the transfer of all FTC antitrust cases, employees, assets, and funding to the DOJ within a transition period of up to 18 months. During this period, the FTC is prohibited from opening new antitrust investigations or taking enforcement actions, while the DOJ assumes responsibility for ongoing cases. This consolidation aims to improve efficiency and reduce duplication in antitrust enforcement under a single agency.
Maddy summaryHR 351 amends the 1991 Intermodal Surface Transportation Efficiency Act to ban congestion pricing and cordon pricing in federal transportation value pricing programs. It directly affects how transportation projects funded under this law can manage traffic flow, prohibiting the use of these specific pricing strategies. The key provision adds a new rule stating the Secretary cannot establish or maintain such programs that include these pricing methods. This changes the legal framework for federal transportation funding without altering other program requirements.
Maddy summaryHR 352, the "Motorist Tax Abuse Act," blocks the implementation of congestion pricing in New York City's Central Business District Tolling Program. It amends a 1991 transportation law to prohibit the federal Secretary from establishing or maintaining cordon pricing under the value pricing pilot program for NYC's central business district. This directly affects NYC's planned tolling system for vehicles entering its downtown core. The bill is procedural, adding a specific federal prohibition without creating new policy.
Maddy summaryThis bill creates a toll credit for vehicles crossing specific bridges and tunnels before entering Manhattan's congestion zone. It requires the Transportation Secretary to certify that drivers using the Holland Tunnel, Lincoln Tunnel, or George Washington Bridge receive a credit equal to their bridge/tunnel toll when paying the congestion toll. The bill also adds a federal tax credit for taxpayers who pay congestion tolls before entering the zone, preventing double benefits with other deductions. It directly affects drivers using those crossings, the Metropolitan Transportation Authority (for grant eligibility), and taxpayers who pay these tolls. The policy change takes effect when congestion tolls begin and applies to tax years after enactment.