Chiropractic Medicare Coverage Modernization Act of 2021 This bill expands Medicare coverage of chiropractic services to include all services provided by chiropractors, rather than only subluxation corrections through manual manipulation of the spine.
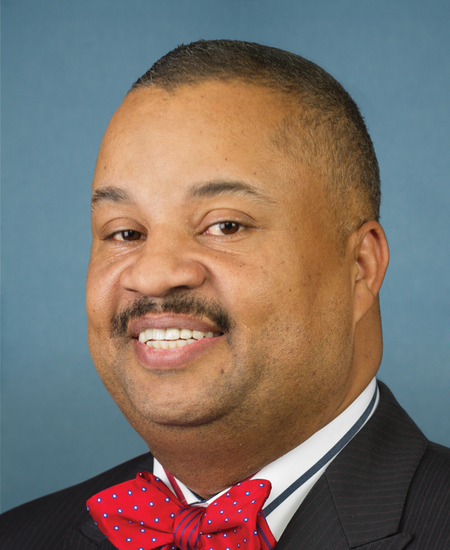
Rep. Donald M. Payne, Jr.
Sponsored bills
Amputation Reduction and Compassion Act of 2021 or the ARC Act of 2021 This bill provides for coverage of peripheral artery disease screening tests without cost-sharing under Medicare, Medicaid, and private health insurance for certain at-risk individuals, and requires the development of certain educational programs and Medicare quality measures to reduce amputations relating to such disease.
Workplace Violence Prevention for Health Care and Social Service Workers Act This bill requires the Department of Labor to address workplace violence in health care, social service, and other sectors. Specifically, Labor must issue an interim occupational safety and health standard that requires certain employers to take actions to protect workers and other personnel from workplace violence. The standard applies to employers in the health care sector, in the social service sector, and in sectors that conduct activities similar to those in the health care and social service sectors. In addition, Labor must promulgate a final standard within a specified time line.
Public Housing Fire Safety Act This bill creates a grant program, to be administered by the Department of Housing and Urban Development, for public housing agencies to install automatic sprinkler systems in certain public housing projects.
Colorectal Cancer Payment Fairness Act This bill eliminates Medicare coinsurance requirements with respect to colorectal cancer screening tests, regardless of the code billed for a resulting diagnosis or procedure, beginning in 2023 (rather than 2030).
FDA Modernization Act of 2021 This bill allows an applicant for market approval for a new drug to use methods other than animal testing to establish the drug's safety and effectiveness. Under this bill, these alternative methods may include cell-based assays, organ chips and microphysiological systems, sophisticated computer modeling, and other human biology-based test methods.
Fire Fighters and EMS Employer-Employee Cooperation Act This bill requires the Federal Labor Relations Authority to determine whether a state substantially provides fire and emergency medical services (EMS) personnel the right to form and join a labor organization; recognition by fire and EMS employers of the employees' labor organization, agreement to bargain with the organization, and reduction of any agreements to writing in a contract or memorandum of understanding; the right to bargain over hours, wages, and terms and conditions of employment; and arbitration or other mechanisms to resolve an impasse in collective bargaining negotiations. The bill makes the authority responsible for (1) determining the appropriateness of units for labor representation; (2) supervising elections; (3) conducting hearings and resolving complaints of unfair labor practices; and (4) protecting the right of employees to form, join, or assist any labor organization, or to refrain from doing so. An employer, fire and EMS personnel, or labor organization may not engage in a lockout, sickout, work slowdown, strike, or any other organized job action that will measurably disrupt the delivery of emergency services and is designed to compel an employer, fire and EMS personnel, or labor organization to agree to the terms of a proposed contract.

Tax Fairness for Workers Act This bill allows an above-the-line tax deduction for union dues and expenses. (An above-the-line deduction is subtracted from gross income and is available whether or not a taxpayer itemizes other deductions.) The bill also reinstates the miscellaneous itemized tax deduction for unreimbursed expenses attributable to the performance of services as an employee (Under current law, all miscellaneous itemized deductions are suspended through 2025).
Defending the Human Rights of Palestinian Children and Families Living Under Israeli Military Occupation Act This bill limits U.S. assistance to Israel and establishes reporting requirements related to Israel's activities in the West Bank and its expenditures for offshore procurement. Specifically, the bill prohibits the use of any funds that are made available for assistance to Israel in support of (1) military detention, interrogation, abuse, or ill treatment of Palestinian children; (2) seizure, appropriation, or destruction of Palestinian property and forcible transfer of civilians in the West Bank; or (3) unilateral annexation by Israel of West Bank territory. The Department of State must report on the nature and extent of such activities carried out by Israel. Further, the Government Accountability Office must submit a report identifying and analyzing Israel's expenditures for offshore procurement, including (1) specific programs and items to which funds for offshore procurement in Israel have been allocated, and (2) identifying all end-use monitoring to which Israel is subject with respect to U.S.-origin defense articles.
For the 99.5 Percent Act This bill imposes increased tax rates on decedent estates, gifts, and generation-skipping transfers. Estates with a value of over $1 billion are taxed at a 65% tax rate. The basic exclusion amount is reduced to $3.5 million. The bill increases (1) to $3 million the reduction in valuations of farmland for estate tax purposes and adjusts such increased amount for inflation, and (2) to $2 million the maximum estate tax exclusion for contributions of conservation easements. It also increases to 60% the applicable percentage for such exclusion. The bill requires (1) consistent basis reporting for property acquired by gift and transfers in trust, and (2) executors of estates and donors of gifts required to file a gift tax return to disclose to the Department of the Treasury, and to recipients of any interest in an estate or a gift, information identifying the value of each interest received. The bill sets forth estate valuation rules for certain transfers of nonbusiness assets and limits estate tax discounts for certain individuals with minority interests in a business acquired from a decedent. The bill expands rules for valuing assets in grantor retained annuity trusts to require that (1) the right to receive fixed amounts from an annuity last for a term of not less than 10 years and not more than the life expectancy of the annuitant plus 10 years, and that such fixed amounts not decrease during the first 10 years of the annuity term, and (2) the remainder interest have a value when transferred that is not less than the the greater of 25% of the fair market value of the trust property or $500,000. The bill also sets forth rules for the application of transfer taxes to a grantor trust (a trust in which the grantor retains control over the trust assets and has the right to receive income from the trust). The bill eliminates the generation-skipping transfer tax exemption for any trust whose termination date is not greater than 50 years after its creation. The bill modifies the tax exclusion for annual gifts to eliminate the present interest requirement for such exclusion and to impose a new, aggregate per donor limit equal to twice the annual exclusion amount in effect for the taxable year.