

Maddy summaryHR 2257 authorizes the U.S. Mint to produce three commemorative coins (a $5 gold coin, a $1 silver coin, and a half-dollar) to honor fallen firefighters, with specific quantity limits and specifications. The bill requires a surcharge ($35 for gold, $10 for silver, $5 for half-dollar) on each coin sold, which is directed entirely to the National Fallen Firefighters Foundation to support its programs. The coins must be issued in 2026, will be legal tender, and the government must recover all costs through sales before distributing funds to the Foundation. This is a commemorative coin program, not a direct legislative policy change affecting broader public programs.
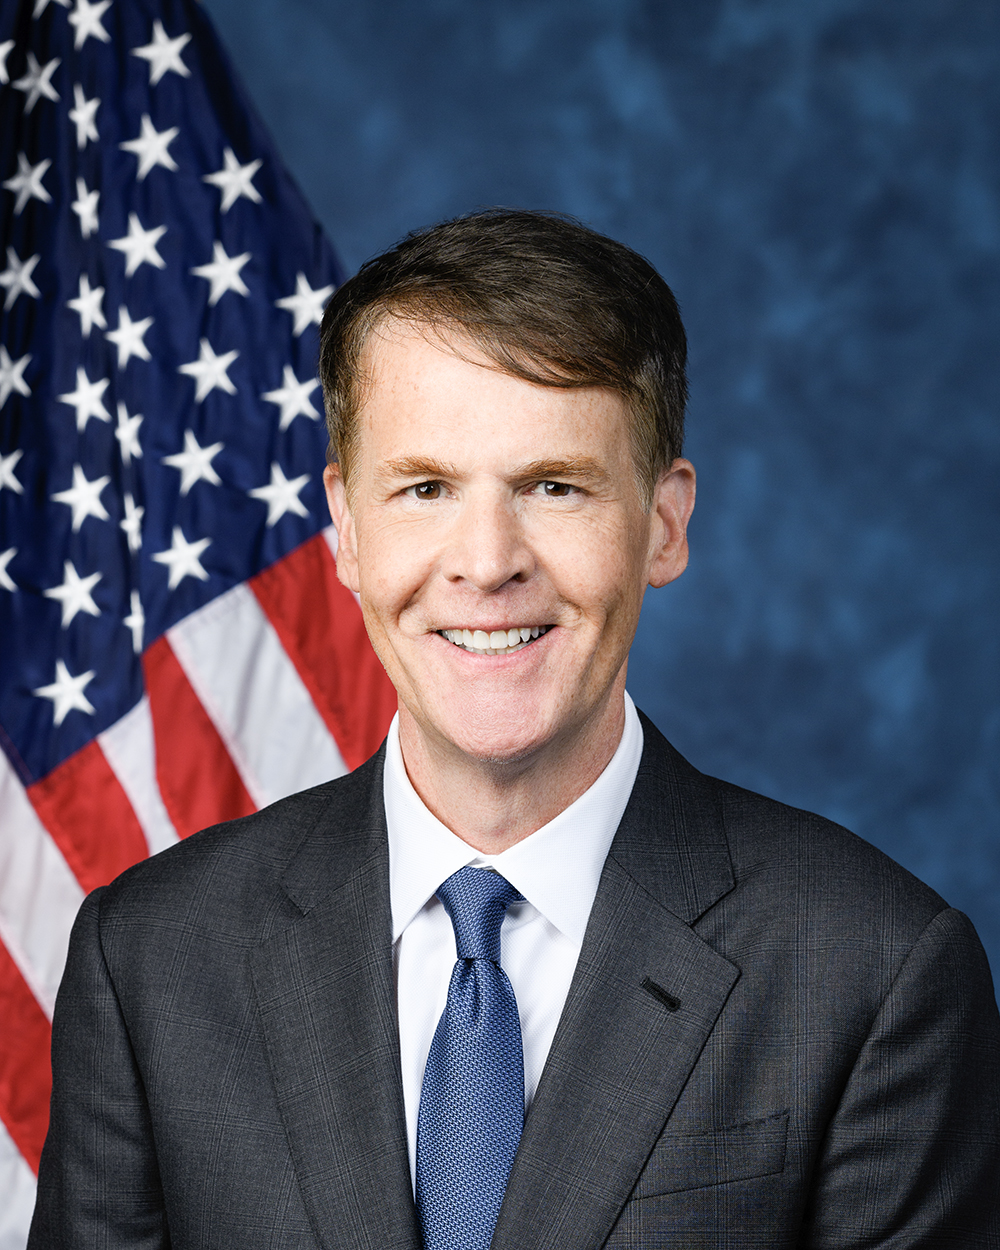
Rep. Jefferson Shreve
Sponsored bills
Maddy summaryThe Innovative FEED Act of 2025 establishes a new regulatory category for "zootechnical animal food substances" - additives in animal feed that affect digestive byproducts, reduce foodborne pathogens, or alter an animal's gut microbiome without providing nutrition. These substances would be regulated as food additives (not drugs) under the Federal Food, Drug, and Cosmetic Act, requiring manufacturers to submit specific safety and efficacy data for approval. The bill mandates labeling stating "Not for use in the diagnosis, cure, mitigation, treatment, or prevention of disease in animals" and allows optional claims about intended effects on animal body function. It explicitly excludes existing drugs, hormones, ionophores, and other substances from this category, ensuring no mandatory use of these additives.
Maddy summaryThis bill delays two Medicare billing deadlines for ground ambulance services from 2025 to 2028. It amends the Social Security Act to extend the timeline for implementing specific billing rules under Section 1834(l). The change directly affects Medicare ambulance providers by postponing compliance deadlines for billing requirements. No new services or funding are created - only a technical extension of existing timelines.
Maddy summaryThis bill amends the tax code to permanently establish a 7-year depreciation period for motorsports entertainment complexes, replacing a temporary provision. It directly affects businesses operating these facilities by allowing them to deduct the cost of qualifying assets over seven years instead of a shorter period. The key change is removing a temporary rule (subparagraph D) from the tax code, making the longer recovery period permanent for these specific properties. The bill focuses solely on clarifying and extending this tax treatment without additional policy changes.
Maddy summaryThe Credit for Caring Act of 2025 creates a federal tax credit for family caregivers of elderly or disabled relatives. It allows eligible caregivers (with over $7,500 in earned income) to claim a credit equal to 30% of qualified caregiving expenses exceeding $2,000, capped at $5,000 per year. Qualified expenses include human assistance, home modifications, respite care, counseling, lost wages for unpaid time off, and transportation, all requiring certification from a licensed healthcare provider that the care recipient has long-term needs. The credit phases out for higher earners (over $75,000 single/$150,000 joint) and requires documentation of expenses and care recipient certification.
Maddy summaryThe JUDGES Act of 2025 authorizes the creation of new federal district court judgeships across multiple jurisdictions to address rising caseloads. It specifies adding 1-2 new judges to 11 federal districts in 2025, with additional judgeships phased in through 2035 across California, Texas, Florida, New York, and other states. The bill also establishes temporary judgeships for Oklahoma's eastern district with specific vacancy rules, authorizes funding for these positions through 2035, and requires GAO reports on judicial caseload methodologies and detention space needs. This legislation directly affects federal courts in 15 states by increasing judicial staffing to address a 30% rise in filings since 1990, as noted in the bill's findings.
Maddy summaryThis bill adds a new tax provision (Section 139J) to the Internal Revenue Code, excluding interest income from certain rural and agricultural loans from taxable income for qualifying lenders. It directly affects banks, insurance companies, and farm credit entities that provide loans secured by rural or agricultural property (including qualifying single-family homes in rural areas), while excluding loans to foreign adversary entities (like those linked to China, Russia, or Iran). The law requires lenders to report on how this tax exclusion impacts loan interest rates, with a Treasury report due to Congress within five years. The policy change aims to reduce lenders' tax burden on these specific loans, potentially lowering costs for borrowers in rural communities.
Maddy summaryHR 1818, the Aviation Workforce Development Act, expands tax-advantaged 529 college savings plans to cover costs for aviation maintenance and commercial pilot training. It allows families to use 529 funds for tuition, fees, books, and equipment at qualifying schools - specifically aviation maintenance technician programs under FAA Part 147 rules or commercial pilot courses at FAA-certified flight schools (Part 61 or Part 141). The bill directly affects students pursuing these aviation careers by making their training more affordable through existing tax-advantaged savings accounts. The change applies to distributions made after the law's enactment date.
Maddy summaryThis bill extends the exclusivity period for certain advanced drugs from 7 to 11 years. It defines "advanced drug product" as a drug using genetically targeted technology to modulate gene function (e.g., suppress or activate genes). This change directly affects pharmaceutical companies developing these specific advanced therapies by granting them longer market exclusivity. The policy change modifies the Social Security Act to provide extended protection for these innovative drugs, allowing companies more time to recoup research and development costs.
Maddy summaryThis bill awards a Congressional Gold Medal to the 761st Tank Battalion (known as the "Black Panthers"), the first predominantly Black armored unit in World War II's European Theater. It recognizes their combat service from 1944-1946, including key roles in the Battle of the Bulge and breaking the Siegfried Line, despite facing racial prejudice during and after the war. The medal will be displayed at the National Museum of African American History and Culture, with bronze duplicates available for sale to cover costs. The bill commemorates the battalion's 130,000 enemy casualties inflicted, 50% casualty rate, and their 1978 Presidential Unit Citation. It does not create new laws or affect current policies.