

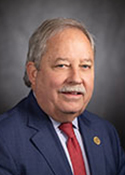
Photo of Richard Hayes
R Texas House · District 57 On the 2026 ballot

Rep. Richard Hayes

Compare
Total votes
5,803
all sessions
Attendance
97%
185 missed
Near the chamber average
With party
85%
of cast votes
Near the chamber average
Bipartisan score
8%
crosses aisle rarely
Near the chamber average
Sponsored
728
bills & resolutions
Higher than 98% of chamber peers
Committees
3
assignments
728 bills and resolutions

Sponsored bills

Total
728
Primary
144
Co-sponsor
584
This page
728
matching current filters
Co-sponsor HB 1392
Signed into law · Texas House · Co-sponsor
Relating to the postponement of the delinquency date for a payment of ad valorem taxes imposed by a taxing unit if the office of the collector for the taxing unit is closed on the delinquency date.

Maddy summaryHB 1392 amends Texas Tax Code Section 1.06 to automatically postpone property tax payment deadlines if the local tax collector's office is closed on the due date. This directly affects property owners in Texas counties, cities, or school districts who would otherwise face penalties for late payments on days when tax offices are closed (e.g., weekends, holidays, or unexpected closures). The bill ensures payments made on the next regular business day are considered timely, eliminating penalties for missed deadlines due to office closures. It takes effect January 1, 2026, and represents a procedural adjustment to existing tax payment rules.

Signed into law May 24, 2025 1 co-sponsor
Co-sponsor HB 22
Signed into law · Texas House · Co-sponsor
Relating to the exemption from ad valorem taxation of intangible personal property.

Maddy summaryHB 22 exempts intangible personal property (such as stocks, bonds, and intellectual property) from Texas property taxes. It removes previous exceptions that required certain intangible assets to be taxed, making all such property fully exempt under the Tax Code. This change directly affects owners of intangible assets and counties that previously collected taxes on these items. The law takes effect January 1, 2026, applying only to tax years beginning after that date.

Signed into law May 24, 2025 1 co-sponsor
Co-sponsor HB 1089
Signed into law · Texas House · Co-sponsor
Relating to creation of the gulf coast protection account to be administered by the General Land Office.

Maddy summaryHB 1089 creates a dedicated "Gulf Coast Protection Account" within the state's general revenue fund, managed by Texas' General Land Office. The account is funded by gifts, donations, grants, and legislative appropriations. Money from this account can only be spent on projects to fulfill federal project requirements under the 2021 Coastal Texas Protection and Restoration Study, comply with local Gulf Coast Protection District agreements, or fund specific coastal protection projects along the Texas Gulf Coast. The bill explicitly states these expenditures serve a public purpose and are subject to state audit.

Signed into law May 24, 2025 1 co-sponsor
Co-sponsor HR 1028
Passed · Texas House · Co-sponsor
Recognizing May 21, 2025, as Texas Capitol Staff Appreciation Day.

Maddy summaryHR 1028 designates May 21, 2025, as "Texas Capitol Staff Appreciation Day" to symbolically recognize legislative staff members for their work supporting Texas lawmakers. This ceremonial resolution, adopted by the Texas House of Representatives, expresses formal appreciation for staff employed in state lawmaker offices and legislative agencies. It has no legal effect, funding requirements, or policy changes - it solely serves as a symbolic gesture of recognition. The bill passed the House on May 23, 2025, and is now enrolled.

Passed May 24, 2025 1 co-sponsor
Primary HB 3778
Passed · Texas House · Lead sponsor
Relating to the use of geothermal energy as a dispatchable generation resource.

Maddy summaryHB 3778 defines geothermal energy facilities as "dispatchable" under Texas law, meaning their power output can be controlled by human operators. This reclassification directly affects geothermal developers in the ERCOT grid region by making their facilities eligible for state financial incentives. The bill creates two key provisions: (1) loans for upgrading existing dispatchable facilities (minimum 100MW capacity increase) and (2) completion grants for new dispatchable facilities (minimum 100MW capacity), excluding electric storage facilities. These mechanisms aim to incentivize geothermal energy development as a reliable power source within Texas' energy grid.

Passed May 23, 2025 0 co-sponsors
Co-sponsor HCR 102
Passed · Texas House · Co-sponsor
Urging Congress to preserve Sections 45U, 45Y, and 48E of the Internal Revenue Code.

Maddy summaryThis Texas concurrent resolution urges Congress to preserve Sections 45U, 45Y, and 48E of the federal tax code, which provide tax incentives for nuclear and natural gas energy projects. It directly addresses Texas' energy sector, which relies on these provisions to maintain existing operations and support new development, employing over 12,000 workers in nuclear/gas plants and supplying nearly half the state's electricity. The resolution requests Congress preserve these tax incentives to sustain affordable energy production and Texas' leadership in electricity generation.

Passed May 22, 2025 1 co-sponsor
Co-sponsor SB 530
Signed into law · Texas Senate · Co-sponsor
Relating to the accreditation of certain postsecondary educational institutions in this state or of certain programs offered by those institutions.

Maddy summarySB 530 limits how many credit hours Texas public colleges and universities can require students to complete for associate and bachelor's degrees beyond the minimum set by their institution's accrediting agency. It ensures students transferring between public institutions receive credit for completed courses in similar programs, unless required by their accrediting agency. The bill also requires universities to maintain accreditation by a recognized agency to operate as general academic institutions. These changes apply to all public higher education institutions in Texas and take effect September 1, 2025.

Signed into law May 20, 2025 1 co-sponsor
Co-sponsor SB 1035
Signed into law · Texas Senate · Co-sponsor
Relating to equitable relief from the enforcement of certain governmental requirements that affect agricultural operations.

Maddy summarySB 1035 allows agricultural operations (like farms and ranches) to sue local governments if those governments enforce rules that violate Texas agriculture laws. It creates a new legal right for affected businesses to seek court orders blocking enforcement of such rules and to recover legal fees if they win their case. The bill applies only to disputes arising after its effective date (September 1, 2025, unless passed with a two-thirds vote). This changes the process for resolving conflicts between local regulations and state agricultural law, giving farmers a direct legal remedy.

Signed into law May 19, 2025 1 co-sponsor
Co-sponsor HB 2658
Passed · Texas House · Co-sponsor
Relating to the Kimble County Hospital District of Kimble County, Texas.

Maddy summaryHB 2658 amends Texas Special District Local Laws Code to update governance and operational rules for Kimble County Hospital District. It reduces the residency requirement for board members from two to one year, removes the requirement for directors to post a $1,000 bond, and clarifies the district’s duty to provide hospital services through facilities like outpatient clinics, skilled nursing centers, and community health centers. The bill also adjusts budget preparation procedures, requiring annual budgets detailing expenditures, revenue estimates, and tax needs. These changes directly affect Kimble County residents who rely on the district’s healthcare services and the board members governing it. The legislation focuses on administrative clarity without creating new funding mechanisms or altering service eligibility.

Passed May 19, 2025 1 co-sponsor
Primary HB 3405
Passed · Texas House · Lead sponsor
Relating to the contents of a trust accounting.

Maddy summaryHB 3405 amends Texas Property Code sections 113.151(c) and 113.152 to change trust accounting rules. It allows courts, upon showing "good cause," to require trustees to separately allocate certain trust receipts and disbursements to principal or income - even when the distribution rules for both are identical. This clarifies that trustees must show these allocations in written accountings, unless the distribution standards for principal and income are the same. The law takes effect September 1, 2025, and applies only to trust accounting demands made after that date.

Passed May 19, 2025 0 co-sponsors
Showing 191 to 200 of 728 bills
Previous 1 … 19 20 21 … 73 Next