

Maddy summaryHB 1835 amends Pennsylvania's criminal code (Title 18) to address the offense of sexual abuse of children. The bill directly affects minors who are victims of such abuse and the legal system prosecuting these cases. It updates the existing statute to clarify or strengthen legal definitions and procedures for handling child sexual abuse offenses. The bill is currently pending in the Judiciary committee for further review.
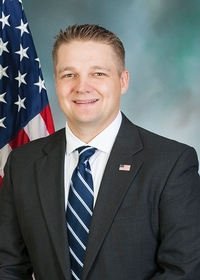
Rep. Aaron Bernstine
Sponsored bills
Maddy summaryHB 1819 amends Pennsylvania's vehicle inspection requirements under Title 75 of the Consolidated Statutes. It updates the rules for when vehicles must undergo periodic safety and emissions inspections. The bill directly affects all vehicle owners in Pennsylvania who are required to have their vehicles inspected regularly. Key provisions specify the revised schedule and procedures for these mandatory inspections, aiming to modernize the existing system. The bill is currently in the Transportation committee for review.
Maddy summaryHB 1820 transfers $500 million annually from Pennsylvania's Budget Stabilization Reserve Fund to a new Supplemental Roads and Bridges Account, starting 30 days after enactment and continuing through 2029. The funds, deposited into the Motor License Fund, are restricted exclusively for road and bridge projects including construction, maintenance, and repairs across the state. This bill directly affects the Pennsylvania Department of Transportation, which will use these allocations for infrastructure work without requiring new taxes. The legislation modifies existing vehicle tax statutes to redirect existing reserve funds rather than creating new revenue streams.
Maddy summaryHB 1815 would repeal the 1935 Individual Net Income Tax Act (P.L.970, No.314), which was the state's original personal income tax law. This bill removes the outdated 1935 statute from the legal code. The repeal would affect the state's tax legal framework but would not change current tax rates or filing procedures.
Maddy summaryHB 1813 repeals Pennsylvania's 1932 Emergency Relief Sales Tax Act, which imposed a 1% tax on sales of tangible personal property during a specific six-month period ending February 1933. The bill removes this historical tax provision, which was designed to fund emergency relief during the Great Depression and expired decades ago. No new taxes, requirements, or affected parties are created by this repeal, as the original law was never active in modern times. This is a straightforward legislative cleanup of an obsolete statute with no current impact on taxpayers or businesses.
Maddy summaryHB 1781 requires organizations receiving Pennsylvania state grants (like nonprofits or contractors) to verify the employment eligibility of new employees using the federal E-Verify system. It establishes a Commonwealth Grantee Employment Verification Account and mandates that grant recipients complete a specific verification form confirming their use of E-Verify before receiving grant funds. The bill imposes penalties for willful violations, such as failing to verify eligibility or providing false information, and prohibits discrimination during verification. This applies to all grantees, contractors, and subcontractors funded by state grants used for employee wages, directly affecting entities receiving public funding.
Maddy summaryHB 1763 aligns Pennsylvania's tax credit program with a federal tax credit for contributions to scholarship organizations. It requires scholarship organizations in Pennsylvania to verify their tax-exempt status, maintain separate accounts for scholarship funds, provide scholarships to at least 10 students from different schools, spend 90% of income on scholarships, and verify applicants' household income to ensure eligibility. Organizations must submit compliance documentation by June 1, 2026, and annually thereafter, with the state department confirming their eligibility for the federal tax credit. This directly affects scholarship organizations seeking to participate in the federal tax credit program, ensuring they meet federal requirements to allow donors to claim tax benefits.
Maddy summaryThis bill (HB 1746) is a joint resolution proposing a constitutional amendment related to sessions of Pennsylvania's General Assembly. The provided context does not describe the specific changes to session timing, duration, or other mechanics proposed by the amendment. No details are given about who would be directly affected by this constitutional change. As a procedural constitutional amendment proposal, the summary is limited by the lack of substantive bill text or description in the available context. The resolution was recently referred to the State Government committee on July 21, 2025.
Maddy summaryHB 1742 eliminates Pennsylvania's personal income tax for tax years beginning on or after January 1, 2026. It removes the requirement for employers to withhold income tax from wages starting in 2026 and repeals filing obligations for Pennsylvania S corporations for tax years starting after 2025. The bill directly affects Pennsylvania residents, employers, and S corporations by ending income tax liability, withholding, and related return filings for future tax years. Key provisions amend Sections 302(a), 323, 330(a), and 330.1(a) of the Tax Reform Code of 1971 to reflect these changes. The law takes effect immediately, but the tax changes apply only to tax years beginning in 2026 or later.
Maddy summaryHB 1740 would prohibit abortions for pregnancies at 24 or more weeks gestational age in Pennsylvania, directly affecting medical providers performing such procedures. The bill requires medical providers to examine for a fetal heartbeat before proceeding with an abortion and mandates that medical judgment be based on that examination. It also specifies that medical consultation must address the fetal heartbeat and the patient's condition. The bill is currently referred to the Judiciary committee, with no further action taken as of July 16, 2025.