

Maddy summaryHB 1840 amends Pennsylvania's Turnpike Commission Act to establish reduced toll rates for disabled veterans using the state turnpike system. It directly affects disabled veterans who are eligible for this benefit under the amended law. The key provision creates a specific lower toll rate category for qualifying veterans, streamlining access to reduced fares without requiring separate applications. This policy change modifies the existing toll structure to provide cost savings for this defined group of users.
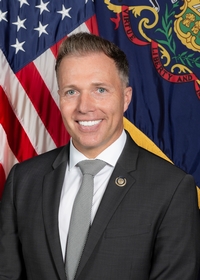
Rep. Dane Watro
Sponsored bills
Maddy summaryHB 1820 transfers $500 million annually from Pennsylvania's Budget Stabilization Reserve Fund to a new Supplemental Roads and Bridges Account, starting 30 days after enactment and continuing through 2029. The funds, deposited into the Motor License Fund, are restricted exclusively for road and bridge projects including construction, maintenance, and repairs across the state. This bill directly affects the Pennsylvania Department of Transportation, which will use these allocations for infrastructure work without requiring new taxes. The legislation modifies existing vehicle tax statutes to redirect existing reserve funds rather than creating new revenue streams.
Maddy summaryHB 1817 would amend Pennsylvania's criminal code to create a specific offense for interfering with or impeding first responders - such as police, firefighters, or paramedics - while they are performing emergency duties. The bill would add this as a new provision under the section on obstructing governmental operations, defining prohibited actions like physically blocking, threatening, or hindering emergency personnel. This change would make such interference a distinct criminal violation, potentially subjecting offenders to penalties under state law. The bill is currently under review by the Judiciary committee.
Maddy summaryHB 1763 aligns Pennsylvania's tax credit program with a federal tax credit for contributions to scholarship organizations. It requires scholarship organizations in Pennsylvania to verify their tax-exempt status, maintain separate accounts for scholarship funds, provide scholarships to at least 10 students from different schools, spend 90% of income on scholarships, and verify applicants' household income to ensure eligibility. Organizations must submit compliance documentation by June 1, 2026, and annually thereafter, with the state department confirming their eligibility for the federal tax credit. This directly affects scholarship organizations seeking to participate in the federal tax credit program, ensuring they meet federal requirements to allow donors to claim tax benefits.
Maddy summaryHB 1429 requires the state agency administering public assistance programs (like food stamps or cash aid) to submit a report detailing a transition plan to replace current access cards with secure chip-enabled electronic cards. The bill directly affects recipients of public assistance and the agencies managing these programs by mandating a formal report on how the switch to chip cards will be implemented. Key provisions include specifying the report must cover timelines, costs, and how the transition will ensure continued access for beneficiaries. This is a procedural bill focused on reporting requirements, not altering benefit eligibility or funding.
Maddy summaryHB 1672 creates a $2,500 annual tax credit against individual income tax for active paid or volunteer firefighters and emergency medical service (EMS) providers in Pennsylvania. It directly affects qualifying professionals working in fire or EMS roles as defined by state law, including career responders and volunteers. The credit reduces tax owed on wages earned, applies for up to three years (the year they become qualified plus the next two), and requires proof of eligibility to the Department of Revenue. The credit expires for new applicants after 2028 and ends entirely by December 31, 2031.
Maddy summaryHB 1666 increases Pennsylvania's minimum property damage liability coverage for auto insurance from $5,000 to $25,000 per accident. It updates definitions and requirements in vehicle insurance law, mandating that insurers offer higher coverage limits for bodily injury ($100,000/$300,000) and property damage, while requiring clear notice to policyholders about available benefits. This affects all drivers purchasing or renewing auto insurance policies in Pennsylvania, as insurers must now provide standardized disclosure of coverage options at application. The changes apply to policies issued or renewed 60 days after the bill's effective date.
Maddy summaryHB 825 amends Pennsylvania's public utilities law to allow utility companies to install "double utility poles" that carry both power lines and communication lines (like fiber optic cables) on the same pole structure. This change directly affects public utility providers regulated under Title 66 by altering their permitted infrastructure options. The key provision modifies the utilities' powers and duties to facilitate this dual-use pole configuration, potentially streamlining infrastructure deployment. Specific impacts on communities, costs, or regulatory details are not described in the provided context.
Maddy summaryHB 1649 eliminates school district property taxes on residential and commercial properties in Pennsylvania. It replaces these taxes with two new revenue sources: a 2% increase to county-level sales, use, and occupancy taxes (with some exclusions like clothing and candy removed), and a local income tax of up to 1.88% on resident taxpayers' earned income and retirement benefits (excluding Social Security). The bill establishes two funds - the School District Property Tax Elimination Fund (to distribute sales tax revenue to school districts) and the School District Emergency Fund - and requires landlords to reduce rents for tenants by the amount of eliminated property taxes. This directly affects property owners, school districts, and landlords/tenants, shifting funding responsibility from property taxes to broader consumption and income-based taxes.
Maddy summaryThe provided context does not include the substantive provisions or specific policy changes of HB 1306. The bill's title only indicates it amends definitions and classes of income under the 1971 Tax Reform Code, but no concrete details about tax rates, brackets, affected groups, or mechanisms are described in the available information. The recent actions (e.g., "Second consideration," "Final passage") reflect procedural steps, not policy content. Without specific language or policy changes outlined in the context, a factual summary of what the bill actually does cannot be provided.