

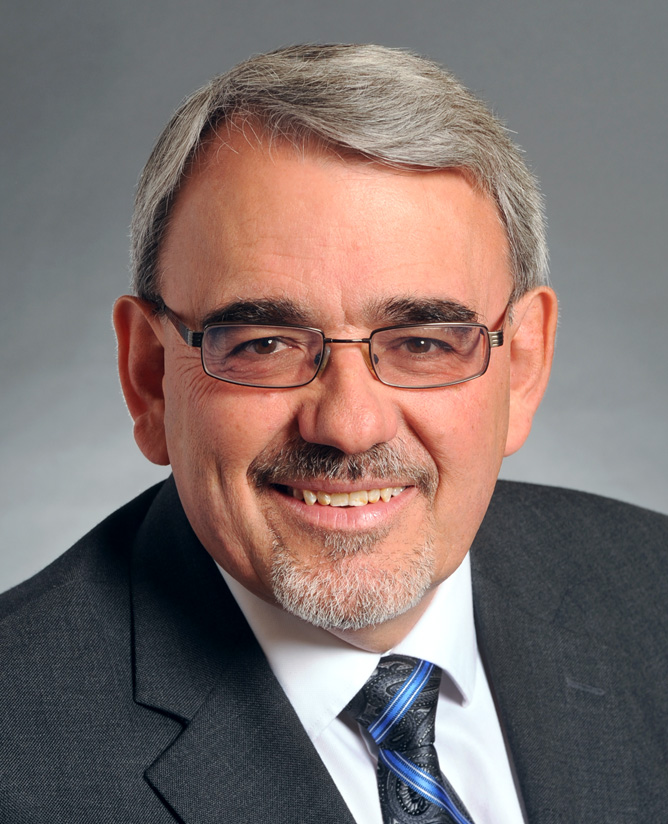
Photo of Bill Weber
R Minnesota Senate · District 21

Sen. Bill Weber

Compare
Total votes
23
all sessions
Attendance
88%
3 missed
Lower than 94% of chamber peers
With party
86%
of cast votes
Near the chamber average
Bipartisan score
7%
crosses aisle rarely
Near the chamber average
Sponsored
918
bills & resolutions
Near the chamber average
Committees
2
assignments
918 bills and resolutions

Sponsored bills

Total
918
Primary
387
Co-sponsor
531
This page
918
matching current filters
Co-sponsor SF 2101
In committee · Minnesota Senate · Co-sponsor
Inflation adjustment repeal for the child tax credit and working family credit

Maddy summaryThis bill repeals Minnesota's automatic inflation adjustments for two state tax credits: the child tax credit and the working family credit. It removes the requirement that the credit amounts and income thresholds be updated annually to match inflation, as currently mandated by law. As a result, these credits will no longer automatically increase with inflation for families claiming them after 2024. The change directly affects Minnesota families who qualify for these credits, as their benefit amounts will remain fixed at current levels without future inflation adjustments. The bill takes effect for taxable years beginning after December 31, 2024.

In committee Mar 3, 2025 1 co-sponsor
Co-sponsor SF 2076
In committee · Minnesota Senate · Co-sponsor
Homestead resort properties tier limits modification

Maddy summaryThis bill modifies Minnesota's tax classification for "homestead resort properties" (Class 1c), clarifying which resort properties qualify for a special tax rate. To qualify, properties must have at least three rental units (e.g., cabins, condos, or RV sites), limit commercial rentals to 250 days per year, and include owner-occupancy (where owners live in the property as homesteads via corporate or partnership ownership). Qualifying properties receive a reduced tax rate of 0.45% on the first $50,000 of value, with the remainder taxed at standard rates. This directly affects resort owners seeking tax benefits for properties blending owner residence with seasonal rentals, such as lakeside resorts.

In committee Mar 3, 2025 1 co-sponsor
Co-sponsor SF 1969
In committee · Minnesota Senate · Co-sponsor
Exemption expansion for purchases by nonprofit snowmobile clubs

Maddy summaryThis bill expands a sales tax exemption for nonprofit snowmobile clubs in Minnesota. It directly affects eligible clubs that maintain state or grant-in-aid snowmobile trails and have received a Department of Natural Resources maintenance grant in the current or previous three years. The key change adds grooming machines, attachments, accessories, and repair parts to the list of exempt purchases, alongside materials used for trail construction and maintenance. The exemption applies to qualifying purchases made after June 30, 2025.

In committee Feb 27, 2025 1 co-sponsor
Co-sponsor SF 1941
In committee · Minnesota Senate · Co-sponsor
All lawful gambling receipts flat rate tax enactment

Maddy summaryThis bill replaces Minnesota's existing tiered tax on gambling with a flat 8.5% tax on all lawful gambling gross receipts minus prizes paid. It directly affects gambling organizations (like casinos and racetracks) that currently pay a combined net receipts tax under Minnesota Statutes 297E.02, subdivision 6. The key change eliminates the previous multi-tiered tax structure (with rates from 8% to 33.5%) and simplifies the calculation to a single flat rate. The new tax takes effect July 1, 2025, and repeals the old tiered tax provision.

In committee Feb 27, 2025 1 co-sponsor
Primary SF 2008
In committee · Minnesota Senate · Lead sponsor
Public water and sewer systems instillation of water and sewer pipelines in public road rights-of-way authorization provision

Maddy summaryThis bill amends Minnesota law to explicitly allow public water districts, sewer districts, and combined water/sewer districts to install pipelines in public road rights-of-way. It adds these entities to the existing list of utilities (like telephone and power companies) already permitted to use public roads for infrastructure under Minnesota Statutes 222.37. The key provision requires these districts to follow the same notice and permitting rules as other utilities - such as notifying local governments before major construction - and to avoid interfering with road safety. It directly affects public water/sewer districts and local governments managing road rights-of-way.

In committee Feb 27, 2025 0 co-sponsors
Co-sponsor SF 44
In committee · Minnesota Senate · Co-sponsor
Vendor allowance provision

Maddy summarySF 44 modifies Minnesota's sales tax rules to establish a "vendor allowance," allowing retailers with $10,000 or more in annual sales tax liability to keep a portion of collected tax as compensation for collection costs. The allowance equals a percentage of eligible taxes collected (with a minimum $10 per reporting period), calculated under new section 297A.816. It affects most retailers (excluding construction material vendors under specific conditions), requiring them to report and remit the remaining tax via electronic payment by specified deadlines. The bill takes effect for sales after June 30, 2025, and updates tax code sections 289A.20 and 297A.77.

In committee Feb 27, 2025 1 co-sponsor
Primary SF 1921
In committee · Minnesota Senate · Lead sponsor
Slayton child care center bond issue and appropriation

Maddy summarySF 1921 appropriates $3 million from state bonds to fund the design, construction, and equipment for a new child care center in Slayton. The city of Slayton will receive a grant from this fund to build the facility, with the state issuing bonds to cover the cost under Minnesota's bond sale procedures. The bill enables the project through state financing without requiring additional local funding. This directly supports Slayton's ability to establish a new child care facility under existing grant rules.

In committee Feb 27, 2025 0 co-sponsors
Primary SF 2018
In committee · Minnesota Senate · Lead sponsor
Certain uses of B100 fuel inclusion as a carbon-free energy technology

Maddy summarySF 2018 amends Minnesota's clean energy standard to include electricity generated from biodiesel fuel (B100) used in peaking facilities as a carbon-free energy technology. It allows electric utilities to count up to 400 annual hours of biodiesel-powered electricity toward their state-mandated carbon-free energy requirements (80% by 2030 for public utilities, 100% by 2040). This specifically applies to peaking facilities using pure biodiesel fuel (as defined in Minn. Stat. § 239.77) during their first 400 hours of annual operation. The bill directly affects electric utilities required to meet Minnesota's carbon-free energy targets under Minn. Stat. § 216B.1691. It expands the definition of qualifying carbon-free sources without altering the overall percentage targets.

In committee Feb 27, 2025 0 co-sponsors
Primary SF 2014
In committee · Minnesota Senate · Lead sponsor
Cottonwood County refundable exemption provision for construction materials for certain projects

Maddy summaryThis bill provides a refundable sales tax exemption for construction materials used in Cottonwood County's Public Works Maintenance Facility in Windom. It exempts materials purchased between December 20, 2024, and December 31, 2026, from Minnesota's sales tax, with the tax collected upfront and refunded later. Refunds won't be issued before July 1, 2025, and are funded through a general fund appropriation. The policy directly affects contractors and suppliers selling materials for this specific county facility during the covered period.

In committee Feb 27, 2025 0 co-sponsors
Co-sponsor SF 1769
In committee · Minnesota Senate · Co-sponsor
Requirements modification for well disclosures certificates

Maddy summaryThis bill modifies Minnesota's real estate disclosure requirements for wells. It requires sellers to provide a written disclosure about wells on property before sale, and at closing, to submit a "well disclosure certificate" to the Department of Health for a $50 fee. The certificate must include well locations (using legal descriptions or lot/block details), buyer information, and a unique certificate number that must appear on the property deed. The requirement applies to most real estate sales but does not cover mineral interest transfers or individual condominium units, and expires July 31, 2028.

In committee Feb 24, 2025 1 co-sponsor
Showing 101 to 110 of 918 bills
Previous 1 10 11 12 92 Next