

Maddy summaryHR 685, the SAVE Moms and Babies Act of 2025, prohibits the FDA from approving new abortion drugs or allowing investigational use of existing ones. It restricts existing abortion drugs to in-person administration by certified healthcare providers in clinics or hospitals (not pharmacies), limits use to pregnancies under 70 days gestation, and requires providers to certify they can handle complications like severe bleeding or ectopic pregnancies. The bill mandates reporting of adverse events (such as hospitalizations or infections) to the FDA without patient identifiers and defines "abortion drug" broadly as any drug intended to terminate pregnancy, excluding specific medical exceptions. This directly affects FDA approval processes, healthcare providers prescribing these drugs, and drug manufacturers.
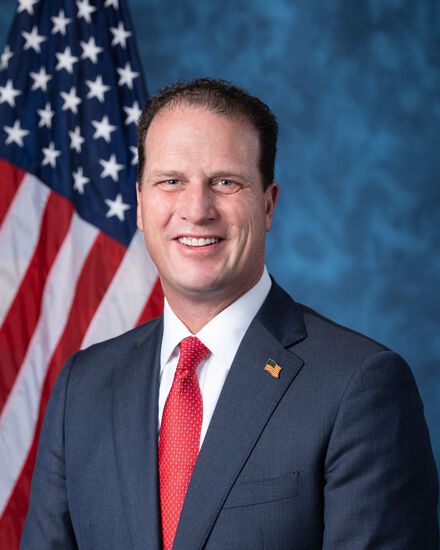
Rep. August Pfluger
Sponsored bills
Maddy summaryHR 703, the Main Street Tax Certainty Act, makes a key tax deduction permanent for small business owners. It removes the temporary sunset provision (subsection (i)) from Section 199A of the tax code, ensuring the qualified business income deduction remains available for eligible small businesses. This change directly affects pass-through business owners (like S-corps, partnerships, and sole proprietorships) who currently qualify for this deduction. The permanent change takes effect for tax years starting after December 31, 2025.
Maddy summaryHR 662 amends the tax code to change how oil and gas companies calculate taxable income related to intangible drilling and development costs. It allows companies to disregard certain depreciation and depletion expenses recorded on their financial statements when computing taxable income, effectively reducing their tax burden on these specific costs. The bill directly affects oil and gas producers who use intangible drilling costs in their operations. The changes apply to taxable years beginning after December 31, 2025. This is a tax code adjustment, not a direct policy change for energy production.
Maddy summaryThis bill amends the legal definition of "firearm silencer" and "firearm muffler" under federal law. It clarifies that these terms include any device designed to reduce firearm noise, as well as the outer tube or primary housing component that serves as the main structure for noise-reduction parts. The definition specifically covers devices intended to attach to a firearm (directly or via mounts) and excludes other firearms. This change affects how silencers are legally categorized under federal regulations, not who can own them. It does not create new restrictions but refines the scope of existing definitions.
Maddy summaryHR 7 prohibits federal funds from being used for abortions or health insurance plans covering abortion, with exceptions for pregnancies resulting from rape, incest, or when a woman's life is endangered. It blocks federal premium tax credits under the Affordable Care Act for health plans covering abortion (except in specified cases) and requires clear disclosure of abortion coverage and related surcharges in plan materials. The bill allows individuals or employers to purchase separate abortion coverage using non-federal funds, such as out-of-pocket payments, without affecting federal subsidies. It directly affects federal health programs, ACA marketplace plans, and health insurance issuers offering coverage that includes abortion services.
Birthright Citizenship Act of 2025 This bill limits birthright citizenship by redefining what it means to be subject to the jurisdiction of the United States. Currently, a person born in the United States and subject to U.S. jurisdiction is entitled to citizenship. Under the bill, a person is subject to U.S. jurisdiction if he or she is born to a parent who is (1) a U.S. citizen or national, (2) a lawful permanent resident residing in the United States, or (3) a non-U.S. national ( alien under federal law) with a lawful immigration status who is performing active service in the Armed Forces. The bill does not affect the citizenship or nationality status of any person born before the bill's enactment date.
Maddy summaryHR 563 requires the Bureau of Alcohol, Tobacco, Firearms and Explosives (ATF) to destroy all firearm transaction records from discontinued businesses within 90 days of the law's enactment. It also amends a federal law to prevent future registration of such transactions by removing language that required these records to be delivered to the Attorney General. The bill mandates that the ATF submit a report to Congress detailing how many records were destroyed. This legislation directly affects ATF record-keeping procedures, not individual gun owners or firearm ownership rights.
Maddy summaryHRES 50 is a symbolic resolution, not a bill with policy changes. It declares that states bordering Mexico have the constitutional right under Article I, Section 10 to defend against "paramilitary, narco-terrorist cartels" and criminal actors at the southern border. The resolution states that states like Texas, Arizona, New Mexico, and California were "invaded" or faced "imminent danger" from these groups from 2021-2024, and that the federal government failed to protect them. It makes no new laws or allocate funds - only asserts a constitutional interpretation for states to act unilaterally. (Note: This is a procedural resolution; no concrete policy change is enacted.)
Chiropractic Medicare Coverage Modernization Act of 2025 This bill expands Medicare coverage of chiropractic services to include all services provided by chiropractors, rather than only subluxation corrections through manual manipulation of the spine.
This bill increases the annual limit on the tax credit for qualified railroad track maintenance expenses (also referred to as the short line railroad tax credit) and expands eligibility for claiming the credit. Under current law, the tax credit is limited each tax year to $3,500 multiplied by the sum of the number of miles of railroad track owned or leased by the taxpayer (miles owned or leased) and the number of railroad track miles assigned to the taxpayer by a Class II or III railroad (miles assigned). This bill increases the annual limit to $6,100 multiplied by the sum of miles owned or leased and miles assigned. The $6,100 amount used in the calculation of the tax credit limit is adjusted for inflation for tax years beginning after 2025. The bill also expands eligibility for the tax credit to include gross expenses for maintaining railroad tracks owned or leased as of January 1, 2024. Under current law, the tax credit is limited to gross expenses for maintaining railroad tracks owned or leased as of January 1, 2015.