

Maddy summaryHR 21, the Born-Alive Abortion Survivors Protection Act, requires medical staff at abortion facilities to provide the same immediate care and hospital admission to any infant born alive during an abortion as they would for any newborn. It mandates reporting failures to provide this care to law enforcement and imposes penalties of up to 5 years in prison for violations, with harsher penalties for intentional killing. The bill also allows women who undergo abortions to sue for civil damages, including triple the abortion cost, and provides for attorney fees. It defines "abortion" to exclude procedures performed after viability to preserve a live birth. This law directly affects healthcare providers at abortion facilities and creates new federal legal obligations for them.
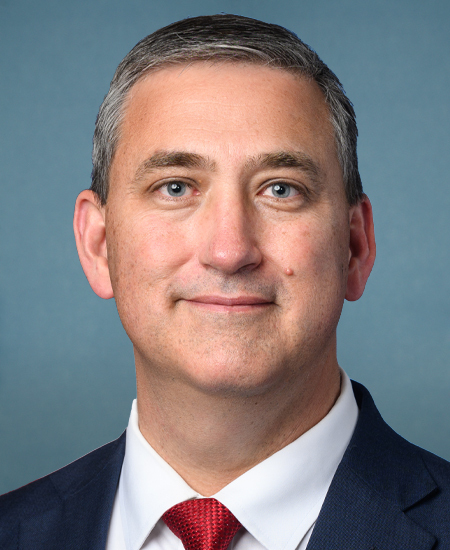
Rep. Nathaniel Moran
Sponsored bills
Maddy summaryHR 685, the SAVE Moms and Babies Act of 2025, prohibits the FDA from approving new abortion drugs or allowing investigational use of existing ones. It restricts existing abortion drugs to in-person administration by certified healthcare providers in clinics or hospitals (not pharmacies), limits use to pregnancies under 70 days gestation, and requires providers to certify they can handle complications like severe bleeding or ectopic pregnancies. The bill mandates reporting of adverse events (such as hospitalizations or infections) to the FDA without patient identifiers and defines "abortion drug" broadly as any drug intended to terminate pregnancy, excluding specific medical exceptions. This directly affects FDA approval processes, healthcare providers prescribing these drugs, and drug manufacturers.
Maddy summaryHR 645, the National Constitutional Carry Act, would prevent all U.S. states and localities from requiring permits or imposing penalties for carrying firearms in public. It directly affects eligible U.S. citizens (including non-residents) who legally possess firearms under state and federal law, removing current permit requirements for public carry. The bill’s key provision amends federal law to invalidate any state or local law that criminalizes or discourages public firearm carry, except where private property owners clearly prohibit firearms or security screening occurs. This would override existing state permit laws, making permitless carry legal across all states and territories for qualified individuals.
Maddy summaryHR 703, the Main Street Tax Certainty Act, makes a key tax deduction permanent for small business owners. It removes the temporary sunset provision (subsection (i)) from Section 199A of the tax code, ensuring the qualified business income deduction remains available for eligible small businesses. This change directly affects pass-through business owners (like S-corps, partnerships, and sole proprietorships) who currently qualify for this deduction. The permanent change takes effect for tax years starting after December 31, 2025.
Maddy summaryHR 662 amends the tax code to change how oil and gas companies calculate taxable income related to intangible drilling and development costs. It allows companies to disregard certain depreciation and depletion expenses recorded on their financial statements when computing taxable income, effectively reducing their tax burden on these specific costs. The bill directly affects oil and gas producers who use intangible drilling costs in their operations. The changes apply to taxable years beginning after December 31, 2025. This is a tax code adjustment, not a direct policy change for energy production.
Maddy summaryHJRES 28 proposes a constitutional amendment to permanently fix the number of justices on the U.S. Supreme Court at nine. This would require ratification by 38 state legislatures (three-fourths of states) within seven years to become part of the Constitution. The amendment directly affects the structure of the Supreme Court, which has had nine justices since 1869 but could otherwise be altered by future congressional action. It does not change current court operations or create new laws, but instead seeks to make the nine-justice composition a permanent constitutional requirement.
Maddy summaryHR 640, the Chemical Tax Repeal Act, eliminates excise taxes on specific chemicals previously levied under Internal Revenue Code Chapter 38. It directly affects chemical manufacturers and distributors who paid these taxes on certain substances. The bill repeals the relevant tax provisions by amending the Internal Revenue Code, removing subchapters B and C of Chapter 38. This change takes effect on January 1, 2024, ending the tax requirement for covered chemicals.
Maddy summaryHR 7 prohibits federal funds from being used for abortions or health insurance plans covering abortion, with exceptions for pregnancies resulting from rape, incest, or when a woman's life is endangered. It blocks federal premium tax credits under the Affordable Care Act for health plans covering abortion (except in specified cases) and requires clear disclosure of abortion coverage and related surcharges in plan materials. The bill allows individuals or employers to purchase separate abortion coverage using non-federal funds, such as out-of-pocket payments, without affecting federal subsidies. It directly affects federal health programs, ACA marketplace plans, and health insurance issuers offering coverage that includes abortion services.
Birthright Citizenship Act of 2025 This bill limits birthright citizenship by redefining what it means to be subject to the jurisdiction of the United States. Currently, a person born in the United States and subject to U.S. jurisdiction is entitled to citizenship. Under the bill, a person is subject to U.S. jurisdiction if he or she is born to a parent who is (1) a U.S. citizen or national, (2) a lawful permanent resident residing in the United States, or (3) a non-U.S. national ( alien under federal law) with a lawful immigration status who is performing active service in the Armed Forces. The bill does not affect the citizenship or nationality status of any person born before the bill's enactment date.
Maddy summaryThis bill requires the Treasury Secretary to regularly report to Congress about foreign countries that impose taxes on U.S. businesses or individuals considered unfair (extraterritorial or discriminatory taxes). For countries identified in these reports, it authorizes the U.S. to increase tax rates on income and withholdings from those countries, starting at 5% and increasing up to 20% over time. The bill also allows the U.S. to prohibit federal government purchases from entities in those countries and to consider these tax policies when negotiating tax treaties or trade agreements. It would directly affect U.S. businesses and individuals doing business with countries that have these tax policies, as well as those countries' businesses operating in the U.S.