

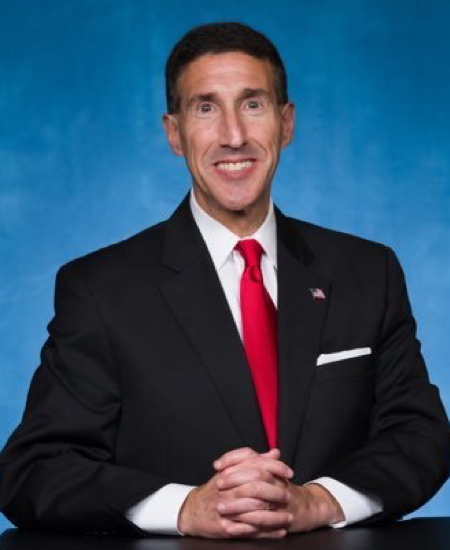
Photo of David Kustoff
R United States House · District 8 · Tennessee On the 2026 ballot

Rep. David Kustoff

Compare
Total votes
2,837
all sessions
Attendance
98%
48 missed
Higher than 78% of chamber peers
With party
96%
of cast votes
Higher than 90% of chamber peers
Bipartisan score
2%
crosses aisle rarely
Lower than 91% of chamber peers
Sponsored
718
bills & resolutions
Lower than 76% of chamber peers
Committees
3
assignments
718 bills and resolutions

Sponsored bills

Total
718
Primary
82
Co-sponsor
636
This page
718
matching current filters
Co-sponsor HR 2346
In committee · Indiana House · Co-sponsor
Accountability for Terrorist Perpetrators of October 7th Act

Maddy summaryThis bill imposes U.S. economic sanctions and visa restrictions on the Popular Resistance Committees (PRC) and related entities, targeting individuals and groups linked to the October 7, 2023, attacks on Israel. It requires the President to block assets and deny visas to PRC members, affiliates, and any group operating under their umbrella, effective 90 days after enactment. The law also mandates a report within 90 days on whether "Lion’s Den" meets criteria for terrorism designation under existing U.S. law. These measures apply specifically to designated terrorist organizations and their networks, without altering broader U.S. counterterrorism policy.

In committee Mar 25, 2025 1 co-sponsor
Co-sponsor HR 2198
In committee · Indiana House · Co-sponsor
To amend the Internal Revenue Code of 1986 to restore the taxable REIT subsidiary asset test.

Maddy summaryThis bill changes a tax rule for Real Estate Investment Trusts (REITs) that use taxable subsidiaries. It increases the percentage limit for assets held in these subsidiaries from 20% to 25% of a REIT's total assets, directly affecting REIT companies that operate through such subsidiaries. The key provision amends the Internal Revenue Code to restore this higher asset threshold, which had been reduced earlier. The change applies to taxable years starting after December 31, 2025.

In committee Mar 18, 2025 1 co-sponsor
Co-sponsor HR 2172
In committee · Indiana House · Co-sponsor
Preserving Patient Access to Home Infusion Act

Preserving Patient Access to Home Infusion Act  This bill specifically includes pharmacy services and home infusion drugs that are administered without a pump as part of covered home infusion therapy under Medicare. The bill also allows nurses and physician assistants to establish and review the plan of care for home infusion therapy, and it specifies that payment may be made regardless of whether a practitioner is physically present in the home at the time the drug is administered.

In committee Mar 18, 2025 1 co-sponsor
Co-sponsor HR 2126
In committee · Indiana House · Co-sponsor
FOCA Act of 2025

Maddy summaryThe FOCA Act of 2025 prohibits federal agencies from requiring or banning contractors from using union agreements in construction project bids or contracts. It directly affects federal agencies, contractors, and subcontractors working on federally funded or assisted construction projects (like buildings or infrastructure). The law requires bid documents to not favor or penalize contractors based on whether they have union agreements, aiming to promote open competition and prevent discrimination. This changes how agencies structure bids but does not affect union agreements themselves. The bill applies to all new contracts and subcontracts after enactment, with limited exemptions only for public health/safety emergencies or national security.

In committee Mar 14, 2025 1 co-sponsor
Co-sponsor HR 1156
Passed · Indiana House · Co-sponsor
Pandemic Unemployment Fraud Enforcement Act

Maddy summaryHR 1156, the Pandemic Unemployment Fraud Enforcement Act, extends the time limit for prosecuting fraud related to pandemic unemployment programs. It adds a 10-year window for criminal or civil actions against individuals who falsely claimed benefits under Pandemic Unemployment Assistance (PUA), Federal Pandemic Unemployment Compensation (FPUC), or Mixed Earner Unemployment Compensation (MEUC). The law applies only to fraud committed during these specific pandemic-era programs and does not revive cases where the original statute of limitations had already expired before this bill passed. This change gives authorities more time to pursue fraud cases without altering the programs' core eligibility rules.

Passed Mar 13, 2025 1 co-sponsor
Co-sponsor HR 2048
In committee · Indiana House · Co-sponsor
Metastatic Breast Cancer Access to Care Act

Metastatic Breast Cancer Access to Care Act This bill expedites payment of Social Security Disability Insurance (SSDI) benefits and eligibility for Medicare coverage for those with metastatic breast cancer (i.e., breast cancer that has spread to other sites in the body). Specifically, the bill eliminates the 5-month waiting period for SSDI benefits and the subsequent 24-month waiting period for Medicare coverage for individuals with metastatic breast cancer. Under current law, individuals generally must wait 5 months after the onset of disability to begin receiving SSDI benefits and an additional 24 months to become eligible for Medicare.

In committee Mar 11, 2025 1 co-sponsor
Co-sponsor HR 2028
In committee · Indiana House · Co-sponsor
REDI Act

Resident Education Deferred Interest Act or the REDI Act This bill allows borrowers in medical or dental internships or residency programs to defer student loan payments until the completion of their programs.

In committee Mar 11, 2025 1 co-sponsor
Co-sponsor HR 2089
In committee · Indiana House · Co-sponsor
Generating Retirement Ownership through Long-Term Holding

Maddy summaryThis bill changes how individual investors in mutual funds (regulated investment companies) are taxed on certain dividends. It allows investors to defer paying tax on capital gain dividends that are automatically reinvested in additional fund shares through a dividend reinvestment plan. The deferred tax is recognized later when the investor sells shares or upon their death. It also establishes that shares acquired through this reinvestment are treated as held for over one year from the start, potentially qualifying for long-term capital gains rates. The rule applies only to individual investors (not estates, trusts, or dependents claimed by others).

In committee Mar 11, 2025 1 co-sponsor
Co-sponsor HR 1990
In committee · Indiana House · Co-sponsor
American Innovation and R&D Competitiveness Act of 2025

Maddy summaryHR 1990, the American Innovation and R&D Competitiveness Act of 2025, amends tax rules for businesses to make research and development (R&D) costs more flexible. It allows companies to deduct R&D expenses immediately as business costs (instead of capitalizing them) or to spread these costs over a minimum 60-month period. The bill clarifies which R&D expenses qualify, excludes land improvements and mineral exploration costs, and ensures companies can claim R&D tax credits without conflict with expense treatment. This directly affects businesses that conduct R&D, changing how they account for these costs on tax returns starting for 2022 taxable years.

In committee Mar 10, 2025 1 co-sponsor
Showing 141 to 150 of 718 bills
Previous 1 … 14 15 16 … 72 Next