

Maddy summaryThis resolution expresses the House of Representatives' support for blockchain technology and digital assets. It states the House believes the U.S. should prioritize understanding blockchain's potential, foster innovation to improve financial systems, avoid losing digital asset development to less regulated countries, and create tailored regulations that maintain investor protections while acknowledging the unique benefits of the technology. As a non-binding resolution, it does not change laws or directly affect specific groups, but reflects congressional sentiment toward the digital asset industry.
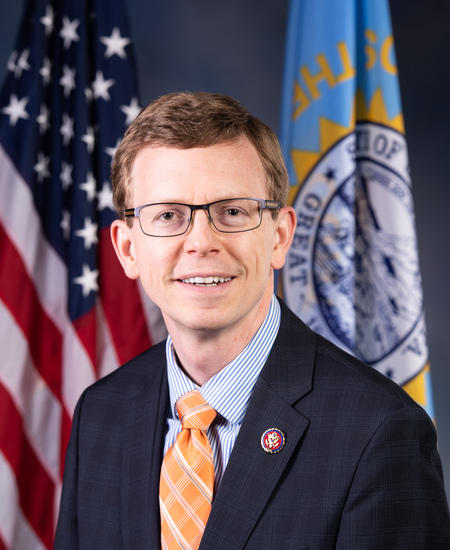
Rep. Dusty Johnson
Sponsored bills
Fair Access to Banking Act This bill places restrictions on certain banks, credit unions, and payment card networks if they refuse to do business with a person who complies with the law. Restrictions include prohibiting the use of electronic funds transfer systems and lending programs, termination of an institution's depository insurance, and specified civil penalties. Banks and other specified financial institutions are allowed to deny financial services to a person only if the denial is justified by a documented failure of that person to meet quantitative, impartial, risk-based standards established in advance by the institution. This justification may not be based upon reputational risks to the institution. The bill establishes the right for a person to bring a civil action for a violation of this bill.
Maddy summaryHR 1007, the Antisemitism Awareness Act of 2025, clarifies how the Department of Education enforces Title VI of the Civil Rights Act of 1964 to address discrimination against Jewish individuals. It requires the Department to consider the International Holocaust Remembrance Alliance (IHRA) definition of antisemitism when investigating complaints involving discrimination based on actual or perceived Jewish ancestry or ethnic characteristics. This affects Jewish students and communities in K-12 schools and colleges receiving federal funding, as it ensures antisemitism is assessed under existing civil rights protections. The bill does not create new laws but specifies that the IHRA definition - already used by the Department since 2018 - must be applied in Title VI enforcement cases.
Maddy summaryThis bill limits the Secretary of Education's authority to create new student loan regulations or executive actions that could increase taxpayer costs. Specifically, it requires the Secretary to determine if a proposed rule would raise subsidy costs before moving forward; if it would, the rule cannot proceed. The restriction applies to any "economically significant" rule (costing $100 million+ annually or materially affecting the economy, jobs, or other key areas). The bill directly affects the Department of Education's regulatory process, not student loan borrowers or lenders.
Medicare Patient Access and Practice Stabilization Act of 2025 This bill increases certain payment adjustments under the Medicare physician fee schedule for services furnished between April 1, 2025, and January 1, 2026.
Maddy summaryHCONRES 4 is a symbolic resolution expressing Congress's support for tax-exempt fraternal benefit societies (like mutual aid organizations). It recognizes these groups, which have over 7 million members nationwide, as historically and currently providing critical community benefits - including life/health insurance, charitable work, and volunteer services - valued at over $3.8 billion annually. The resolution affirms that their tax-exempt status under Section 501(c)(8) of the Internal Revenue Code remains beneficial and should continue to be promoted. This is a non-binding expression of congressional sentiment, not a policy change.
Maddy summaryThis bill prohibits federal funds from being used to cover gender transition procedures for individuals under 18, including puberty blockers, hormone therapies (at higher-than-normal doses), and surgeries like hysterectomies or mastectomies. It defines "sex" biologically as male or female and exempts certain medical treatments, such as puberty suppression for precocious puberty or care for genetic disorders of sex development. The policy directly affects minors receiving federally funded healthcare (e.g., Medicaid), restricting coverage for most gender-affirming care. Key mechanisms include funding restrictions and specific medical exceptions, though it does not ban private insurance or out-of-pocket payments.
Life at Conception Act This bill declares that the right to life guaranteed by the Constitution is vested in each human being at all stages of life, including the moment of fertilization, cloning, or other moment at which an individual comes into being. Nothing in this bill shall be construed to authorize the prosecution of any woman for the death of her unborn child.
Maddy summaryHR 21, the Born-Alive Abortion Survivors Protection Act, requires medical staff at abortion facilities to provide the same immediate care and hospital admission to any infant born alive during an abortion as they would for any newborn. It mandates reporting failures to provide this care to law enforcement and imposes penalties of up to 5 years in prison for violations, with harsher penalties for intentional killing. The bill also allows women who undergo abortions to sue for civil damages, including triple the abortion cost, and provides for attorney fees. It defines "abortion" to exclude procedures performed after viability to preserve a live birth. This law directly affects healthcare providers at abortion facilities and creates new federal legal obligations for them.
Maddy summaryHR 703, the Main Street Tax Certainty Act, makes a key tax deduction permanent for small business owners. It removes the temporary sunset provision (subsection (i)) from Section 199A of the tax code, ensuring the qualified business income deduction remains available for eligible small businesses. This change directly affects pass-through business owners (like S-corps, partnerships, and sole proprietorships) who currently qualify for this deduction. The permanent change takes effect for tax years starting after December 31, 2025.