

Maddy summaryHJRES 30 is a congressional resolution seeking to block an Environmental Protection Agency (EPA) rule that implements the American Innovation and Manufacturing (AIM) Act of 2020. The resolution targets the EPA's specific rule (published in the Federal Register on October 11, 2024) which establishes a phasedown schedule for hydrofluorocarbons (HFCs) used in refrigeration, air conditioning, and other applications. If approved, this resolution would formally disapprove the EPA rule under the Congressional Review Act, preventing it from taking effect and halting the agency's implementation of the HFC phase-down. The resolution directly affects the EPA’s regulatory authority and the timeline for reducing HFC use, which impacts industries relying on these chemicals.
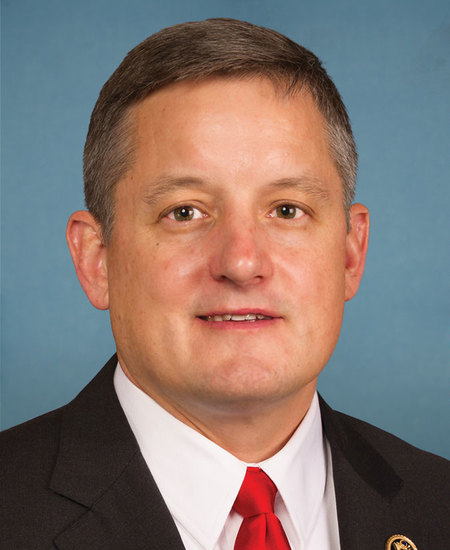
Rep. Bruce Westerman
Sponsored bills
Life at Conception Act This bill declares that the right to life guaranteed by the Constitution is vested in each human being at all stages of life, including the moment of fertilization, cloning, or other moment at which an individual comes into being. Nothing in this bill shall be construed to authorize the prosecution of any woman for the death of her unborn child.
Maddy summaryHR 21, the Born-Alive Abortion Survivors Protection Act, requires medical staff at abortion facilities to provide the same immediate care and hospital admission to any infant born alive during an abortion as they would for any newborn. It mandates reporting failures to provide this care to law enforcement and imposes penalties of up to 5 years in prison for violations, with harsher penalties for intentional killing. The bill also allows women who undergo abortions to sue for civil damages, including triple the abortion cost, and provides for attorney fees. It defines "abortion" to exclude procedures performed after viability to preserve a live birth. This law directly affects healthcare providers at abortion facilities and creates new federal legal obligations for them.
Maddy summaryHR 703, the Main Street Tax Certainty Act, makes a key tax deduction permanent for small business owners. It removes the temporary sunset provision (subsection (i)) from Section 199A of the tax code, ensuring the qualified business income deduction remains available for eligible small businesses. This change directly affects pass-through business owners (like S-corps, partnerships, and sole proprietorships) who currently qualify for this deduction. The permanent change takes effect for tax years starting after December 31, 2025.
This bill increases the annual limit on the tax credit for qualified railroad track maintenance expenses (also referred to as the short line railroad tax credit) and expands eligibility for claiming the credit. Under current law, the tax credit is limited each tax year to $3,500 multiplied by the sum of the number of miles of railroad track owned or leased by the taxpayer (miles owned or leased) and the number of railroad track miles assigned to the taxpayer by a Class II or III railroad (miles assigned). This bill increases the annual limit to $6,100 multiplied by the sum of miles owned or leased and miles assigned. The $6,100 amount used in the calculation of the tax credit limit is adjusted for inflation for tax years beginning after 2025. The bill also expands eligibility for the tax credit to include gross expenses for maintaining railroad tracks owned or leased as of January 1, 2024. Under current law, the tax credit is limited to gross expenses for maintaining railroad tracks owned or leased as of January 1, 2015.
Maddy summaryHR 431, the "Pony Up Act," requires the United States Postal Service (USPS) to reimburse citizens for fees or penalties incurred due to late delivery of their bills or payment notices. If a bill notice is delivered late (defined as USPS receiving mail more than 12 days before the due date but delivering it less than 6 days before the due date), USPS must pay the full amount of late fees charged to the citizen. Citizens can apply for reimbursement online, by mail, or in person at post offices, with appeals available to a Judicial Officer if denied. The bill also mandates annual USPS reports to Congress on mail delivery delays, including data on different mail classes and presorting effects. This directly affects citizens who face late fees due to USPS delivery errors.
Maddy summaryHR 404, the "Hearing Protection Act," reclassifies firearm silencers (devices that reduce gunfire noise) as firearms for federal tax and regulatory purposes. It imposes a 10% federal tax on silencers, requires the destruction of all existing federal silencer registration records within one year, and preempts state laws that tax or regulate silencers. The bill clarifies that silencers are treated as firearms under federal law, including for licensing and marking requirements, and defines "firearm silencer" to include specific components. Note: The bill’s title is misleading - it addresses firearm silencer regulation, not hearing protection for people.
Maddy summaryThis bill prohibits federal funding under Title X (which supports family planning services) for clinics or organizations that perform or fund abortions, except in cases of rape, incest, or when a physician certifies a life-threatening condition. It requires grantees to certify compliance annually and mandates detailed annual reports to Congress on exceptions, including abortion counts by circumstance. The law directly affects Title X-funded providers who currently offer abortion services, potentially forcing them to stop providing abortions or lose federal funding. Key mechanisms include the certification requirement, exception criteria, and the new reporting obligations for the Secretary of Health and Human Services.
Maddy summaryThis bill amends the tax code to create a special rule for deducting losses of uncut timber (timber not yet cut for sale) from disasters like fires, storms, pests, or drought. It requires taxpayers to base deductions on the timber's pre-loss appraised value minus salvage value, using a certified appraiser's assessment within one year. Crucially, taxpayers must reforest the affected area with hardwoods or softwoods within five years to keep the tax benefit; failure to reforest results in recapturing the deduction. The rule applies only to timber held for sale in an active business, excluding passive activities. This changes how businesses can claim tax deductions after timber losses while linking the benefit to reforestation efforts.
Maddy summaryThe D.C. Robert F. Kennedy Memorial Stadium Campus Revitalization Act transfers administrative control of the 174-acre Robert F. Kennedy Memorial Stadium Campus from the federal government to the District of Columbia. This allows the District to develop the campus for residential, commercial, and public purposes, including designating at least 30% as "Robert F. Kennedy Memorial Park" for recreation. The District must pay all transfer and development costs, maintain public access to the Anacostia River, and follow specific environmental and development requirements. The transfer is for a minimum of 99 years, with provisions for federal reversion if the District fails to meet requirements. The bill also repeals the 1957 Stadium Act and terminates a 1988 lease agreement.