Issue · Budget & Taxes

Budget & Taxes (Business Taxes)

Every budget & taxes bill, vote, and legislator stance in Hawaii, automatically classified by Maddy, our AI policy reader.

Total bills
112
2026 Regular Session
Top supporter
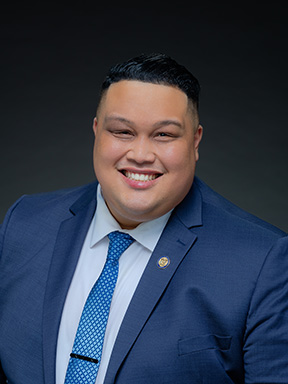
Darius Kila
100% support rate
Top opponent
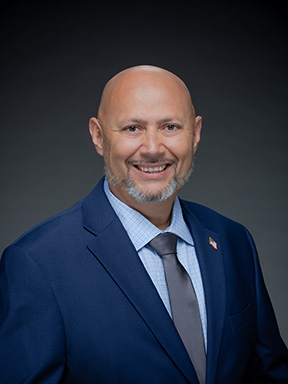
Chris Muraoka
0% support rate
Ranked legislators
4
3 support · 1 oppose
Key legislators

Who's moving business taxes in Hawaii

Legislators moving business taxes in Hawaii
Legislator Party Stance Support rate Votes
Darius Kila
Darius Kila House · District 44
D
Strong +
100% 3
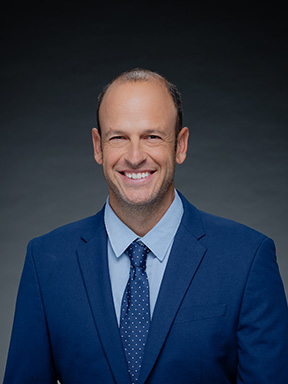
Luke Evslin
Luke Evslin House · District 16
D
Strong +
100% 3
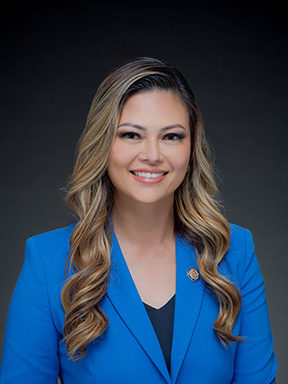
Trish La Chica
Trish La Chica House · District 37
D
Strong +
100% 3
Chris Muraoka
Chris Muraoka House · District 45
R
Strong −
0% 3
Showing 61–70 of 112 bills

All budget & taxes bills

passed · Hawaii · Senate Feb 20, 2026

SB 3046: RELATING TO INCOME TAX CREDIT.

Establishes a nonrefundable Workforce Builder Tax Credit for employers who employ qualified interns and apprentices, to be applied to taxable years beginning after 12/31/2026. Requires a report to the Legislature. Appropriates funds. Effective 1/1/2077. (SD1)
in committee · Hawaii · Senate Feb 13, 2026

SCR 12: URGING THE UNITED STATES CONGRESS TO PROVIDE OWNER-OCCUPANTS WITH COMPARABLY EQUIVALENT TAX DEDUCTIONS AFFORDED TO BUSINESS ENTITIES FOR EXPENSES RELATED TO PROPERTY OWNERSHIP.

This Hawaii Senate resolution (SCR 12) urges the U.S. Congress to change federal tax law so that homeowners (owner-occupants) can deduct the same property-related expenses as business property owners. Currently, businesses like real estate investment trusts (REITs) can deduct costs such as depreciation, property taxes, insurance, maintenance, and utilities, but homeowners are limited to deducting only mortgage interest. The resolution states this disparity creates an unfair tax disadvantage for Hawaii homeowners, hindering affordability as housing costs are a major barrier. It does not create new law but formally requests Congress to address this imbalance.
in committee · Hawaii · Senate Feb 2, 2026

SB 3197: RELATING TO TAXATION.

Exempts the sale of groceries and nonprescription drugs from the general excise tax. Removes the state income tax on unemployment compensation benefits. Doubles the standard deduction for individuals earning less than $100,000 and joint returns earning less than $200,000. Repeals the incremental increases on standard income tax deduction amounts. Increases the minimum income threshold and exemption amount for the low-income household renters' income tax credit. Removes the tax liability for the first $100,000 of individual income earned.
passed · Hawaii · Senate Feb 20, 2026

SB 2884: RELATING TO TAXATION.

Establishes a nonrefundable individual income tax credit for a certain percentage of expenses paid to retrofit a residence with wind resistive devices or to purchase, install, or construct, a hurricane shelter on the taxpayer's property. Reduces the general excise tax rate on the gross proceeds or income from the sale of a concrete high-rise certified hurricane-resistant residential project or certain hurricane-resistant components of the project. Applies to taxable years beginning after 12/31/2026. Sunsets 12/31/2030. Effective 7/1/2050. (SD1)
passed · Hawaii · House Dec 8, 2025

HB 1077: RELATING TO ECONOMIC DEVELOPMENT.

Increases the transient accommodations tax and allocates a portion of the tax to the general fund for projects that address climate change impacts and advance economic development and revitalization. Effective 7/1/3000. (HD2)
Sub-Topics Business Taxes State Budget Tax Incentives Climate Change Tags Economic Development
in committee · Hawaii · Senate Jan 28, 2026

SB 2562: RELATING TO THE RENTAL MOTOR VEHICLE SURCHARGE TAX.

SB 2562 requires rental companies to prorate the surcharge tax (an additional fee on vehicle rentals) when a customer rents a vehicle for fewer than six hours in a single day. This change directly affects short-term renters (e.g., those using a car for a few hours for errands or a quick trip) and the rental companies that collect the tax. Instead of charging the full daily surcharge for partial-day rentals, the tax would be calculated based on the actual rental duration. The bill aims to reduce the tax burden for brief rental periods while maintaining the tax structure for longer rentals.
passed · Hawaii · House Mar 10, 2026

HB 1813: RELATING TO TAXATION.

HB 1813 amends and repeals specific exemptions within the state's general excise tax and use tax laws. This bill changes how certain tax exemptions apply, potentially affecting businesses and individuals who currently qualify for those exemptions. The legislation does not create new taxes or directly fund programs, but alters existing tax rules by removing or modifying eligibility criteria for exemptions. As the bill is very recent (introduced January 22, 2026), specific exemptions impacted or affected entities are not detailed in the provided context.
in committee · Hawaii · House Feb 2, 2026

HB 2526: RELATING TO TAXATION.

Establishes a nonrefundable individual income tax credit for a certain percentage of expenses paid to retrofit a residence with wind resistive devices or to purchase, install, or construct, a hurricane shelter on the taxpayer's property. Reduces the general excise tax rate on the gross proceeds or income from the sale of a concrete certified hurricane-resistant residential project or certain hurricane-resistant components of a high-rise condominium. Applies to taxable years beginning after 12/31/2026. Sunsets 12/31/2030.
in committee · Hawaii · Senate Jan 30, 2026

SB 2792: RELATING TO GENERAL EXCISE TAX EXEMPTIONS.

Establishes a general excise tax exemption for the gross proceeds or income from the sale of groceries that are eligible under the Supplemental Nutrition Assistance Program (SNAP), regardless of the means of purchase or the SNAP eligibility of the purchaser. Establishes a general excise tax exemption for the gross proceeds or income from the sale of nonprescription drugs.
in committee · Hawaii · House Dec 8, 2025

HB 1498: RELATING TO TAXATION.

Increases the motion picture, digital media, and film production income tax credit for qualified productions that utilize qualified production facilities located within the State. Changes the cap amount and aggregate cap amount of the motion picture, digital media, and film production income tax credit to unspecified amounts. Imposes the manufacturing GET rate on motion picture, digital media, and film productions and repeals the provision in the definition of "qualified production costs" that applied the term to mean costs incurred that are subject to the highest GET rate. Exempts from the GET amounts received by a motion picture project employer from a client equal to amounts that are disbursed by the motion picture project employer for employee wages, salaries, payroll taxes, insurance premiums, and employment benefits and payments to loan-out companies. (HD1)
Showing 61 to 70 of 112 bills
Previous 1 6 7 8 12 Next