

Maddy summaryThe ACE Act (HR 750) expands 529 education savings plans to cover K-12 expenses, allowing families to use these accounts for tuition, curriculum materials, books, online learning, approved tutoring, standardized tests, and educational therapies for students with disabilities. It doubles the annual distribution limit from $10,000 to $20,000 for elementary and secondary expenses and increases gift tax exclusions for 529 contributions by up to $20,000 per year. The bill also requires states to implement school choice programs (like vouchers or education savings accounts) to qualify for tax-exempt school bonds, with specific eligibility thresholds for states. This directly affects families using 529 plans for K-12 education, homeschoolers, and states seeking tax-exempt bond funding for schools.
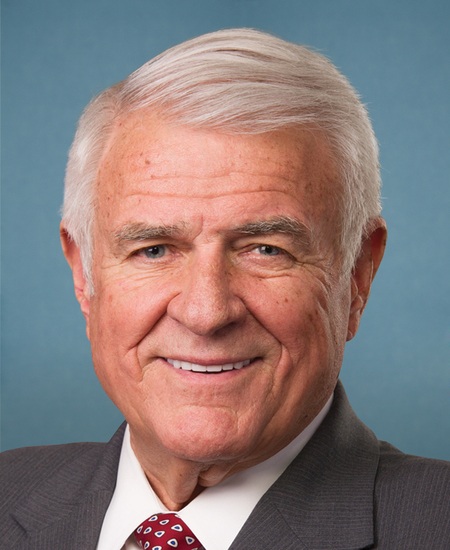
Rep. John R. Carter
Sponsored bills
Maddy summaryHR 723, the Protect American Election Administration Act of 2025, prohibits states from accepting or using funds, property, or services from private entities for administering federal elections. This directly affects state election offices, which would no longer be allowed to take private donations for activities like voter education, outreach, or registration. The bill includes an exception allowing states to accept private donations of physical space for polling places or early voting sites. It amends the Help America Vote Act of 2002 to add this prohibition, effective for federal elections after the law's enactment.
Life at Conception Act This bill declares that the right to life guaranteed by the Constitution is vested in each human being at all stages of life, including the moment of fertilization, cloning, or other moment at which an individual comes into being. Nothing in this bill shall be construed to authorize the prosecution of any woman for the death of her unborn child.
Maddy summaryHR 21, the Born-Alive Abortion Survivors Protection Act, requires medical staff at abortion facilities to provide the same immediate care and hospital admission to any infant born alive during an abortion as they would for any newborn. It mandates reporting failures to provide this care to law enforcement and imposes penalties of up to 5 years in prison for violations, with harsher penalties for intentional killing. The bill also allows women who undergo abortions to sue for civil damages, including triple the abortion cost, and provides for attorney fees. It defines "abortion" to exclude procedures performed after viability to preserve a live birth. This law directly affects healthcare providers at abortion facilities and creates new federal legal obligations for them.
Maddy summaryHR 662 amends the tax code to change how oil and gas companies calculate taxable income related to intangible drilling and development costs. It allows companies to disregard certain depreciation and depletion expenses recorded on their financial statements when computing taxable income, effectively reducing their tax burden on these specific costs. The bill directly affects oil and gas producers who use intangible drilling costs in their operations. The changes apply to taxable years beginning after December 31, 2025. This is a tax code adjustment, not a direct policy change for energy production.
Maddy summaryHR 7 prohibits federal funds from being used for abortions or health insurance plans covering abortion, with exceptions for pregnancies resulting from rape, incest, or when a woman's life is endangered. It blocks federal premium tax credits under the Affordable Care Act for health plans covering abortion (except in specified cases) and requires clear disclosure of abortion coverage and related surcharges in plan materials. The bill allows individuals or employers to purchase separate abortion coverage using non-federal funds, such as out-of-pocket payments, without affecting federal subsidies. It directly affects federal health programs, ACA marketplace plans, and health insurance issuers offering coverage that includes abortion services.
Maddy summaryThis bill amends U.S. immigration law to deny entry to noncitizens convicted of or admitting to certain violent crimes, and to make them deportable. It directly affects noncitizens who have been convicted of or admitted to sex offenses, domestic violence, stalking, child abuse/neglect, or violating protection orders involving threats of violence. Key provisions add these offenses as grounds for denying entry (inadmissibility) under Section 212(a)(2) and as grounds for deportation (deportability) under Section 237(a)(2). The law specifies that domestic violence and protection order violations are included regardless of whether the jurisdiction received specific federal grant funding.
Maddy summaryHRES 50 is a symbolic resolution, not a bill with policy changes. It declares that states bordering Mexico have the constitutional right under Article I, Section 10 to defend against "paramilitary, narco-terrorist cartels" and criminal actors at the southern border. The resolution states that states like Texas, Arizona, New Mexico, and California were "invaded" or faced "imminent danger" from these groups from 2021-2024, and that the federal government failed to protect them. It makes no new laws or allocate funds - only asserts a constitutional interpretation for states to act unilaterally. (Note: This is a procedural resolution; no concrete policy change is enacted.)
Chiropractic Medicare Coverage Modernization Act of 2025 This bill expands Medicare coverage of chiropractic services to include all services provided by chiropractors, rather than only subluxation corrections through manual manipulation of the spine.
This bill increases the annual limit on the tax credit for qualified railroad track maintenance expenses (also referred to as the short line railroad tax credit) and expands eligibility for claiming the credit. Under current law, the tax credit is limited each tax year to $3,500 multiplied by the sum of the number of miles of railroad track owned or leased by the taxpayer (miles owned or leased) and the number of railroad track miles assigned to the taxpayer by a Class II or III railroad (miles assigned). This bill increases the annual limit to $6,100 multiplied by the sum of miles owned or leased and miles assigned. The $6,100 amount used in the calculation of the tax credit limit is adjusted for inflation for tax years beginning after 2025. The bill also expands eligibility for the tax credit to include gross expenses for maintaining railroad tracks owned or leased as of January 1, 2024. Under current law, the tax credit is limited to gross expenses for maintaining railroad tracks owned or leased as of January 1, 2015.