

Maddy summarySB 79 prohibits state agencies from charging payors a service fee when payments are made using credit cards, charge cards, or debit cards. This directly affects individuals and businesses paying state fees (like licenses or permits) who would otherwise face extra charges for using card payments. The bill amends statutes to explicitly ban these fees, requiring agencies to accept card payments without additional costs. It does not change how payments are processed, only eliminates the fee for specific payment methods.
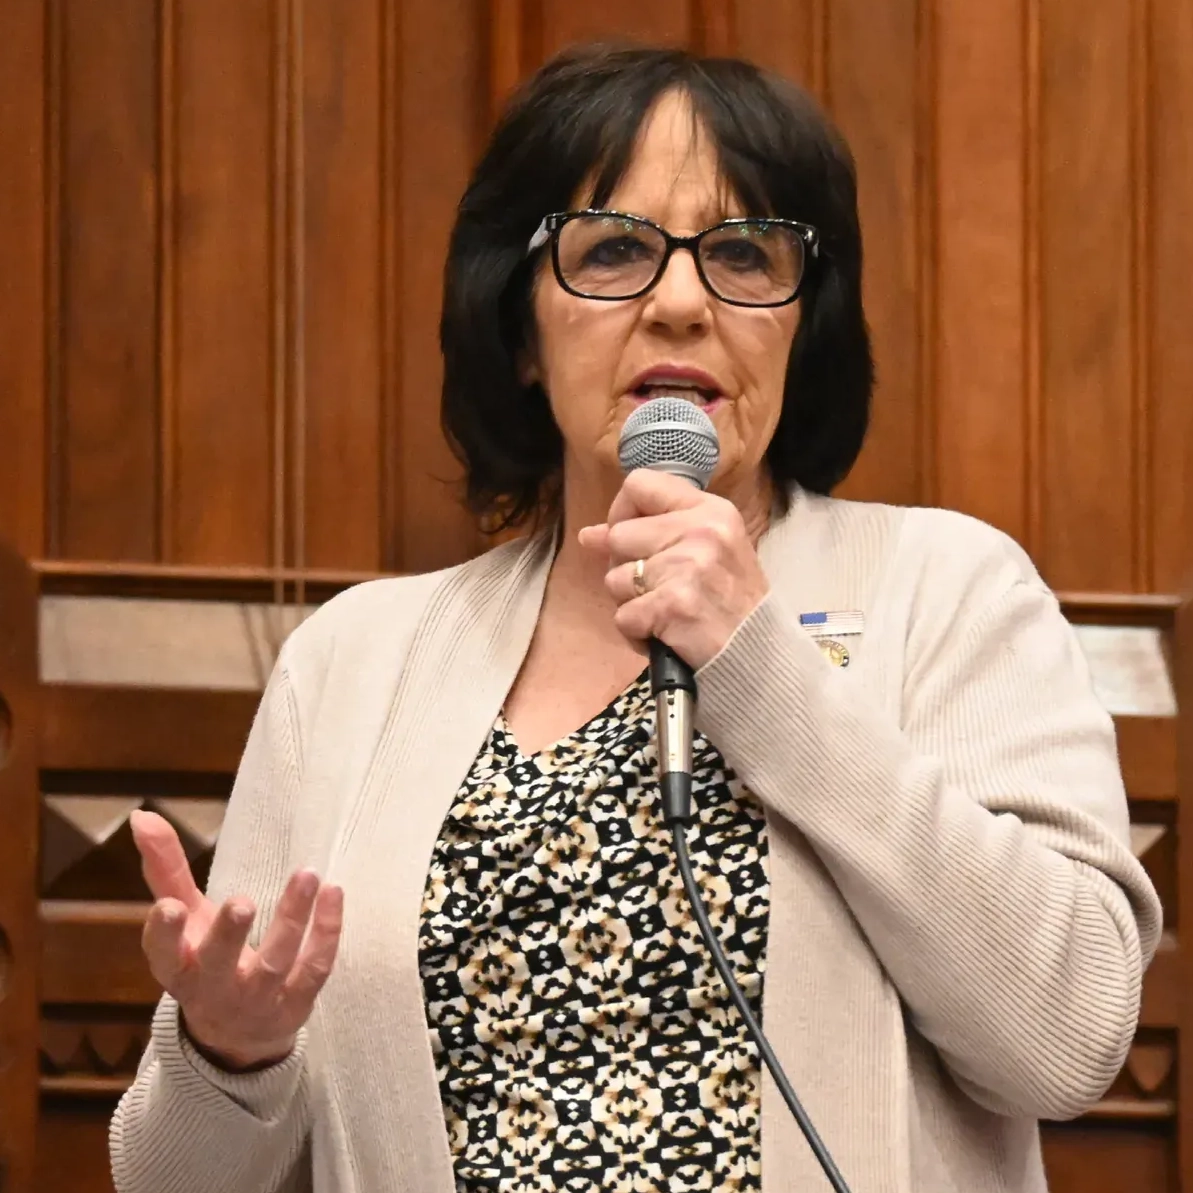
Rep. Gale Mastrofrancesco
Sponsored bills
Maddy summarySB 69 would eliminate Connecticut's Earned Income Tax Credit (EITC) by repealing the statute (section 12-704e) that created the program. This change would directly affect low-to-moderate income working individuals and families, particularly those with children, who currently qualify for the credit. The bill's key mechanism is the simple repeal of the existing law, removing the eligibility and calculation rules for the credit. As a result, qualifying residents would no longer receive this refundable tax credit, reducing their annual tax refund or increasing their tax liability. The bill does not create new provisions but removes the current program.
Maddy summarySB 28 requires the state budget for fiscal year 2027 to appropriate funds directly from the General Fund to support nine regional fire training schools, rather than using specific taxes or fees like insurance premium surcharges. This bill directly affects the nine regional fire training schools by securing their funding through standard state budget appropriations. The key provision mandates that funding must come from the General Fund in the state budget, eliminating reliance on targeted revenue sources. The bill does not change the schools' operations but specifies how their funding will be allocated. This is a procedural budgetary measure with no new policy requirements.
Maddy summarySB 70 would exempt all Social Security benefits and pension or annuity income from state personal income tax for every taxpayer. This policy change directly affects residents receiving these income types, removing them from the taxable base. The bill amends Section 12-701 of the general statutes to implement this universal exemption. It creates a concrete tax relief measure without altering other income tax provisions.
Maddy summaryHB 5006 eliminates a 1% sales and use tax on meals sold by restaurants, caterers, and grocery stores. The bill directly affects these businesses by removing an additional tax on food sales, reducing their operational costs. Key provision: it amends tax law to remove the specific 1% surcharge applied to meals at these establishments. The purpose is to simplify the tax structure for food service providers without changing general sales tax rates. This is a direct policy change affecting food retailers and their customers through lower prices.
Maddy summaryHB 5028 removes the "Combined Public Benefits Charge" from electricity bills for residential and business customers of electric distribution companies. This bill directly affects all end-use electricity customers in the state by eliminating this specific fee from their monthly bills. The key mechanism shifts the funding source for these public benefits programs from customer bills to the state General Fund. The bill does not change existing public benefits programs but changes how their costs are paid. This is a direct billing change with no impact on program eligibility or service levels.
Maddy summaryHB 5008 establishes a $2,080 tax credit per full-time equivalent employee for small businesses meeting the U.S. Small Business Administration's definition (typically businesses with fewer than 500 employees). This credit would directly reduce the state tax liability for qualifying small businesses, providing a concrete financial incentive tied to employee count. The bill amends state tax law to implement this credit, which applies to businesses that meet federal SBA criteria. This policy change specifically targets small business employment costs without altering broader tax structures.
Maddy summaryHB 6932 (now Public Act 25-144) creates a State Interpreting Standards Board to establish certification and training requirements for interpreters providing services in state agencies. The board will set rules for language access, ensuring interpreters meet specific qualifications when working with limited English proficiency individuals. This law directly affects professional interpreters and state agencies that rely on interpretation services. The bill became effective upon the governor's signature on July 1, 2025.
Maddy summaryThis bill (HB 6438, now Public Act 25-95) creates multiple symbolic honors to recognize Connecticut military members and veterans. It authorizes specific non-monetary measures, such as placing plaques at state facilities, designating commemorative events, and establishing a formal process for honoring service. The law directly affects active-duty service members, veterans, and their families within Connecticut by providing official state-level recognition of their military contributions. As a commemorative measure, it does not alter benefits, funding, or existing policies but affirms the state's appreciation for military service.
Maddy summaryHB 7081 allows Connecticut-licensed marriage and family therapists to practice in other states without obtaining new licenses. The bill requires Connecticut to recognize licenses from states with comparable standards, eliminating redundant exams and paperwork for therapists moving across state lines. This directly affects therapists seeking to relocate, serve clients in multiple states, or expand their practice without repeating licensing steps. The law streamlines interstate practice by aligning Connecticut’s requirements with other states’ standards.