

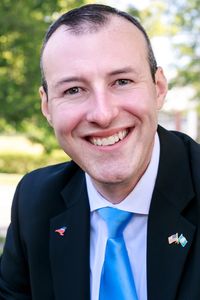
Photo of Nick Gauthier
D Connecticut House · District 38 On the 2026 ballot

Rep. Nick Gauthier

Compare
Total votes
754
all sessions
Attendance
100%
of floor votes
Higher than 79% of chamber peers
With party
98%
of cast votes
Near the chamber average
Bipartisan score
1%
crosses aisle rarely
Near the chamber average
Sponsored
259
bills & resolutions
Higher than 98% of chamber peers
Committees
3
assignments
259 bills and resolutions

Sponsored bills

Total
259
Primary
259
Co-sponsor
0
This page
259
matching current filters
Primary SB 114
In committee · Connecticut Senate · Lead sponsor
AN ACT ELIMINATING THE QUALIFYING INCOME THRESHOLDS FOR THE PERSONAL INCOME TAX DEDUCTIONS FOR SOCIAL SECURITY BENEFITS.

Maddy summarySB 114 eliminates income limits that currently restrict who can deduct Social Security benefits from their state personal income tax. It directly affects all Social Security benefit recipients in the state who pay income tax, removing the previous requirement that their total income must fall below specific thresholds to qualify for the deduction. The bill amends Section 12-701 of the general statutes to remove these qualifying income thresholds entirely. This change means anyone receiving Social Security benefits would automatically qualify for the tax deduction regardless of their total income level. The policy change simplifies the deduction process for eligible taxpayers without altering the deduction amount itself.

In committee Feb 20, 2026 0 co-sponsors
Primary SB 104
In committee · Connecticut Senate · Lead sponsor
AN ACT ESTABLISHING A CAPITAL GAINS SURCHARGE.

Maddy summarySB 104 would impose a 1.75% surcharge on net gains from selling capital assets (like stocks or real estate) for Connecticut taxpayers with adjusted gross income meeting the threshold for the state's highest and second-highest marginal tax brackets. It directly affects high-income earners whose income level triggers the top tax rates under current law. The surcharge applies only to capital gains, not ordinary income, and is calculated as a percentage of the net gain from qualifying sales. This is a specific tax rate change affecting a defined income group, not a broad policy overhaul.

In committee Feb 20, 2026 0 co-sponsors
Primary SB 103
In committee · Connecticut Senate · Lead sponsor
AN ACT ESTABLISHING A REFUNDABLE CHILD TAX CREDIT.

Maddy summaryThis bill establishes a refundable child tax credit for families with up to three children, starting at $150 per child in 2026 and increasing to $600 per child by 2028. It phases out for higher-income households: single filers over $100,000, heads of household over $160,000, and married couples filing jointly over $200,000 (reducing by 5% for every $1,000 over these thresholds). The credit is refundable, meaning eligible families receive it even if they owe no income tax. It directly affects low-to-moderate income families with children under age 18.

In committee Feb 20, 2026 0 co-sponsors
Primary HB 5218
In committee · Connecticut House · Lead sponsor
AN ACT CONCERNING TEACHERS.

Maddy summaryHB 5218 updates Connecticut's teacher employment contract rules, affecting all public school teachers (both tenured and non-tenured). It requires school boards to provide written notice of nonrenewal by May 1st each year for non-tenured teachers, with a 10-day window for them to request a hearing if they dispute the decision. For tenured teachers, termination must be for specific reasons (like incompetence, insubordination, or position elimination) and require written notice before a hearing, with the hearing scheduled within 15 days. The bill clarifies that non-tenured teachers cannot appeal position eliminations, and all hearings must follow strict timelines and just-cause standards.

In committee Feb 19, 2026 0 co-sponsors
Primary SB 226
In committee · Connecticut Senate · Lead sponsor
AN ACT CONCERNING VARIOUS REVISIONS RELATED TO ELECTION PROCESSES.

Maddy summarySB 226 revises early voting rules for all elections in Connecticut, affecting voters who wish to cast ballots before election day. It establishes specific early voting periods: 15 days before regular elections (ending two days prior), 8 days before non-presidential primaries, and 5 days before special elections or presidential primaries (adjusted for holidays). The bill requires unaffiliated voters or new voters to register with a political party by noon the day before early voting at primaries. Additionally, it mandates that early voting locations must be certified to the Secretary of State, provide access to the state voter system, and remain consistent throughout the early voting period. These changes take effect July 1, 2026.

In committee Feb 19, 2026 0 co-sponsors
Primary SB 162
In committee · Connecticut Senate · Lead sponsor
AN ACT AUTHORIZING BONDS OF THE STATE TO THE SOUTHEASTERN CONNECTICUT WATER AUTHORITY TO UPGRADE WATERLINES AND CONNECTIONS IN THE TOWN OF MONTVILLE.

Maddy summarySB 162 authorizes the state to issue up to $14 million in bonds to fund waterline upgrades in Montville Manor, Montville. The funds will be provided as a grant-in-aid to the Southeastern Connecticut Water Authority through the Department of Economic and Community Development. This bill directly affects residents of Montville Manor by enabling critical infrastructure improvements to waterlines and connections. The key mechanism is state bond financing, with the grant specifically targeting upgrades in that specific neighborhood. The bill does not alter existing water service regulations or impose new requirements on residents.

In committee Feb 11, 2026 0 co-sponsors
Primary HB 5193
In committee · Connecticut House · Lead sponsor
AN ACT AUTHORIZING BONDS OF THE STATE FOR CAPITAL IMPROVEMENTS TO CAMP OAKDALE IN THE TOWN OF MONTVILLE.

Maddy summaryHB 5193 authorizes the state to issue up to $3.8 million in bonds to fund capital improvements at Camp Oakdale in Montville. The funds will be provided as a grant to Montville through the Department of Economic and Community Development for specific facility upgrades at the camp. This bill directly affects Montville residents and Camp Oakdale users by enabling physical improvements to the local facility. The key mechanism is the state bond authorization, with funds flowing to the town for designated capital projects only.

In committee Feb 11, 2026 0 co-sponsors
Primary SB 175
In committee · Connecticut Senate · Lead sponsor
AN ACT AUTHORIZING BONDS OF THE STATE FOR STUDENT HOUSING AT THE AVERY POINT CAMPUS OF THE UNIVERSITY OF CONNECTICUT.

Maddy summarySB 175 authorizes the state to issue up to $40 million in bonds specifically for designing and building new student housing at the University of Connecticut's Avery Point Campus. This funding directly supports UConn students by expanding housing capacity at that campus location. The bill enables the State Bond Commission to issue these bonds, with proceeds dedicated solely to constructing new on-campus housing facilities.

In committee Feb 11, 2026 0 co-sponsors
Primary HB 5186
In committee · Connecticut House · Lead sponsor
AN ACT CONCERNING THE AFFECTED BUSINESS ENTITY TAX AND THE CREDIT RELATED THERETO AND ESTABLISHING A SURCHARGE ON THE AMOUNT OF FEDERAL QUALIFIED BUSINESS INCOME DEDUCTIONS CLAIMED BY CERTAIN FILERS.

Maddy summaryHB 5186 adjusts Connecticut's affected business entity tax and related credits for businesses claiming federal qualified business income deductions. It adds a 1% surcharge on the business entity tax and a 10% surcharge on federal deductions claimed by filers in the highest tax bracket. The bill also modifies tax credits: reducing the credit to 83.6% for high-bracket filers while increasing it to 93.01% for lower-bracket filers. These changes directly impact businesses using federal pass-through income deductions, particularly those in Connecticut's top tax rate category.

In committee Feb 11, 2026 0 co-sponsors
Primary HB 5185
In committee · Connecticut House · Lead sponsor
AN ACT ESTABLISHING A CAPITAL GAINS AND DIVIDENDS SURCHARGE.

Maddy summaryHB 5185 would impose a surcharge on capital gains and dividends for Connecticut taxpayers with adjusted gross income meeting the threshold for the state's highest marginal income tax rate. It directly affects high-income earners subject to Connecticut's top tax bracket, specifically targeting net gains from selling investments and dividend income. The bill amends state tax law to add this surcharge to the existing tax calculation for qualifying taxpayers. The policy change is a direct revenue measure applying only to those already paying the highest rate on ordinary income.

In committee Feb 11, 2026 0 co-sponsors
Showing 191 to 200 of 259 bills
Previous 1 19 20 21 26 Next