

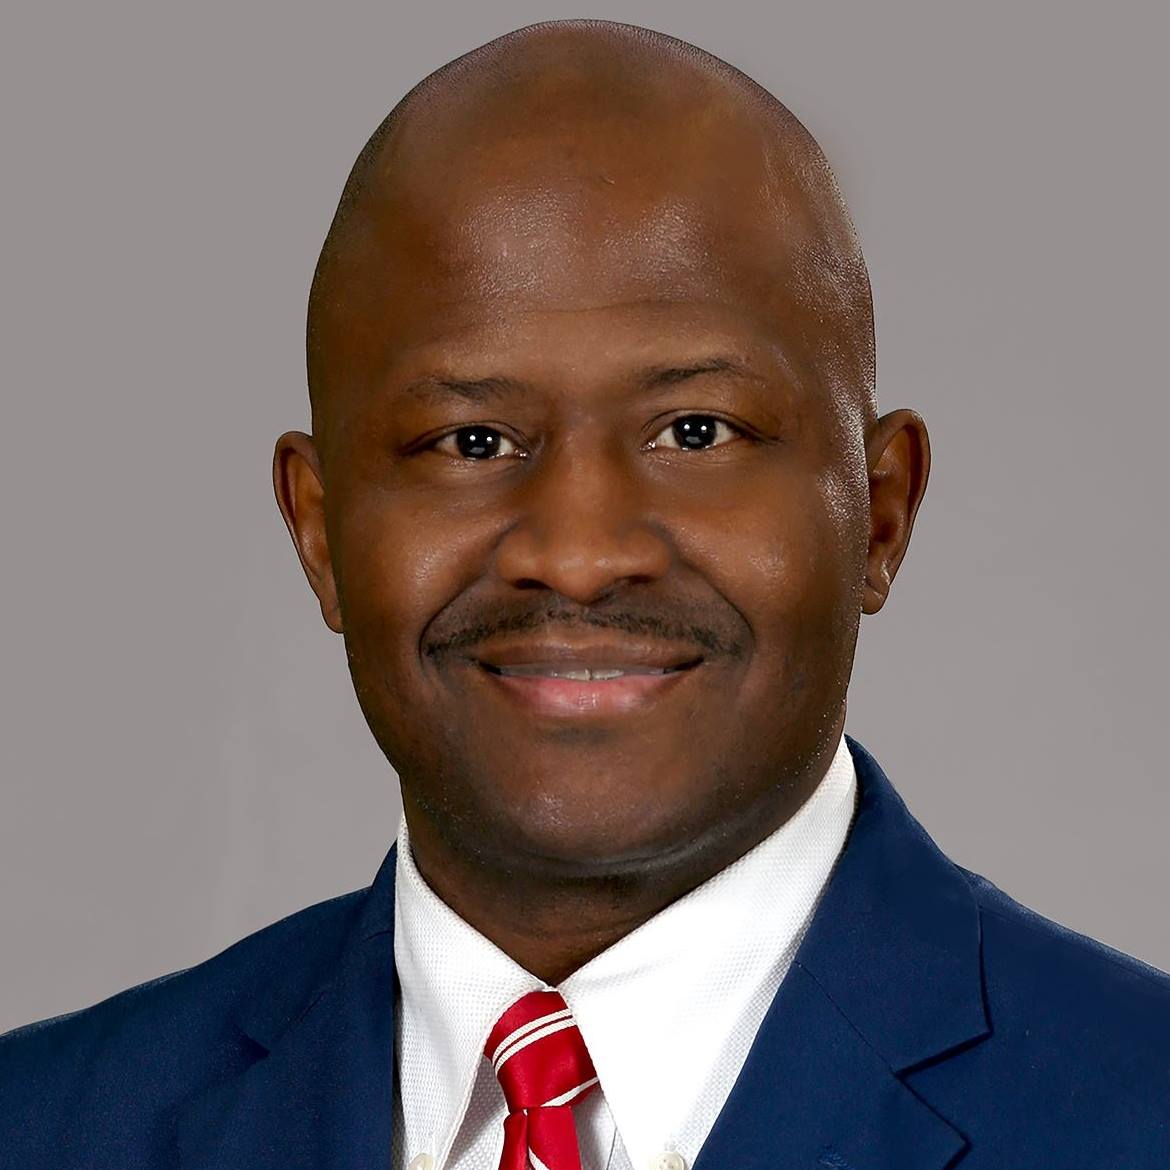
Photo of Travis Simms
D Connecticut House · District 140 On the 2026 ballot

Rep. Travis Simms

Compare
Total votes
1,069
all sessions
Attendance
87%
135 missed
Lower than 94% of chamber peers
With party
97%
of cast votes
Near the chamber average
Bipartisan score
1%
crosses aisle rarely
Near the chamber average
Sponsored
639
bills & resolutions
Higher than 85% of chamber peers
Committees
3
assignments
639 bills and resolutions

Sponsored bills

Total
639
Primary
639
Co-sponsor
0
This page
639
matching current filters
Primary SB 103
In committee · Connecticut Senate · Lead sponsor
AN ACT ESTABLISHING A REFUNDABLE CHILD TAX CREDIT.

Maddy summaryThis bill establishes a refundable child tax credit for families with up to three children, starting at $150 per child in 2026 and increasing to $600 per child by 2028. It phases out for higher-income households: single filers over $100,000, heads of household over $160,000, and married couples filing jointly over $200,000 (reducing by 5% for every $1,000 over these thresholds). The credit is refundable, meaning eligible families receive it even if they owe no income tax. It directly affects low-to-moderate income families with children under age 18.

In committee Feb 20, 2026 0 co-sponsors
Primary SB 197
In committee · Connecticut Senate · Lead sponsor
AN ACT PROVIDING A FAMILY CAREGIVER TAX CREDIT.

Maddy summarySB 197 creates a new tax credit for family caregivers who pay for the care and support of elderly relatives. It directly affects adult children or other relatives providing unpaid care to older family members. The bill provides a credit against state income tax for eligible out-of-pocket expenses related to that care, such as medical supplies or in-home assistance. This policy change offers financial relief to caregivers by reducing their state tax burden for specific caregiving costs.

In committee Feb 17, 2026 0 co-sponsors
Primary HB 5186
In committee · Connecticut House · Lead sponsor
AN ACT CONCERNING THE AFFECTED BUSINESS ENTITY TAX AND THE CREDIT RELATED THERETO AND ESTABLISHING A SURCHARGE ON THE AMOUNT OF FEDERAL QUALIFIED BUSINESS INCOME DEDUCTIONS CLAIMED BY CERTAIN FILERS.

Maddy summaryHB 5186 adjusts Connecticut's affected business entity tax and related credits for businesses claiming federal qualified business income deductions. It adds a 1% surcharge on the business entity tax and a 10% surcharge on federal deductions claimed by filers in the highest tax bracket. The bill also modifies tax credits: reducing the credit to 83.6% for high-bracket filers while increasing it to 93.01% for lower-bracket filers. These changes directly impact businesses using federal pass-through income deductions, particularly those in Connecticut's top tax rate category.

In committee Feb 11, 2026 0 co-sponsors
Primary HB 5185
In committee · Connecticut House · Lead sponsor
AN ACT ESTABLISHING A CAPITAL GAINS AND DIVIDENDS SURCHARGE.

Maddy summaryHB 5185 would impose a surcharge on capital gains and dividends for Connecticut taxpayers with adjusted gross income meeting the threshold for the state's highest marginal income tax rate. It directly affects high-income earners subject to Connecticut's top tax bracket, specifically targeting net gains from selling investments and dividend income. The bill amends state tax law to add this surcharge to the existing tax calculation for qualifying taxpayers. The policy change is a direct revenue measure applying only to those already paying the highest rate on ordinary income.

In committee Feb 11, 2026 0 co-sponsors
Primary HB 5139
In committee · Connecticut House · Lead sponsor
AN ACT ESTABLISHING AN ESTATE TAX RECAPTURE FOR CERTAIN ESTATES AND AN ALTERNATIVE MINIMUM ESTATE TAX.

Maddy summaryHB 5139 establishes two key estate tax provisions: (1) an estate tax recapture for estates exceeding $15 million in value, requiring additional tax payment if the effective rate falls below 2%, and (2) an alternative minimum estate tax to ensure the effective tax rate never drops below 2%. This bill directly affects high-value estates (over $15 million) by preventing tax avoidance through low effective rates. The recapture mechanism targets estates that would otherwise pay minimal tax relative to their value, while the alternative minimum tax sets a floor on the tax rate. These provisions aim to maintain revenue from large estates under the state's tax code.

In committee Feb 10, 2026 0 co-sponsors
Primary HB 5134
In committee · Connecticut House · Lead sponsor
AN ACT ESTABLISHING A REFUNDABLE CHILD TAX CREDIT.

Maddy summaryHB 5134 establishes a refundable child tax credit of $600 per child for families with up to three children. It directly affects low-to-moderate income households, specifically those with federal adjusted gross income under $100,000 for single filers or $200,000 for married couples filing jointly. The credit is refundable, meaning eligible families may receive the full credit amount even if it exceeds their income tax liability. This policy change reduces tax burden for qualifying families with children, using the state’s personal income tax system to provide direct financial support.

In committee Feb 10, 2026 0 co-sponsors
Primary HB 5129
In committee · Connecticut House · Lead sponsor
AN ACT ESTABLISHING A SURCHARGE ON HIGH-VALUE RECREATIONAL VESSELS AND CONCERNING THE USE OF THE REVENUE GENERATED.

Maddy summaryHB 5129 would require owners of high-value recreational vessels (such as expensive boats and yachts) to pay an additional surcharge. The revenue generated from this surcharge would be dedicated to reducing and eliminating the property tax on motor vehicles, including cars and trucks. This bill directly affects vessel owners through a new fee and vehicle owners through potential tax relief, creating a funding mechanism to lower vehicle taxes by taxing a specific category of recreational boats.

In committee Feb 10, 2026 0 co-sponsors
Primary SB 88
In committee · Connecticut Senate · Lead sponsor
AN ACT REQUIRING INSURANCE COVERAGE FOR SCALP COOLING.

Maddy summarySB 88 requires health insurance policies covering chemotherapy to also cover scalp cooling systems, which prevent hair loss during cancer treatment. It applies to individual and group health insurance plans issued in the state on or after January 1, 2027, directly affecting cancer patients receiving chemotherapy and insurers. The bill mandates that coverage for scalp cooling must be at least as comprehensive as Medicare’s coverage, prohibiting stricter copayments, deductibles, or coinsurance than for other covered benefits. Insurers may still require prior authorization for scalp cooling, but only under the same conditions applied to other covered treatments.

In committee Feb 5, 2026 0 co-sponsors
Primary SB 37
In committee · Connecticut Senate · Lead sponsor
AN ACT ELIMINATING THE APPLICATION FEE FOR HEALTH CARE PROFESSIONALS SEEKING LICENSURE BY THE DEPARTMENT OF PUBLIC HEALTH AND CAPPING THE LICENSURE FEE FOR SUCH PROFESSIONALS AT TWO HUNDRED DOLLARS.

Maddy summarySB 37 eliminates the application fee for health care professionals (such as doctors, nurses, and allied health workers) seeking licensure through the Department of Public Health and caps the total licensure fee at $200. This directly affects individuals applying for or renewing their state licenses to practice in health care roles. The bill removes the current application fee and ensures no professional pays more than $200 for the full licensure process. The change lowers upfront costs for health care professionals entering or maintaining their practice in the state.

In committee Feb 4, 2026 0 co-sponsors
Primary SB 26
In committee · Connecticut Senate · Lead sponsor
AN ACT CONCERNING FUNDING FOR MUNICIPALITIES FOR EARLY VOTING COSTS.

Maddy summarySB 26 provides state funding to reimburse municipalities for increased election costs caused by early voting. It appropriates money from the General Fund for the 2026-2027 fiscal year to cover any cost increases municipalities face in administering early voting. The bill directly affects local governments that operate elections, ensuring they are financially compensated for these specific administrative expenses. This is a straightforward reimbursement mechanism, not a policy change to early voting itself.

In committee Feb 4, 2026 0 co-sponsors
Showing 51 to 60 of 639 bills
Previous 1 5 6 7 64 Next