

Maddy summaryHB 5093 increases the state's base funding for public schools from $11,525 to $18,681 per student over five years, with automatic annual adjustments for inflation. This change directly affects local school districts and municipalities, as it increases state education grants (equalization aid) that school districts receive. The bill allows towns to lower property tax rates by the exact amount of the increased state funding, reducing the tax burden on homeowners. It aims to provide immediate property tax relief by aligning local tax revenue reductions with the new state grant levels. The policy change is triggered solely by the increased state funding, without requiring new local tax revenue.
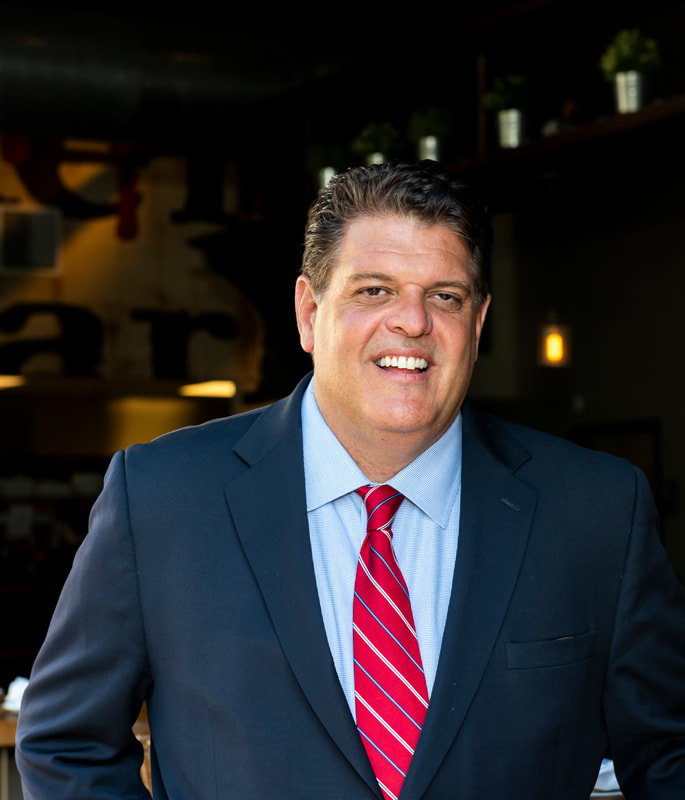
Rep. Dave Rutigliano
Sponsored bills
Maddy summaryHB 5079 repeals a $5 annual fee called the "Passport to the Parks" that was added to motor vehicle registrations. This change directly affects all vehicle owners in the state who previously paid this fee when registering their cars. The bill simply removes the fee from the law, eliminating the charge without creating new programs or requirements. It does not alter park access or funding mechanisms, only eliminating the registration fee. The bill is procedural and focuses solely on removing this specific fee from statute.
Maddy summaryHB 5007 requires the state to fully reimburse municipalities for revenue lost when veterans qualify for a property tax credit under subdivision (83) of section 12-81 of the general statutes. This directly affects municipalities that administer the veterans' property tax exemption, which reduces local tax revenue. The bill's key mechanism is a state-funded reimbursement to offset the financial impact of the exemption. It does not change the veterans' tax credit itself but ensures municipalities are compensated for the revenue loss. (Bill: HB 5007, LCO No. 288)
Maddy summaryHB 5006 eliminates a 1% sales and use tax on meals sold by restaurants, caterers, and grocery stores. The bill directly affects these businesses by removing an additional tax on food sales, reducing their operational costs. Key provision: it amends tax law to remove the specific 1% surcharge applied to meals at these establishments. The purpose is to simplify the tax structure for food service providers without changing general sales tax rates. This is a direct policy change affecting food retailers and their customers through lower prices.
Maddy summaryHB 5029 increases Medicaid provider rates based on phase one of a required rate study (public act 23-186) to ensure rates are competitive with neighboring states and improve access to quality healthcare. It directly affects healthcare providers who treat Medicaid patients, such as hospitals and clinics. The bill mandates rate adjustments to align with regional market standards, aiming to prevent provider shortages and maintain service availability. This policy change focuses on stabilizing provider participation in Medicaid by addressing current rate disparities.
Maddy summaryHB 5009 increases Connecticut's property tax credit for primary residences and motor vehicles by raising the maximum credit from $300 to $1,000 annually. It expands eligibility by increasing the income thresholds taxpayers must meet to qualify for the credit, as outlined in Section 12-704c of state law. This bill directly affects Connecticut homeowners and vehicle owners who pay property tax on their primary residence or vehicle and meet the updated income requirements. The key change simplifies access to the credit for more residents by lowering the income barrier while significantly boosting the maximum benefit amount.
Maddy summaryHB 5005 increases the sales price threshold for motor vehicles subject to a 7.75% sales and use tax rate from $75,000 to "more than $75,000." This means vehicles priced at $75,000 or below will now pay the standard tax rate, while those exceeding $75,000 will be taxed at the higher rate. The bill directly affects high-end vehicle buyers and dealers selling vehicles above this new threshold. It makes no changes to the tax rate itself but adjusts which vehicles qualify for the higher rate.
Maddy summaryHB 5028 removes the "Combined Public Benefits Charge" from electricity bills for residential and business customers of electric distribution companies. This bill directly affects all end-use electricity customers in the state by eliminating this specific fee from their monthly bills. The key mechanism shifts the funding source for these public benefits programs from customer bills to the state General Fund. The bill does not change existing public benefits programs but changes how their costs are paid. This is a direct billing change with no impact on program eligibility or service levels.
Maddy summaryHB 5008 establishes a $2,080 tax credit per full-time equivalent employee for small businesses meeting the U.S. Small Business Administration's definition (typically businesses with fewer than 500 employees). This credit would directly reduce the state tax liability for qualifying small businesses, providing a concrete financial incentive tied to employee count. The bill amends state tax law to implement this credit, which applies to businesses that meet federal SBA criteria. This policy change specifically targets small business employment costs without altering broader tax structures.
Maddy summaryThis bill (HB 7267, now Public Act 25-140) establishes requirements for a fiscal accountability report, but the provided context does not include details about the report's specific content, scope, or who it directly affects. The bill was enacted after passing through the legislature and receiving the governor's signature on July 8, 2025. Without additional information on the report's mechanisms or requirements, no concrete policy changes or affected parties can be described. The summary must remain neutral and factual, based solely on the available details.