

Passed Feb 10, 2022
0 co-sponsors
Total votes
8,467
all sessions
Attendance
98%
155 missed
Higher than 80% of chamber peers
With party
99%
of cast votes
Higher than 75% of chamber peers
Bipartisan score
1%
crosses aisle rarely
Lower than 87% of chamber peers
Sponsored
585
bills & resolutions
Near the chamber average
Committees
4
assignments
585 bills and resolutions
Sponsored bills
Total
585
Primary
206
Co-sponsor
379
This page
585
matching current filters
Add Consumer Protections Regulation Mortgage Servicers
The act subjects mortgage servicers to regulation by the assistant attorney general designated by the attorney general as the administrator of the "Uniform Consumer Credit Code". A "mortgage servicer" is a person that is responsible for servicing a Colorado residential mortgage loan. Regulation of mortgage services includes the requirements of notification, record keeping, payment of fees, compliance with applicable federal laws, reporting, examinations, inspections, and enforcement. A violation of the requirements is subject to enforcement by the administrator, which may include an order requiring the payment of refunds to injured consumers, penalties, costs, and attorney fees.$51,783 is appropriated from the uniform consumer credit code cash fund to the department of law to implement the act and is based on an assumption that the department will require 0.5 FTE to implement the act.(Note: This summary applies to this bill as enacted.)
Signed into law Jul 7, 2021
0 co-sponsors
Voter Transparency In Ballot Measures
The act requires that certain language appear at the beginning of a ballot title for an initiated measure that would either increase or decrease tax revenue through a tax change.First, in the case of a measure that would reduce state tax revenue through a tax change, the ballot title must begin "Shall there be a reduction to the (description of tax) by (the percentage by which the tax is reduced in the first full fiscal year that the measure reduces revenue) thereby reducing state revenue, which will reduce funding for state expenditures that include but are not limited to (the three largest areas of program expenditure) by an estimated (projected dollar figure of revenue reduction to the state in the first full fiscal year that the measure reduces revenue) in tax revenue...?". If the ballot measure specifies the public services or programs that are to be reduced by the tax change, those public services or programs must be stated in the ballot title.Second, in the case of a measure that would reduce local district property tax revenue through a tax change, the ballot title must begin "Shall funding available for counties, school districts, water districts, fire districts, and other districts funded, at least in part, by property taxes be impacted by a reduction of (projected dollar figure of property tax revenue reduction to all districts in the first full fiscal year that the measure reduces revenue) in property tax revenue...?".Finally, in the case of a measure that would increase tax revenue for any district through a tax change, after the language required by section 20 (3)(c) of article X of the state constitution, the ballot title must state either "in order to increase or improve levels of public services", or, if applicable, "in order to increase or improve levels of public services, including, but not limited to (the program expenditure that the measure states will receive increased funding)".The act also changes the requirements for the ballot information booklet entry for certain measures. The act requires the ballot information booklet entry for an initiated measure that would increase or decrease income tax revenue or state sales tax revenue to include a table that shows the number of tax filers in designated income categories, the total tax burden change for each of those income categories, and the average tax burden change for a filer within each of those income categories. If an initiated measure includes a tax change that reduces state tax revenue, the act requires the ballot information booklet to include a description of the 3 largest areas of program expenditure funded by the affected revenue stream.(Note: This summary applies to this bill as enacted.)
Signed into law Jul 7, 2021
0 co-sponsors
Health-care Provider Liens For Injured Persons
The act establishes requirements for the creation and assignment of a health-care provider lien for a person injured in an accident. A health-care provider lien is a lien related to charges for health care provided to a person injured by the negligence or wrongful act of another person, which is asserted against money the injured person may receive from a personal injury claim or uninsured motorist claim.A health-care provider or the health-care provider's assignee creating a lien must advise the injured person of their options for payment, including the use of benefits from an insurance plan. In addition, the provider or assignee must provide additional disclosures about the lien, including how the health-care provider's assignee is compensated and of any common ownership interests among the lien holder and the injured person's health-care providers or legal counsel. The injured person must also be advised that, except in the case of fraud or misrepresentation:If the injured person does not receive a judgment, settlement, or payment on the injured person's claim, the injured person is not liable for any amount of the lien; If the injured person receives a net judgment, settlement, or payment that is less than the amount of the lien, the injured person is not liable for any amount over the amount of the net judgment, settlement, or payment; and The lien holder cannot assign the lien to a collection agency. The act requires that a health-care provider lien cannot include additional finance charges or interest and must be limited to the total of the usual and customary charges billed by health-care providers. In the absence of fraud or misrepresentation:If the injured person does not receive a judgment, settlement, or payment on the injured person's claim, the injured person is not liable for any amount of the lien; If the injured person receives a net judgment, settlement, or payment that is less than the amount of the lien, the injured person is not liable for any amount over the amount of the net judgment, settlement, or payment; and The lien holder cannot assign the lien to a collection agency. A health-care provider or its assignee must comply with the provisions of the act to have a valid health-care provider lien. If a court determines that a health-care provider or its assignee knowingly failed to comply, the injured person may seek a ruling from the court concerning which portions of the lien, if any, the health-care provider or assignee cannot recover.Except in an action under the "Uniform Consumer Credit Code", when a lien is assigned, the amount paid for the assignment, the fact of the assignment, and the terms of the assignment are not admissible as evidence in the underlying personal injury action.The holder of a health-care provider lien may file a record of the lien in accordance with the "Colorado Statutory Lien Registration Act". If more than one health-care provider lien has been asserted against an injured person's net judgment, settlement, or payment for the same accident or incident, a lien for which a record has been filed has priority for payment out of the injured person's net judgment, settlement, or payment over a lien for which no record is filed. If records are filed for more than one health-care provider lien for the same accident or incident, priority is determined by the date on which the record was filed, with the lien with the earliest date of filing having first priority. Filing a record is optional and does not waive any other provisions of the act.(Note: This summary applies to this bill as enacted.)
Signed into law Jul 7, 2021
0 co-sponsors
Record Sealing Collateral Consequences Reduction
Under current law, adults and juveniles can file motions for relief from collateral consequences. The act states that a motion can be filed related to convictions retroactively.The act allows the state public defender and the office of alternate defense counsel to apply for grants and accept gifts and donations for the purposes of representing defendants in record sealing proceedings. The state public defender and the office of the alternate defense counsel shall not accept a gift, grant, or donation if the gift, grant, or donation is conditioned on its use for sealing records for a specific identified individual or individuals. The state public defender and the office of the alternate defense counsel shall report on the receipt and expenditure of gifts, grants, and donations at its SMART act hearing.The act creates an automatic sealing process for arrest records when no criminal charges are filed. For arrest records on or after January 1, 2022, the Colorado bureau of investigation (CBI) shall seal arrest records in its custody and control after a year has passed without the filing of criminal charges. For arrest records before January 1, 2022, CBI shall seal arrest records for:Felonies with a 3-year statute of limitations if 3 years have passed since the date of arrest without the filing of charges; and Misdemeanors, traffic misdemeanors, petty offenses, or municipal violations with an 18-month statute of limitations or less if 18 months have passed since the date of arrest without the filing of charges. Felony arrest records with a statute of limitations of longer than 3 years or with no statute of limitations are not eligible for automatic sealing. The department of education can still access and use records sealed under these provisions.The act creates a process for a person with multiple conviction records that are eligible for sealing due to an intervening conviction to petition the court in a civil proceeding to have the records sealed. The district attorney has an opportunity to object, and if the district attorney objects, the court sets the matter for hearing to determine whether to seal the records.The act allows a person who receives a full and unconditional pardon to have his or her conviction record sealed.The act creates a process to automatically seal drug convictions. The state court administrator (administrator) shall compile a list of drug convictions eligible for sealing under current law, and seal the record:If the drug conviction is for a petty offense or misdemeanor, and at least 7 years have passed since the disposition of the case; or If the drug conviction is for a felony, and at least 10 years have passed since the disposition of the case. After the administrator compiles the list, the administrator shall send the list to the CBI for review and the bureau shall remove any convictions in which the identity of the defendant is unverifiable or convictions in which the defendant had another conviction during the waiting period. The bureau shall send its list to each district attorney in the state. The district attorney shall remove any convictions in which a condition of a plea was that the defendant agreed to not have the case sealed and convictions in which the defendant has pending criminal charges. Each district attorney shall send its amended list to the administrator. The administrator shall compile each of the lists into one list and sort the convictions by judicial district.The district attorney shall send the list to the chief judge for the judicial district and the courts of that judicial district shall enter sealing orders based on the list received.The administrator shall develop a website that allows defendants to confidentially determine whether the defendant's conviction has been sealed and information about how to receive a copy of the sealing order.The act appropriates from the general fund $300,605 to the judicial department to implement the act. The act appropriates $39,815 from the general fund to the department of public safety for the biometric identification unit.(Note: This summary applies to this bill as enacted.)
Signed into law Jul 6, 2021
0 co-sponsors
Revisor's Bill
To improve the clarity and certainty of the statutes, the act amends, repeals, and reconstructs various statutory provisions of law that are obsolete, imperfect, or inoperative. The specific reasons for each amendment or repeal are set forth in the appendix to the act. The amendments made by the act are not intended to change the meaning or intent of the statutes, as amended.(Note: This summary applies to this bill as enacted.)
Signed into law Jul 2, 2021
0 co-sponsors
Environmental Justice Disproportionate Impacted Community
Section 3 of the act defines "disproportionately impacted community" (DIC) as:A community that is in a census block group where the proportion of households that are low income, that identify as minority, or that are housing cost-burdened is greater than 40%; or Any other community as identified or approved by a state agency, if the community: Has a history of environmental racism perpetuated through redlining, anti-Indigenous, anti-immigrant, anti-Hispanic, or anti-Black laws; or is one where multiple factors may act cumulatively to affect health and the environment and contribute to persistent disparities. Section 3 also requires the air quality control commission (AQCC) to promote outreach to and engage with DICs by creating new ways to gather input from communities across the state, using multiple languages and multiple formats, and transparently sharing information about adverse effects resulting from its proposed actions.Section 4 creates the environmental justice action task force (task force) in the department of public health and environment (department), the goal of which is to propose recommendations to the general assembly regarding practical means to address environmental justice inequities, particularly within DICs. The department will report on the task force's activities during the department's "SMART Act" presentations. The task force will:Hold meetings to solicit public comment concerning the development of a state agency-wide environmental justice strategy and a plan to implement that strategy, including ways to address data gaps and data sharing between state agencies and the engagement of disproportionately impacted communities; Evaluate and propose recommended revisions to the definitions of DIC, "proposed state action", and "agency" and the state agencies and their proposed actions that are subject to section 3; and File a final report by November 14, 2022, regarding its recommendations. Section 7 requires the AQCC to include greenhouse gas (GHG) in the list of air pollutants required to be reported in an air pollutant emission notice (APEN) and allows the AQCC to require that APENs for GHG report the previous calendar year's emissions of GHG in the form of carbon dioxide equivalent. Section 8 requires the AQCC to adopt rules, including permit processing fees, that apply to permits for sources of pollutants that cause or contribute to significant health or environmental impacts in DICs. Section 9 allows the division of administration in the department to reopen an air permit to add monitoring requirements for sources that affect DICs.Section 12 creates in the department the position of an environmental justice ombudsperson and directs the ombudsperson to promote environmental justice for the people of Colorado, particularly as an advocate for DICs and as a liaison between DICs and the department. Section 12 also creates in the department the environmental justice advisory board and directs the board to advise the ombudsperson and to develop guidelines for a grant program to fund environmental mitigation projects that avoid, minimize, measure, or mitigate adverse environmental impacts in DICs.Section 10 requires the AQCC to establish an annual APEN fee for GHG and authorizes the use of the fees to pay for the engagement of DICs required by section 3 and for the ombudsperson position created in section 12. Current law credits air quality fines to the general fund; section 13 creates the community impact cash fund and, over the course of 5 years, credits all of the fines to the fund, which is used to pay for environmental mitigation projects and the environmental justice advisory board.Section 14:Allows the AQCC to adopt rules that add permit requirements for sources that affect DICs; Directs the AQCC to adopt rules that pursue near-term reductions in GHG emissions, including reducing GHG emissions from electric utilities by at least 48% by 2025 and 80% by 2030, relative to 2005 levls; Directs the division to prepare an annual report that indicates whether GHG emission reduction requirements are being met and, if not, to develop and propose additional requirements to the AQCC; Requires each wholesale generation and transmission electric cooperative to file with the public utilities commission (PUC) and the division an electric resource plan that will achieve at least an 80% reduction of GHG emissions by 2030, relative to 2005 levels; Requires certain electric utilities that serve at least 50,000 Colorado retail customers to either file a clean energy plan with the division or comply with AQCC rules that would require GHG emission reductions of at least 48% by 2025 and 80% by 2030, relative to 2005 levels; Requires the AQCC to adopt rules to reduce GHG emissions from oil and gas exploration, production, processing, transmission, and storage operations by at least 36% by 2025 and 60% by 2030, relative to 2005 levels; Requires the AQCC to adopt rules to reduce GHG emissions from the industrial and manufacturing sector in the state by at least 20% by 2030, relative to 2015 levels; and Authorizes the AQCC to adopt a rule or program that provides for the use of a trading program, including a comprehensive and centralized accounting system to track emissions from the sources that participate in the program. Section 16 requires that the economic impact analysis for GHG rules must include an analysis of the social cost of greenhouse gases. Section 17 requires that the division make publicly available the data upon which its GHG forecast is based and requires that the forecast include at least one scenario that does not include emission reductions projected to occur pursuant to existing law.Section 19 requires the just transition office in the division of employment and training in the department of labor and employment to develop a proposed long-term budget to adequately finance the just transition plan relating to the closure of coal-fired electric generation facilities. Section 20 modifies the mission statement for the Colorado energy office, including by adding the goal of supporting Colorado's transition to a more equitable, low-carbon, and clean energy economy and promoting resources that reduce air pollution and greenhouse gas emissions, including pollution and emissions from electricity generation, buildings, industry, agriculture, and transportation.Existing law requires electric utilities to provide best value employment metrics to the PUC when applying for approval of new resource acquisitions. Section 22 requires the state auditor to study the implementation of the best value employment metrics requirement.To implement the act, section 23 appropriates the following:$2,550,218 from the general fund and the community impact cash fund to the department, of which amount $382,680 is reappropriated to the department of law to provide legal services and $239,642 is reappropriated to the office of the governor for use by the office of information technology to provide information technology services; and $146,703 from the general fund to the office of the governor for use by the Colorado energy office.(Note: This summary applies to this bill as enacted.)
Signed into law Jul 2, 2021
0 co-sponsors
Bias-motivated Crimes
The act specifies that for harassment that is bias-motivated or a bias-motivated crime, the bias motivation only needs to be part of the defendant's motivation in committing the crime.The act makes the crime of harassment when the harassment is bias-motivated a victim rights act crime, which provides a victim certain statutory rights.(Note: This summary applies to this bill as enacted.)
Signed into law Jun 28, 2021
0 co-sponsors
Income Tax
Section 2 of the act requires CollegeInvest to provide the department of revenue (department) with a secure electronic report of CollegeInvest account holders who are also Colorado taxpayers who made distributions between January 1, 2017, and January 1, 2021. The department is required to examine a risk-based sample of such taxpayers to substantiate that the distribution was made for authorized purposes. The department is also required to regularly example a risk-based sample of distributions on or after January 1, 2021, and determine if the taxpayer paid the correct amount of income tax. The executive director of the department is required to provide a report of the examinations as part of the department's presentation to its legislative committee of reference.Section 3 of the act modifies how taxable income is determined for individuals for purposes of the state income tax. Specifically, it:Extends the limit on the federal deduction allowed under section 199A of the internal revenue code; Imposes a cap for taxpayers with adjusted gross incomes equal to or exceeding $400,000 on certain itemized deductions claimed under the internal revenue code; Requires individual taxpayers to add amounts of federal taxable income that are equal to the enhanced federal deductions for food and beverage in a restaurant for the 2022 income year (this is also required for corporate taxpayers in section 7 of the act); Repeals, for social security income earned by individuals who are 65 years of age or older that is included in federal taxable income only, the cap on the deduction for pension and annuity income received; and Adds an annually adjusted cap, per taxpayer per beneficiary, on the income tax deduction for contributions made to 529 plans, and requires CollegeInvest to provide the department with a secure electronic report containing specified information for the 529 plans account owners and third-party contributors necessary for the administration of the income tax deduction. Section 4 of the act increases the earned income tax credit to 20% for income tax years commencing on or after January 1, 2022, but before January 1, 2023, and income tax years commencing on or after January 1, 2026. Section 3 also increases the earned income tax credit to 25% for income tax years commencing on or after January 1, 2023, but before January 1, 2026. Finally, section 4 of the act applies the lowered minimum age for individuals without a qualifying child in the federal "American Rescue Plan Act of 2021" to the state credit for income tax years commencing on or after January 1, 2022.Section 5 of the act funds the child tax credit for income tax years commencing on or after January 1, 2022, and allows a child tax credit in the state regardless of the federal requirement that a qualifying child must have a social security number for the federal child tax credit. Section 5 of the act also specifies that if the changes to the federal child tax credit in the "American Rescue Plan Act of 2021" are no longer in effect, the percentages of the state child tax credit are increased.Section 6 of the act modifies the computation of the corporate income tax receipts factor to make it more congruent with combined reporting and also prevents corporations from using tax shelters in foreign jurisdictions for the purpose of tax avoidance.Section 7 of the act functions to prevent corporations from using tax shelters in foreign jurisdictions for the purpose of tax avoidance and additionally modifies how taxable income is determined for C corporations for purposes of the state income tax. Specifically, it requires corporate taxpayers to add amounts of federal taxable income that are equal to the enhanced federal deductions for food and beverage in a restaurant for the 2022 income year.Section 8 of the act limits the state subtraction for certain capital gains incurred by allowing the subtraction to a taxpayer who is required to file a Schedule F, profit or loss from farming, as an attachment to the taxpayer's federal income tax return for the tax year in which the net capital gains arise for the sale of real property, not tangible personal property, that is classified as agricultural land for property tax purposes.Section 9 of the act creates a temporary income tax credit for a business for a percentage of the conversion costs to convert the business to a worker-owned coop, an employee stock ownership plan, or an employee ownership trust.Sections 10 through 13 of the act address the avoidance of income tax by certain captive insurance companies.Section 14 of the act adds an appropriation to:The office of the governor for use by the office of economic development for the administration of the income tax credit for a business converting to a worker-owned coop, an employee stock ownership plan, or an employee ownership trust; and The department of revenue for administration and support.(Note: This summary applies to this bill as enacted.)
Signed into law Jun 23, 2021
0 co-sponsors
Insurance Premium Property Sales Severance Tax
To be deemed to maintain a home office or regional home office and pay the insurance premium tax at a rate of 1%, the act requires a company to have a minimum percentage of its total domestic workforce in the state. This percentage is 2% for 2022, 2.25% for 2023, and 2.5% for 2024 and thereafter. The act also narrows the tax exemption for annuities considerations. For the purpose of auditing a company's tax statement, the commissioner of insurance may appoint an independent examiner to conduct an examination on behalf of the commissioner.For purposes of imposing the property tax, the act specifies that the actual value of real property reflects the value of the fee simple estate and the actual value of personal property is determined based on the property's value in use, which will be defined by the property tax administrator. The act also increases the per schedule exemption for business personal property from $7,900 to $50,000, adjusted for inflation, and the state is required to reimburse local governments for lost property tax revenue caused by the increase. Assessors are required to provide an estimate of the exempt business personal property along with the certifications to local governments.The state sales and use tax is imposed on the sale and use of tangible personal property. The act codifies the department of revenue rule that the definition of "tangible personal property" includes "digital goods" and specifies that the state sales tax applies to amounts charged for mainframe computer access, photocopying, and packing and crating. Beginning January 1, 2022, a retailer whose total taxable sales were greater than $1 million for a filing period is not permitted to retain any portion of the sales and use tax collected as compensation for the retailer's tax-collection expenses.The act limits the allowable deductions, which are used to determine the taxable amount of oil and gas subject to the severance tax, to direct costs actually paid or accrued by the taxpayer for those purposes. Beginning with the 2022 taxable year, the act phases out the quarterly exemption and the tax credits for the severance tax on coal. The additional revenue that results from changes to the coal severance tax is credited to the just transition cash fund.(Note: This summary applies to this bill as enacted.)
Signed into law Jun 23, 2021
0 co-sponsors
Ask Maddy
·
AI policy assistant
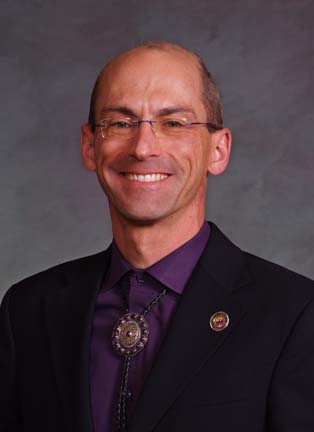
Ask Maddy about Mike Weissman
Scope: colorado
Hi! I can help you understand Mike Weissman's legislative record. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline