

Oklahoma Capital Investment Board; repealing the Oklahoma Capital Formation Act and Board. Effective date.
SB 718 repeals Oklahoma's Capital Investment Board and related statutes (Sections 5085.1-5085.16) while updating tax credit provisions for venture capital investments. The bill maintains a 20% tax credit for investments in qualified venture capital companies that fund Oklahoma business ventures meeting specific criteria (e.g., 75% capital in-state, 50% employees/assets in Oklahoma). It removes the requirement for the Capital Investment Board to certify entities or investments, leaving the Oklahoma Tax Commission to administer the program directly. This change simplifies oversight but preserves the core tax credit mechanism for businesses seeking to expand within Oklahoma.
Bill status
in committee
1 of 4 stages cleared
Introduction
Feb 2025
Committee Review
Floor Vote
Governor
Introduced Feb 3, 2025
Last action Feb 24, 2025
Maddy AI version diff · 1 comparison
What changed between versions
Introduced
→
Floor (Senate)
·
4 edits
MODERATE
The bill text was reformatted from an introduced version to a Senate floor version, with substantive amendments adding new definitions and clarifying requirements for tax credit eligibility. The floor version adds definitions for 'direct investment' and 'debt and equity funds', clarifies that 'intangible assets' include software and patents, and specifies that debt investments must have repayment schedules of at least five years.
Scope change
The bill's scope remains focused on Oklahoma's venture capital tax credit program, but eligibility criteria and definitions were expanded and clarified to provide more specific guidance on what qualifies for the tax credit.
DEFINITION
Added new definitions for 'direct investment' and 'debt and equity funds' to clarify what investments qualify for the tax credit program.
REQUIREMENT
Modified the definition of 'intangible assets' to explicitly include computer software, licenses, patents, and copyrights.
Added a requirement that debt investments must have repayment schedules of at least five years with level principal amortization.
TECHNICAL
Reformatted the document structure and page numbering from introduced version to Senate floor version format.
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
6
Key actions
1
Committee
1
Feb 19, 2025
Upper · Passed
Reported Do Pass as amended Economic Development, Workforce and Tourism committee; CR filed
upper
Feb 3, 2025
Introduced
First Reading
upper
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
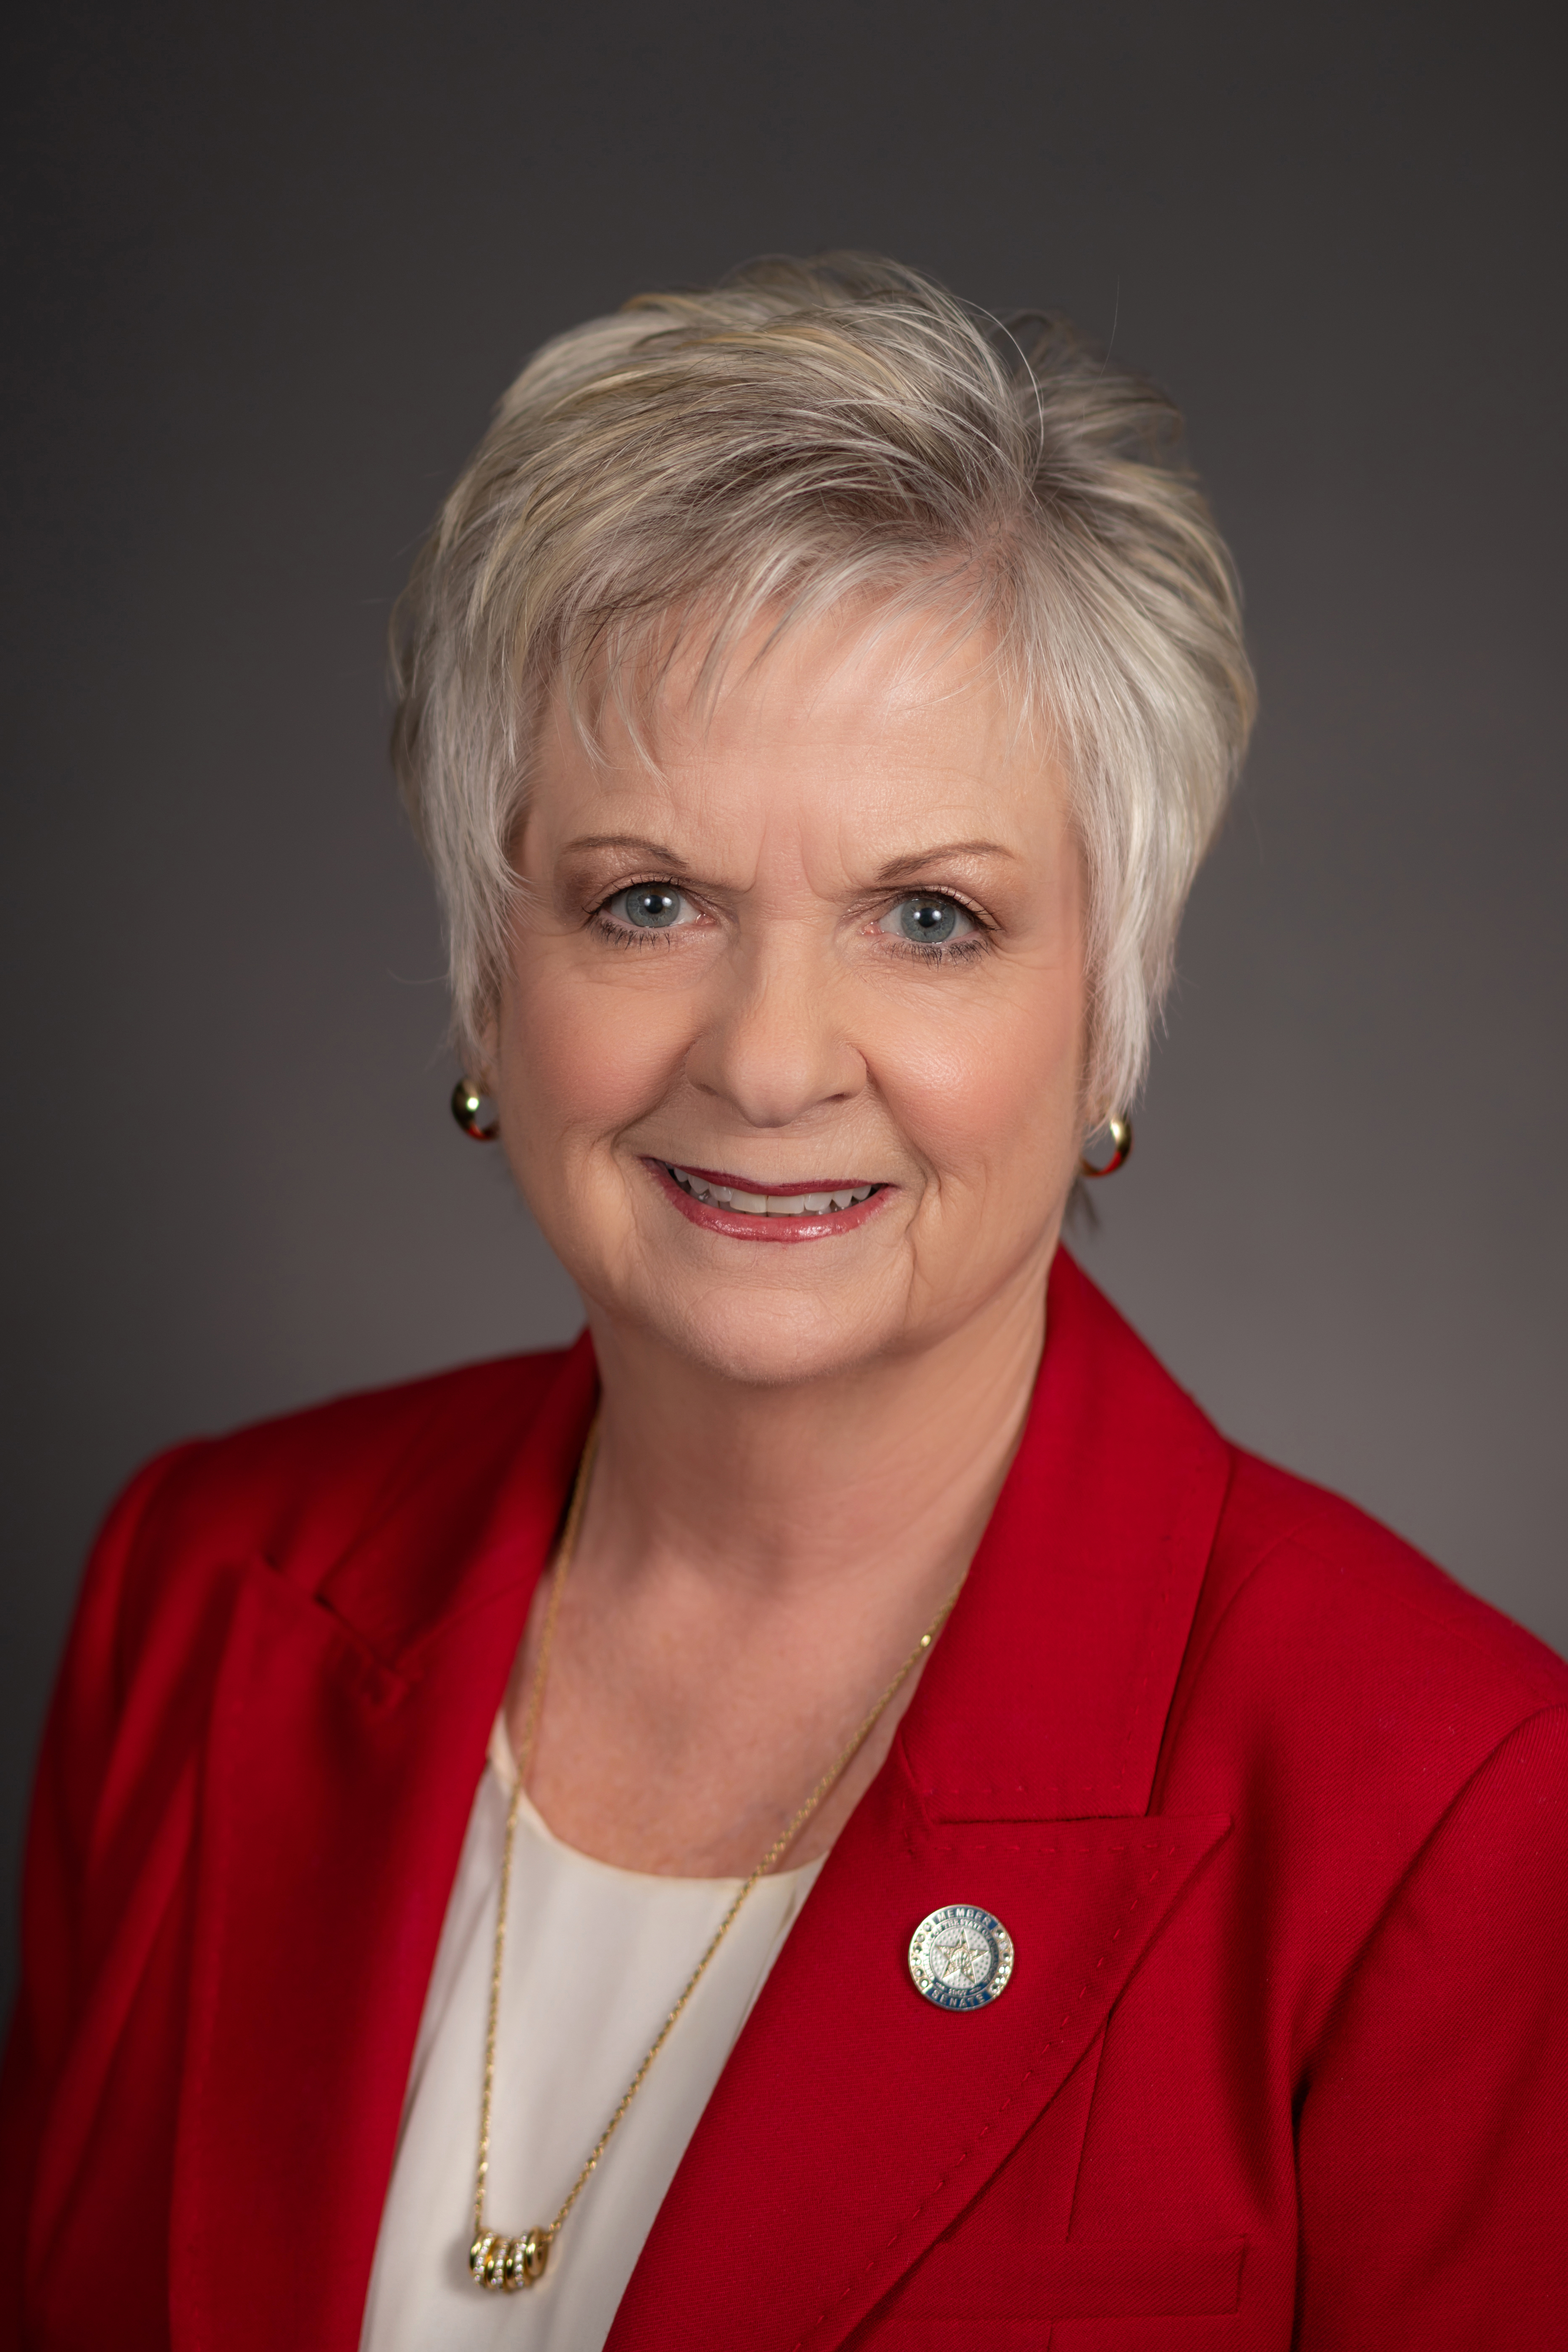
Julie Daniels
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about SB 718
Scope: OK
Hi! I can help you understand SB 718. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline