Issue · Budget & Taxes

Budget & Taxes (Fees & Licensing)

Every budget & taxes bill, vote, and legislator stance in New York, automatically classified by Maddy, our AI policy reader.

Total bills
64
2025 Regular Session
Top supporter
Jamaal Bailey
100% support rate
Top opponent
Andrew Lanza
0% support rate
Ranked legislators
10
5 support · 5 oppose
Key legislators

Who's moving fees & licensing in New York

Legislators moving fees & licensing in New York
Legislator Party Stance Support rate Votes
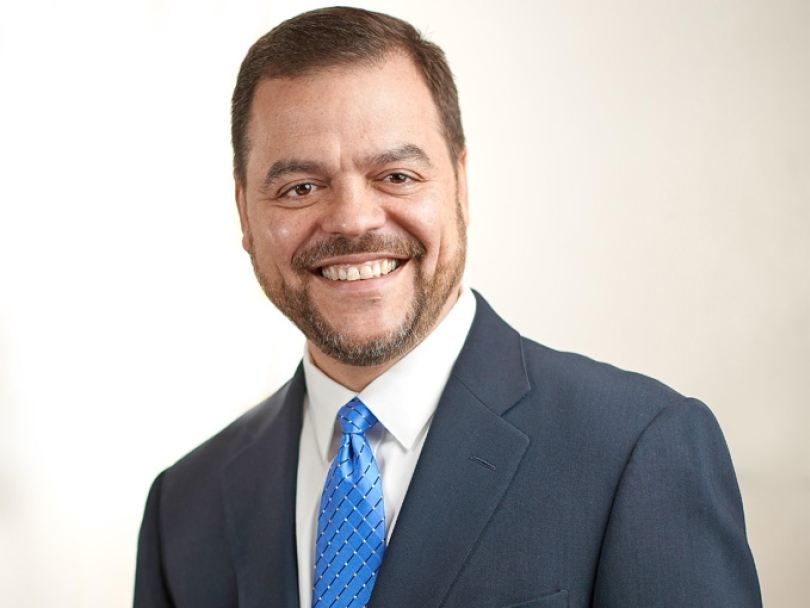
Jamaal Bailey
Jamaal Bailey Senate · District 36
D
Strong +
100% 13
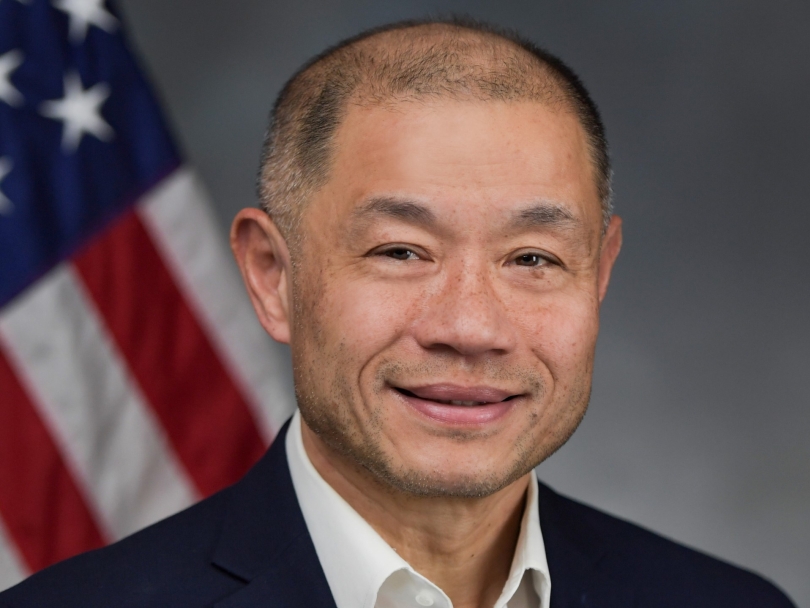
John Liu
John Liu Senate · District 16
D
Strong +
100% 13
Leroy Comrie
Leroy Comrie Senate · District 14
D
Strong +
100% 13
Luis Sepúlveda
Luis Sepúlveda Senate · District 32
D
Strong +
100% 13
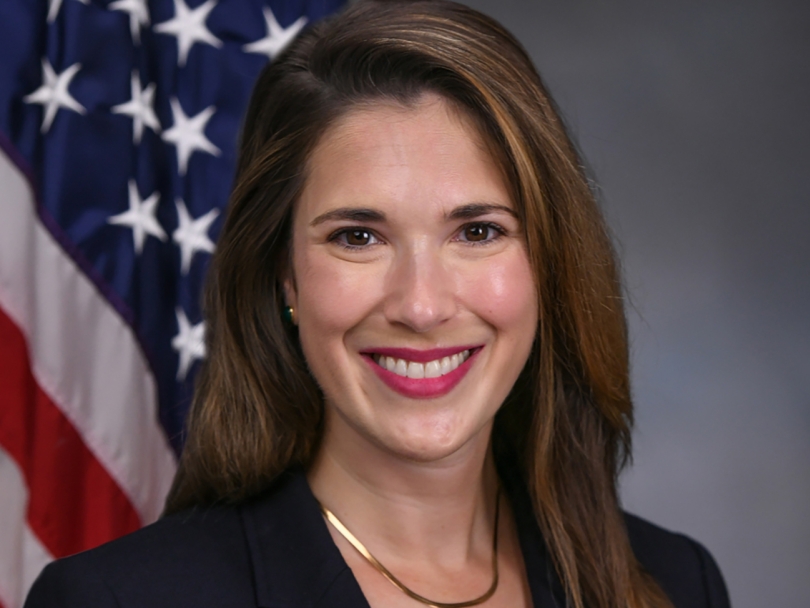
Michelle Hinchey
Michelle Hinchey Senate · District 41
D
Strong +
100% 13
Andrew Lanza
Andrew Lanza Senate · District 24
R
Strong −
0% 8
Alexis Weik
Alexis Weik Senate · District 8
R
Strong −
0% 7
Patricia Canzoneri-Fitzpatrick
Patricia Canzoneri-Fitzpatrick Senate · District 9
R
Strong −
0% 7
Danny Norber
Danny Norber House · District 16
R
Strong −
0% 6
Jack Martins
Jack Martins Senate · District 7
R
Strong −
0% 6
Showing 61–64 of 64 bills

All budget & taxes bills

in committee · New York · Assembly Jan 7, 2026

A 2418: Relates to authorizing the imposition of service charges upon certain real property

This bill clarifies that certain previously tax-exempt properties (like nonprofits, religious organizations, and hospitals) must now pay "service charges" for specific municipal services - including police, fire, street maintenance, sanitation, and water supply. It defines "service charge" as a fee distinct from taxes or special assessments, requiring these properties to contribute to costs for the listed services. The bill also specifies that municipal properties within their own boundaries remain exempt from these charges. This change applies to properties that were previously exempt under tax law but not used for charitable, hospital, educational, or cemetery purposes.
Sub-Topics Fees & Licensing
in committee · New York · Assembly Mar 10, 2026

A 8642: Enacts the "NYS health care tax reform act"

Enacts the "NYS health care tax reform act"; establishes a public goods and medicaid subsidy surcharge on insurance corporations; establishes a public goods and medicaid subsidy surcharge on business corporations; establishes a public goods and medicaid subsidy surcharge on pass-through entities; relates to filing fee surcharges; relates to revenues to be included in the health care reform act resources fund; establishes a public goods and medicaid surcharge on misclassified workers.
in committee · New York · Senate May 12, 2026

S 8463: Provides a one-year utility bill tax and surcharge holiday and two-year green energy tax holiday

S 8463 provides a one-year exemption from utility taxes and specific surcharges for all residential and commercial utility customers, effective 14 days after enactment. It also creates a two-year exemption from tariffs for renewable energy systems, electric vehicle infrastructure, and charging stations. During these periods, utility companies must reduce customer prices by the exact amount of the exempted taxes and surcharges. The state will reimburse lost revenue to utility funds within 45 days after the one-year period ends. This bill directly affects all utility ratepayers and impacts how utilities price services for renewable energy investments.
in committee · New York · Senate Jan 7, 2026

S 1256: Prohibits the transfer of unexpended moneys from funds receiving moneys from a dedicated fee into any other fund

This bill prohibits state agencies from moving unspent money from funds that receive dedicated fees (like specific user fees) into other funds or using it for unrelated purposes. It applies directly to state funds that are legally required to keep money separate from general funds and spend it only for the specific purpose they were created for. The law requires these funds to remain distinct, preventing their unspent balances from being redirected to other programs or accounts. As a procedural budget rule, it focuses on fund management rather than new services or taxes.
Showing 61 to 64 of 64 bills
Previous 1 5 6 7