Issue · Budget & Taxes

Budget & Taxes (Revenue)

Every budget & taxes bill, vote, and legislator stance in New York, automatically classified by Maddy, our AI policy reader.

Total bills
52
2025 Regular Session
Top supporter
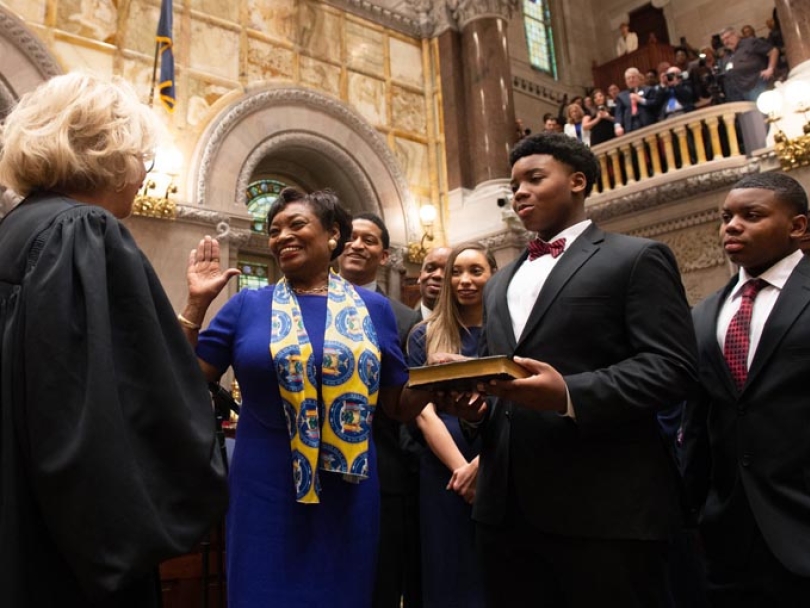
Andrea Stewart-Cousins
100% support rate
Top opponent
Andrew Lanza
0% support rate
Ranked legislators
10
5 support · 5 oppose
Key legislators

Who's moving revenue in New York

Legislators moving revenue in New York
Legislator Party Stance Support rate Votes
Andrea Stewart-Cousins
Andrea Stewart-Cousins Senate · District 35
D
Strong +
100% 7
Dan Stec
Dan Stec Senate · District 45
R
Strong +
100% 7
Jamaal Bailey
Jamaal Bailey Senate · District 36
D
Strong +
100% 7
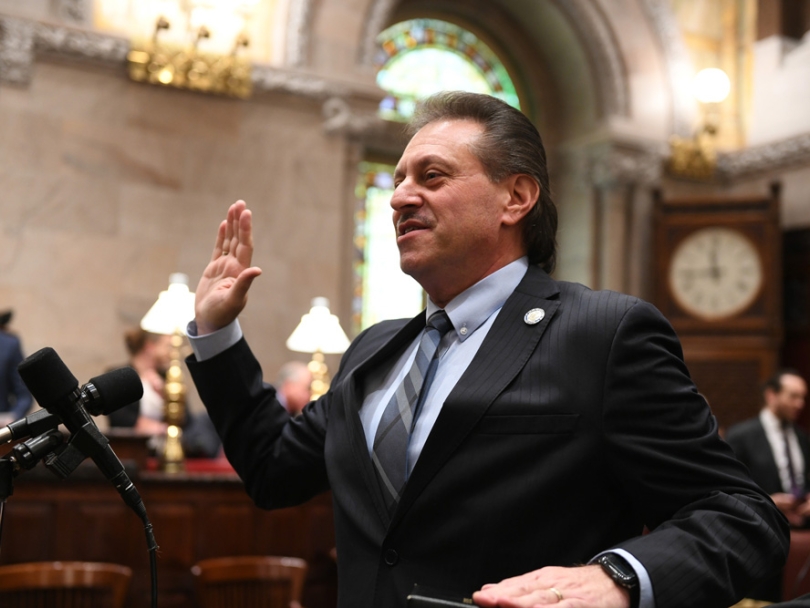
Joe Addabbo
Joe Addabbo Senate · District 15
D
Strong +
100% 7
Joe Griffo
Joe Griffo Senate · District 53
R
Strong +
100% 7
Andrew Lanza
Andrew Lanza Senate · District 24
R
Strong −
0% 7
Al Stirpe
Al Stirpe House · District 127
D
Strong −
0% 6
Alec Brook-Krasny
Alec Brook-Krasny House · District 46
R
Strong −
0% 6
Alexis Weik
Alexis Weik Senate · District 8
R
Strong −
0% 6
Bill Conrad
Bill Conrad House · District 140
D
Strong −
0% 6
Showing 31–40 of 52 bills

All budget & taxes bills

in committee · New York · Senate Mar 23, 2026

S 3245: Relates to payments in lieu of taxes

This bill (S 3245) updates how New York local governments and school districts calculate payments in lieu of taxes (PILT) for tax-exempt properties. It requires the Commissioner of Taxation to compute an annual "quantity change factor" showing percentage shifts in taxable property values between specific assessment rolls. This factor must include changes in value for properties under PILT agreements, ensuring these adjustments directly impact local tax revenue calculations. The bill affects municipalities and school districts receiving PILT payments by standardizing how property value changes are factored into their funding.
Sub-Topics Property Tax Revenue
in committee · New York · Senate Jan 7, 2026

S 2615: Authorizes one percent of mobile sports tax revenue be used for problem gambling

This bill directs 1% of mobile sports betting tax revenue (with a minimum of $6 million annually) to fund problem gambling education and treatment programs. It requires the state gaming commission to allocate these funds starting in the first fiscal year mobile betting operations begin, with the money deposited into the commercial gaming fund for this specific purpose. The policy directly affects state-funded gambling treatment services and public health programs addressing gambling addiction. It creates a dedicated, ongoing revenue stream from mobile sports betting taxes to support these services, separate from other lottery or gaming funds.
in committee · New York · Assembly Jun 16, 2025

A 7854: Authorizes the town of Patterson to impose a hotel and motel tax

This bill authorizes the town of Patterson to impose a tax of up to 5% on hotel and motel room rentals, including bed and breakfasts and tourist facilities, but not on guests staying 90+ consecutive days (defined as "permanent residents"). Hotels and motels would collect the tax from guests and remit it to the town’s chief fiscal officer, with exemptions for state/federal government, non-profits, and other specified entities. All tax revenue would go into Patterson’s general fund for any lawful purpose, such as public services or infrastructure. The authorization expires two years after the bill takes effect.
Sub-Topics Revenue State Budget
in committee · New York · Assembly Jan 5, 2026

A 1032: Updates value capture mechanisms for NYC and the MTA

This bill updates how New York City and local municipalities can capture value from mass transportation projects, making transparency requirements permanent. It requires cities to publish two analyses before public hearings: property value projections showing increased tax revenue from projects, and transportation service benefits, both in machine-readable formats. Municipalities may then use specific value-capture methods like tax increment financing, special transportation assessments, or land value taxation to fund projects, with revenue limits tied to actual property benefits. The bill directly affects NYC and local governments contracting with the MTA to finance transportation capital projects benefiting specific districts.
Sub-Topics Revenue
in committee · New York · Senate Jan 7, 2026

S 1805: Grants real property tax abatement to rent-controlled or rent regulated properties when the maximum authorized rent exceeds 1/2 of the tenants' household income

Authorizes application of the property tax abatement for rent-controlled or rent regulated properties occupied by senior citizens or disabled persons, to those units occupied by tenants paying the maximum allowable rent when such rent exceeds 1/2 of the household income; provides for state payments to cities affected thereby equal to 10% of lost real property tax revenue.
in committee · New York · Senate May 27, 2025

S 6669: Extends the authorization for the county of Monroe to impose certain sales and compensating use taxes

S 6669 extends Monroe County's authorization to impose an additional 1% sales tax (on top of the existing 3%) until November 30, 2027. The revenue from this extra 1% will be distributed as follows: 5% to school districts outside Rochester, 3% to towns, 1.25% to villages, and 93.75% to the city of Rochester and Monroe County (with the county's share used for county services). The bill ensures this additional tax revenue does not affect future calculations for county sales tax rate changes.
Sub-Topics Revenue Sales Tax
signed · New York · Senate Aug 7, 2025

S 6337: Authorizes the county of Rockland to impose an additional rate of sales and compensating use taxes

This bill authorizes Rockland County to impose two additional sales tax rates: a 0.625% rate (5/8 of 1%) from March 2022 through November 2027, and a 0.375% rate (3/8 of 1%) from March 2027 through November 2027. It directly affects residents and businesses in Rockland County who pay sales tax, as well as towns and villages within the county that receive allocated tax revenue. The law requires the county to distribute 20% of the first tax's revenue to towns/villages based on population, and 16.67% (2027) and 33.33% (2028-2027) of the second tax's revenue to towns/villages with police departments based on full-time police officers - funds cannot be used for police salaries. The bill specifies these tax rates and revenue distribution mechanisms until November 30, 2027.
Sub-Topics Revenue Sales Tax
in committee · New York · Senate Jan 7, 2026

S 2175: Exempts low-emission and energy efficient vehicles from retail sales and compensating use taxes

S 2175 exempts EPA-certified low-emission and energy-efficient vehicles from New York's retail sales tax and compensating use tax. This directly affects buyers of qualifying electric, hybrid, or other ultra-low-emission vehicles (defined by EPA certification or a 9+ score on pollution and greenhouse gas ratings). The exemption is funded by offsetting tax revenue losses with proceeds from emissions allowance auctions, capped at $27 million annually. The law takes effect in the first sales tax quarter after enactment and expires December 31, 2028.
in committee · New York · Assembly Jan 7, 2026

A 3486: Relates to the stock transfer tax

This bill modifies how stock transfer tax revenue is allocated. It gradually increases the percentage of tax rebates paid to taxpayers (from 30% to 80% over time) before directing remaining funds to the Metropolitan Transportation Authority's special assistance fund. The key mechanism is a phased change in rebate rates for stock transactions, with all leftover tax money after rebates being sent to the MTA fund starting in 1981. This directly affects the MTA by providing dedicated funding for its operations through the special assistance fund.
Sub-Topics Revenue
in committee · New York · Senate Jun 9, 2025

S 7420: Relates to Suffolk county sales and compensating use taxes

S 7420 extends Suffolk County's authority to impose an additional 1% sales and use tax on top of existing rates, effective June 2021 through November 2027. This tax applies to residents and businesses within Suffolk County that pay sales tax. The bill requires that 12.5% to 37.5% of the tax revenue collected must fund public safety, with the remainder going to the county's general fund. The measure modifies existing tax law to formalize this temporary tax increase and its revenue allocation rules.
Showing 31 to 40 of 52 bills
Previous 1 3 4 5 6 Next