

Issue · Budget & Taxes
Budget & Taxes (Sales Tax)
Every budget & taxes bill, vote, and legislator stance in New York, automatically classified by Maddy, our AI policy reader.
Total bills
303
2025 Regular Session
Top supporter
Andrew Hevesi
100% support rate
Top opponent
Karen McMahon
0% support rate
Ranked legislators
10
5 support · 5 oppose
Key legislators
Who's moving sales tax in New York
| Legislator | Party | Stance | Support rate | Decisive votes |
|---|---|---|---|---|
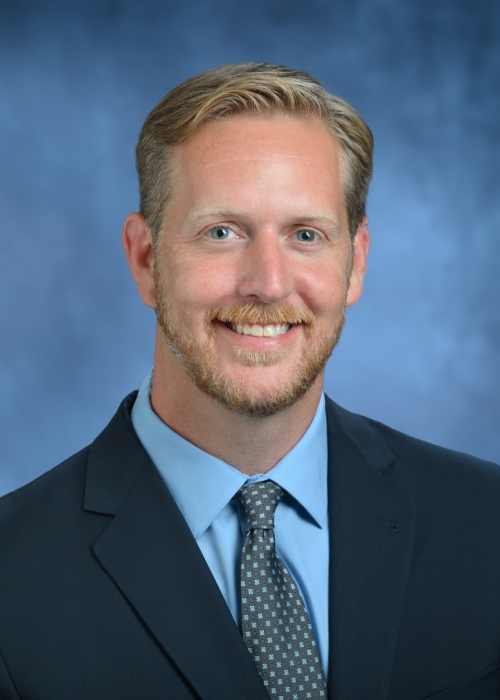
Andrew Hevesi
House · District 28
|
D |
Strong +
|
100% | 39 |
Bill Magnarelli
House · District 129
|
D |
Strong +
|
100% | 39 |
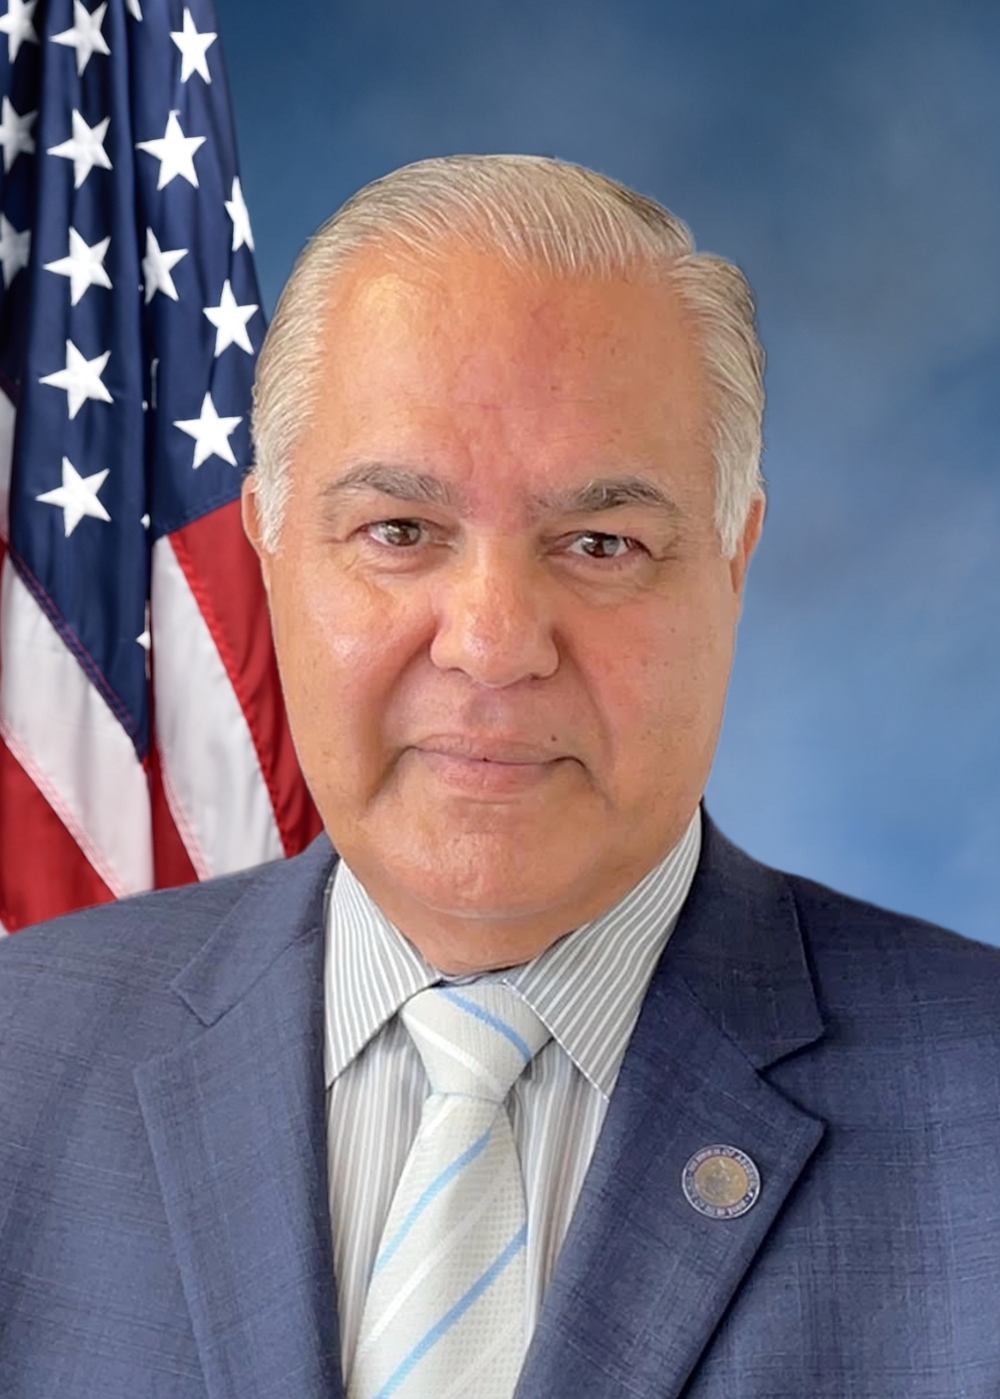
Nader Sayegh
House · District 90
|
D |
Strong +
|
100% | 38 |
Vivian Cook
House · District 32
|
D |
Strong +
|
100% | 38 |
Charles Fall
House · District 61
|
D |
Strong +
|
100% | 37 |
Karen McMahon
House · District 146
|
D |
Strong −
|
0% | 39 |
Kwani O'Pharrow
House · District 11
|
D |
Strong −
|
2% | 44 |
Pat Chludzinski
House · District 143
|
R |
Strong −
|
2% | 44 |
Bill Conrad
House · District 140
|
D |
Strong −
|
2% | 42 |
Kalman Yeger
House · District 41
|
D |
Strong −
|
2% | 41 |
Showing 211–220 of 303
bills
All budget & taxes bills
A 4764: Repeals the excise tax on medical cannabis and the medical cannabis trust fund
Topics
✓ Budget & TaxesSupports Budget & TaxesRepeals excise tax on medical cannabis, providing tax relief and eliminating dedicated funding for the trust fund.
✗ HealthcareOpposes HealthcareRepeals medical cannabis trust fund, defunding dedicated healthcare program; aligns with 'oppose' criteria of defunding public health initiatives.
Sub-Topics
Sales Tax
A 6408: Relates to extending the authorization for Ontario county to impose additional rates of sales and compensating use taxes
Sub-Topics
Sales Tax
A 6483: Extends the authorization of the county of Tioga to impose an additional one percent of sales and compensating use taxes
Sub-Topics
Sales Tax
S 7420: Relates to Suffolk county sales and compensating use taxes
S 4712: Exempts athletic club membership dues from a sales tax
Sub-Topics
Sales Tax
A 3490: Imposes an excise tax on sugary drinks
Topics
✓ Budget & TaxesSupports Budget & TaxesBill imposes new excise tax on sugary drinks, with revenue funding a community health equity fund, directly advancing fiscal management through new tax revenue allocation for public health programs.
✓ HealthcareSupports HealthcareTax revenue funds a community health equity fund, directly advancing public health initiatives per healthcare funding indicators.
Sub-Topics
Sales Tax
A 7261: Exempts low-emission and energy efficient vehicles from retail sales and compensating use taxes
Topics
✓ Budget & TaxesSupports Budget & TaxesExempts qualifying vehicles from sales tax, providing tax relief funded by emissions auctions, aligning with tax relief indicators.
✓ EnergySupports EnergyExempts low-emission/energy-efficient vehicles from taxes to promote adoption, meeting EPA standards and funded by emissions auctions, directly advancing energy efficiency goals.
✓ EnvironmentSupports EnvironmentExempts low-emission vehicles meeting EPA standards from taxes to reduce emissions, funded by emissions auctions, directly promoting cleaner transportation and climate goals.
✓ TransportationSupports TransportationExempts low-emission vehicles from taxes to promote sustainable transportation, aligning with EPA standards and green vehicle policies.
A 2148: Exempts infant car seats from sales and compensating use tax
A 2453: Relates to a sales tax exemption for zero-emission school buses
Topics
✓ Budget & TaxesSupports Budget & TaxesBill creates tax exemption for school buses, providing sales tax relief to purchasers, aligning with tax relief indicator for Budget & Taxes
✓ EducationSupports EducationExempts zero-emission school buses from sales tax, reducing costs for school districts and supporting school infrastructure/transportation funding. Directly aligns with education topic via Education Law definition and operational cost savings.
✓ EnergySupports EnergyExempts zero-emission school buses from sales tax, reducing costs for clean energy fleet adoption and directly advancing renewable energy infrastructure transition.
✓ EnvironmentSupports EnvironmentBill exempts zero-emission school buses from sales tax, reducing costs to accelerate fleet transition and directly reduce transportation emissions per environmental protection goals.
✓ TransportationSupports TransportationBill promotes sustainable transportation by exempting zero-emission school buses from sales tax, reducing costs for transitioning to eco-friendly fleets per Education Law definitions.