

Issue · Budget & Taxes
Budget & Taxes (Tax Credits)
Every budget & taxes bill, vote, and legislator stance in New York, automatically classified by Maddy, our AI policy reader.
Total bills
362
2025 Regular Session
Top supporter
Joe Addabbo
100% support rate
Top opponent
Rob Ortt
0% support rate
Ranked legislators
10
5 support · 5 oppose
Key legislators
Who's moving tax credits in New York
| Legislator | Party | Stance | Support rate | Decisive votes |
|---|---|---|---|---|
Joe Addabbo
Senate · District 15
|
D |
Strong +
|
100% | 8 |
Leroy Comrie
Senate · District 14
|
D |
Strong +
|
100% | 8 |
April Baskin
Senate · District 63
|
D |
Strong +
|
100% | 5 |
Chris Ryan
Senate · District 50
|
D |
Strong +
|
100% | 5 |
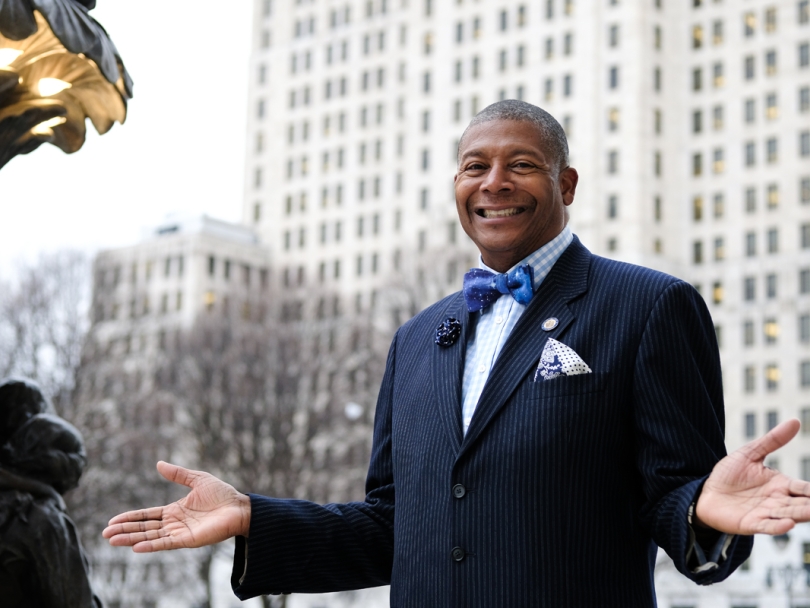
James Sanders
Senate · District 10
|
D |
Strong +
|
100% | 5 |

Rob Ortt
Senate · District 62
|
R |
Strong −
|
0% | 4 |

George Borrello
Senate · District 57
|
R |
Strong −
|
20% | 5 |
Dan Stec
Senate · District 45
|
R |
Oppose
|
25% | 4 |
Joe Griffo
Senate · District 53
|
R |
Oppose
|
25% | 4 |
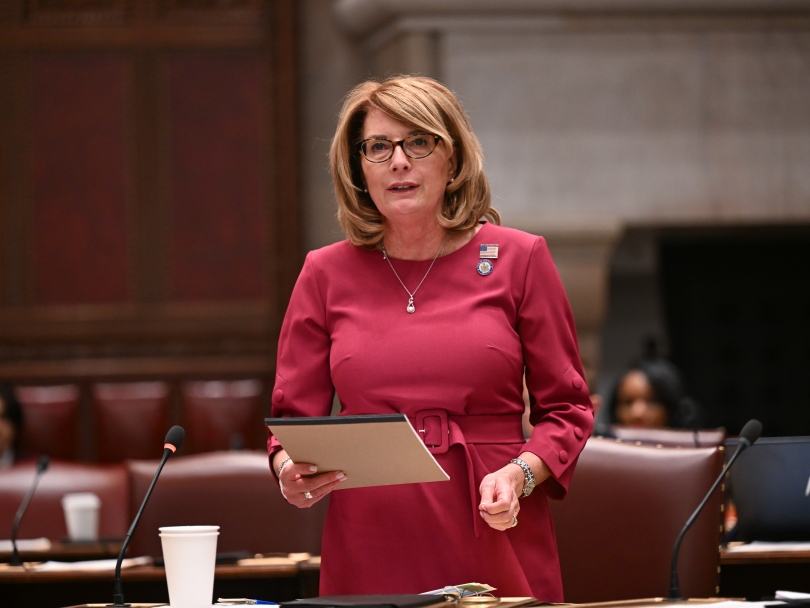
Pam Helming
Senate · District 54
|
R |
Oppose
|
25% | 4 |
Showing 161–170 of 362
bills
All budget & taxes bills
A 288: Relates to the volunteer firefighters' and ambulance workers' credit; repealer
S 3079: Relates to the employee training incentive program
A 1652: Relates to a tax credit for employment of an individual who has successfully completed a judicial diversion substance abuse treatment program or graduated from drug court
Topics
✓ Budget & TaxesSupports Budget & TaxesEstablishes tax credit for employers hiring individuals from substance abuse treatment programs, providing targeted tax relief to incentivize employment in social services.
✓ Criminal JusticeSupports Criminal JusticeProvides tax credit for hiring individuals completing drug court/diversion programs, directly supporting rehabilitation and reducing recidivism through employment opportunities.
✓ HealthcareSupports HealthcareBill provides tax credit for hiring individuals who completed substance abuse treatment, supporting recovery and reintegration into workforce as part of healthcare for substance use disorders.
A 28: Provides tax credit to certain volunteer firefighters, volunteer ambulance workers, volunteer reserve forces officers, auxiliary police officers and volunteer emergency medical personnel
Sub-Topics
Tax Credits
S 2429: Creates a work opportunity tax credit
Topics
✓ Budget & TaxesSupports Budget & TaxesCreates tax credit reducing state tax liability for employers, providing targeted tax relief aligns with support indicators for fiscal policy.
✓ Labor & EmploymentSupports Labor & EmploymentBill incentivizes hiring targeted groups (veterans, ex-offenders) via tax credit, directly advancing employment opportunities for underserved workers.
✓ VeteransSupports VeteransBill explicitly targets veterans as eligible for tax credit to incentivize employer hiring, directly supporting veteran employment opportunities.
A 3221: Creates a tax credit for small businesses that sell a certain percentage of products produced in New York state
Sub-Topics
Tax Credits
A 4955: Establishes a tax credit for homeowners and businesses to build permeable surfaces
Topics
✓ Budget & TaxesSupports Budget & TaxesCreates tax credit reducing tax liability for eligible property improvements, providing direct tax relief under Budget & Taxes framework.
✓ EnvironmentSupports EnvironmentPromotes permeable surfaces to reduce stormwater runoff and pollution, aligning with environmental protection goals.
Sub-Topics
Tax Credits
A 7308: Establishes a sustainable aviation fuel tax credit
Topics
✓ Budget & TaxesSupports Budget & TaxesCreates tax credit for SAF producers, providing tax relief to incentivize sustainable aviation fuel production and reduce emissions.
✓ EnergySupports EnergyBill provides tax credit for sustainable aviation fuel (SAF) producers, incentivizing renewable energy production and carbon reduction in aviation, directly advancing clean energy infrastructure.
✓ EnvironmentSupports EnvironmentTax credit for SAF producers with emission-based incentives directly promotes cleaner aviation fuel and reduces CO2 emissions per bill summary.
✓ TransportationSupports TransportationBill provides tax credits for sustainable aviation fuel producers, directly promoting cleaner transportation infrastructure and emissions reduction in aviation, a key transportation sector.
S 1674: Creates a tax credit for employers who help reduce higher education loans of their employees
Topics
✓ Budget & TaxesSupports Budget & TaxesCreates tax credit for employers reducing student debt, providing tax relief per bill's explicit tax credit mechanism.
✓ EducationSupports EducationBill reduces undergraduate student debt burden via employer tax credits, directly expanding higher education affordability and access for employees.
✓ Labor & EmploymentSupports Labor & EmploymentProvides employer tax credit for reducing employee student debt, enhancing financial stability and expanding non-wage worker benefits per Labor & Employment topic description.