

Issue · Budget & Taxes
Budget & Taxes (Tax Credits)
Every budget & taxes bill, vote, and legislator stance in New York, automatically classified by Maddy, our AI policy reader.
Total bills
362
2025 Regular Session
Top supporter
Joe Addabbo
100% support rate
Top opponent
Rob Ortt
0% support rate
Ranked legislators
10
5 support · 5 oppose
Key legislators
Who's moving tax credits in New York
| Legislator | Party | Stance | Support rate | Decisive votes |
|---|---|---|---|---|
Joe Addabbo
Senate · District 15
|
D |
Strong +
|
100% | 8 |
Leroy Comrie
Senate · District 14
|
D |
Strong +
|
100% | 8 |
April Baskin
Senate · District 63
|
D |
Strong +
|
100% | 5 |
Chris Ryan
Senate · District 50
|
D |
Strong +
|
100% | 5 |
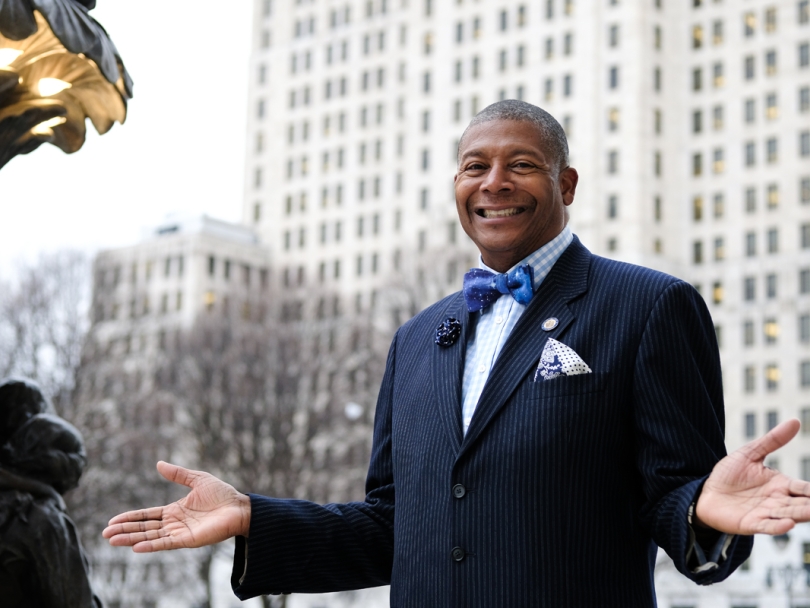
James Sanders
Senate · District 10
|
D |
Strong +
|
100% | 5 |

Rob Ortt
Senate · District 62
|
R |
Strong −
|
0% | 4 |

George Borrello
Senate · District 57
|
R |
Strong −
|
20% | 5 |
Dan Stec
Senate · District 45
|
R |
Oppose
|
25% | 4 |
Joe Griffo
Senate · District 53
|
R |
Oppose
|
25% | 4 |
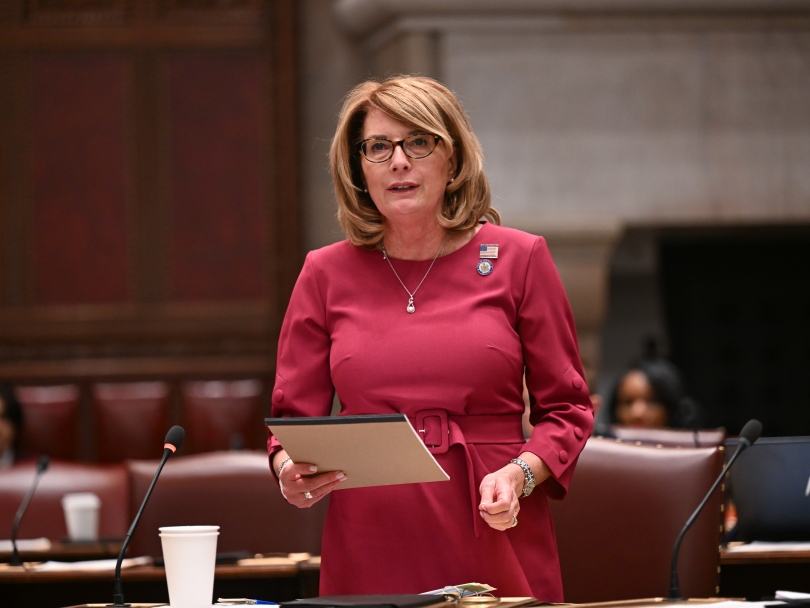
Pam Helming
Senate · District 54
|
R |
Oppose
|
25% | 4 |
Showing 121–130 of 362
bills
All budget & taxes bills
A 3373: Creates a personal income tax credit for taxpayers who pay an excess premium paid during the applicable tax year for flood insurance providing coverage on the taxpayer's primary residence
S 3803: Provides a tax credit for the purchase or conversion of an electric vessel or zero emission vessel and provides a tax credit for electric vessel recharging property
Topics
✓ Budget & TaxesSupports Budget & TaxesProvides tax credits for electric vessel purchases and recharging infrastructure, reducing tax burden through fiscal incentives per bill summary.
✓ EnergySupports EnergyProvides tax credits for electric/zero-emission vessels and recharging infrastructure, directly promoting renewable energy adoption and clean transportation infrastructure.
✓ EnvironmentSupports EnvironmentTax credits for electric/zero-emission vessels directly reduce emissions and promote clean maritime transport, aligning with environmental protection goals.
✓ TransportationSupports TransportationProvides tax credits for electric vessels and recharging infrastructure, promoting sustainable transportation infrastructure innovation within the transportation topic.
A 5182: Enacts the frontline worker assistance act
Topics
✓ Budget & TaxesSupports Budget & TaxesProvides $1,000 tax credit to frontline workers, reducing tax burden as fiscal relief for public employees during pandemic.
✓ Labor & EmploymentSupports Labor & EmploymentProvides $1,000 tax credit to frontline workers without pandemic compensation, directly enhancing financial support for affected laborers during crisis.
Sub-Topics
Tax Credits
A 5439: Establishes an active military service travel credit
Sub-Topics
Tax Credits
A 1373: Increases the amount of residential solar tax credits
Topics
✓ Budget & TaxesSupports Budget & TaxesIncreases residential solar tax credit (26% of costs) with higher max credits, providing direct tax relief to homeowners for renewable energy adoption, aligning with fiscal support for sustainable energy.
✓ EnergySupports EnergyIncreases residential solar tax credits (26%) to boost renewable energy adoption, directly advancing clean energy infrastructure investment per bill's explicit purpose.
✓ EnvironmentSupports EnvironmentIncreases solar tax credits to promote residential renewable energy adoption, directly advancing clean energy use and reducing fossil fuel reliance for environmental protection.
A 7016: Relates to expanding New York's manufacturing tax incentive to S corporations
A 516: Increases the volunteer firefighters' and ambulance workers' credit
S 7643: Relates to the pass-through entity tax credit and the city pass-through entity tax credit
S 3471: Establishes business franchise, personal income and insurance franchise tax credits for the expenses of employer provided or sponsored child care
Topics
✓ Budget & TaxesSupports Budget & TaxesBill establishes tax credits reducing business tax liability for child care expenses, providing direct tax relief under fiscal policy.
✓ Labor & EmploymentSupports Labor & EmploymentProvides tax credits for employer-sponsored childcare, reducing employee costs and supporting work-life balance for workers with childcare needs.