Issue · Budget & Taxes

Budget & Taxes

Every budget & taxes bill, vote, and legislator stance in New Mexico, automatically classified by Maddy, our AI policy reader.

Total bills
235
2026 Regular Session
Top supporter
Nathan Small
100% support rate
Top opponent
Stefani Lord
0% support rate
Ranked legislators
10
5 support · 5 oppose
Key legislators

Who's moving budget & taxes in New Mexico

Legislators moving budget & taxes in New Mexico
Legislator Party Stance Support rate Votes
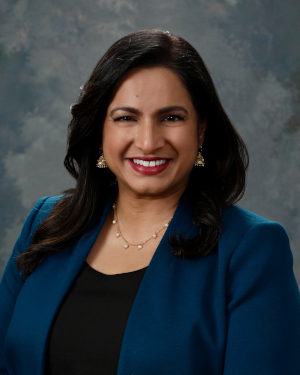
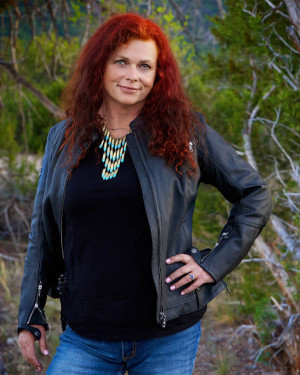
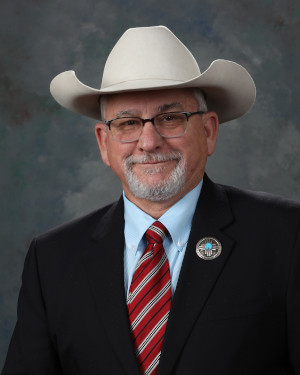
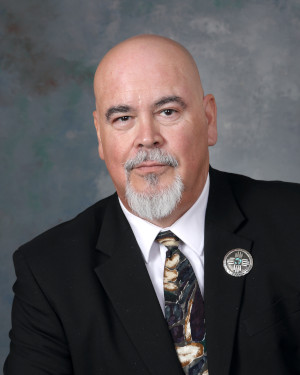
Nathan Small
Nathan Small House · District 36
D
Strong +
100% 21
Art De La Cruz
Art De La Cruz House · District 12
D
Strong +
100% 22
Anita Gonzales
Anita Gonzales House · District 70
D
Strong +
100% 21
Ray Lara
Ray Lara House · District 34
D
Strong +
100% 20
Reena Szczepanski
Reena Szczepanski House · District 47
D
Strong +
100% 22
Stefani Lord
Stefani Lord House · District 22
R
Strong −
0% 17
Randy Pettigrew
Randy Pettigrew House · District 61
R
Strong −
0% 21
Alan Martinez
Alan Martinez House · District 23
R
Strong −
0% 15
John Block
John Block House · District 51
R
Strong −
0% 22
Angelita Mejia
Angelita Mejia House · District 58
R
Strong −
0% 21
Showing 141–150 of 235 bills

All budget & taxes bills

signed · New Mexico · Senate Mar 11, 2026

SB 151: CORPORATE INCOME TAX CHANGES

SB 151 adjusts New Mexico's corporate tax calculation to better align with federal rules for certain income types. It modifies the state's definition of "base income" by adding back specific federal deductions (like interest from state bonds) and subtracting amounts for bonus depreciation and interest expenses that the federal government allows. This bill directly affects corporations operating in New Mexico that file federal tax returns, particularly those with income from controlled foreign corporations. The key change ensures New Mexico's tax calculation accounts for federal adjustments related to foreign income and depreciation, while applying standard apportionment rules to attributed income.
in committee · New Mexico · Senate Mar 24, 2026

SB 174: GOLD & SILVER SALE GRT DEDUCTION

This bill allows New Mexico businesses selling gold or silver coins or bullion to deduct those sales from their gross receipts tax (a tax on business sales) until July 1, 2031. It specifically defines "bullion" as metal bars, ingots, or commemorative medallions where value depends on metal content, not form. Taxpayers must report these deductions to the state, and the cost of the deduction will be tracked in annual tax expenditure reports. The bill applies directly to businesses engaged in selling qualifying gold or silver products.
in committee · New Mexico · Senate Mar 24, 2026

SB 9: MEDICAID TRUST FUND

SB 9 authorizes a $1 billion transfer from New Mexico's general fund to the Medicaid Trust Fund for fiscal year 2027. This funding directly supports the state's Medicaid program, which provides healthcare coverage to low-income residents, including children, seniors, and people with disabilities. The bill establishes a specific financial mechanism to replenish the Medicaid Trust Fund, ensuring stable funding for healthcare services without altering eligibility rules or program structure. It does not create new benefits or change how Medicaid operates, only providing a dedicated funding source. The transfer is scheduled for implementation in the 2027 fiscal year.
Sub-Topics State Budget Medicaid
passed · New Mexico · Senate Mar 24, 2026

SB 35: CREATE ADDITION 1ST DISTRICT JUDGESHIP

SB 35 creates an additional judgeship in New Mexico's First Judicial District, increasing the number of district judges from ten to eleven. The bill appropriates $451,400 from the state general fund for fiscal year 2027 to cover the new position's costs, including the judge's salary, benefits, and office equipment. Unspent funds at year-end will revert to the general fund. This change directly affects the First Judicial District court system by expanding its judicial capacity to handle caseloads.
in committee · New Mexico · House Mar 24, 2026

HB 40: TEMPORARY ERB MEMBER PAYMENT

HB 40 provides a temporary 2% additional payment to retired members receiving annuities under New Mexico's Educational Retirement Act for fiscal years 2027 and 2028. This payment, calculated as 2% of each retiree's current annual benefit amount (including prior cost-of-living adjustments), is non-compounding and separate from standard annual adjustments. It applies to all retired educators under the Act, excluding those on disability status or under specific retirement provisions. The bill does not alter existing cost-of-living adjustment rules but adds this short-term benefit for two years.
in committee · New Mexico · Senate Mar 24, 2026

SB 124: HIGHER ED. MAJOR PROJECTS FUND

SB 124 creates a new state fund to support major capital projects at New Mexico's public colleges and universities. The fund finances research/instruction facilities costing $50 million or more at four-year universities, and student housing/life projects (like recreation centers and dining halls) at all public institutions. Projects must meet matching requirements (10-50% from non-state sources like bonds or fees), with waivers possible if institutions can't afford the match. The bill also requires graduation rate data for Division I athletic facility projects and mandates documentation on student population needs for new facilities.
Sub-Topics Higher Education
in committee · New Mexico · Senate Mar 24, 2026

SB 52: PERA COST-OF-LIVING ADJUSTMENTS

SB 52 (PERA Cost-of-Living Adjustments) changes how cost-of-living adjustments (COLAs) are calculated for New Mexico public retirement pension recipients. It requires that starting July 1, 2027, pension increases equal the Social Security and Supplemental Security Income (SSI) COLA rate determined by the federal government each year, instead of the previous method. This directly affects retirees who meet specific duration requirements (e.g., retired for 2 years, or age 65+ for 1 year), as well as survivor beneficiaries. The bill appropriates $50 million from the general fund for fiscal year 2027 to fund these adjustments, with unspent funds carrying forward to future years.
Sub-Topics Pensions State Budget
signed · New Mexico · House Mar 10, 2026

HB 80: OIL & GAS CONSERVATION TAX ACT CHANGES

HB 80 increases funding for New Mexico's Oil and Gas Reclamation Fund by raising the tax distribution percentage from 2/19% to 50% starting July 2027, gradually increasing to 100% through 2037 before returning to 50% after 2037. The bill directly affects oil and gas operators (through higher tax contributions) and the state's energy department (which administers the fund). Key provisions include expanding fund use to cover energy education programs ($150,000 annually) and requiring the department to plug abandoned wells, restore sites, and pursue cost recovery from operators. Funds will be managed under the Energy, Minerals and Natural Resources Department with annual reporting requirements.
Sub-Topics Conservation
in committee · New Mexico · House Mar 24, 2026

HB 62: RENAME & CREATE GEOTHERMAL TAX CREDITS

HB 62 renames New Mexico's geothermal electricity generation tax credits to "geothermal energy production" credits and establishes a tiered credit system based on kilowatt-hour output. It provides tax credits ranging from $0.015 to $0.035 per kWh (increasing over the first five years then decreasing), capped at 200,000 megawatt-hours per facility annually. The bill limits total annual credits to $55 million, reserving $11 million for tribal and small businesses, and allows credit transfers between taxpayers. This directly affects geothermal energy producers in New Mexico who own facilities generating electricity from geothermal resources.
in committee · New Mexico · House Mar 24, 2026

HB 187: RURAL HOSPITAL MALPRACTICE LIABILITY INS. ACT

HB 187 creates a state-funded grant program to help rural hospitals cover medical malpractice insurance premiums. Eligible hospitals - defined as those licensed in rural or frontier areas operating within health care underserved regions - can apply for grants to pay for approved malpractice insurance. The bill appropriates $66 million for fiscal year 2026 and subsequent years, with unspent funds not reverting to the general fund. The Department of Health will administer the program, requiring hospitals to use grant money solely for premiums and submit annual reports on financial stability, staffing, and patient access.
Showing 141 to 150 of 235 bills
Previous 1 14 15 16 24 Next